2024 EN

Implementation of the vat corrective self-assessment:a step towards tax simplification

The Ministry of Finance has introduced a new system for correcting VAT self-assessments, allowing taxpayers to modify their declarations without having to wait for an official response. This change simplifies the process and facilitates the correction of errors or necessary adjustments in self-assessments.

This new system is part of an amendment to the General Tax Law made in 2023, which introduced corrective self-assessments to replace the previous correction method. In May 2024, an order was published formalizing these changes in the VAT declaration models, specifically models 303 and 308.

The new model 303 includes two key fields: Field 108, for adjustments due to discrepancies with administrative criteria, and Field 111, which differentiates between refund requests based on tax regulations and other requests. This model will be used starting September 2024 for those who file VAT monthly and from the third quarter of 2024 for those who file quarterly.

While the aim is to streamline the rectification process, it remains unclear how the tax authorities will handle these changes, particularly regarding the documentation required to justify corrections. Therefore, it is advisable for taxpayers to seek guidance to ensure compliance with all legal requirements. For any questions or inquiries, please contact MDG Advisors, and we will be pleased to assist you with this matter.


Sandra Gámez Chaves

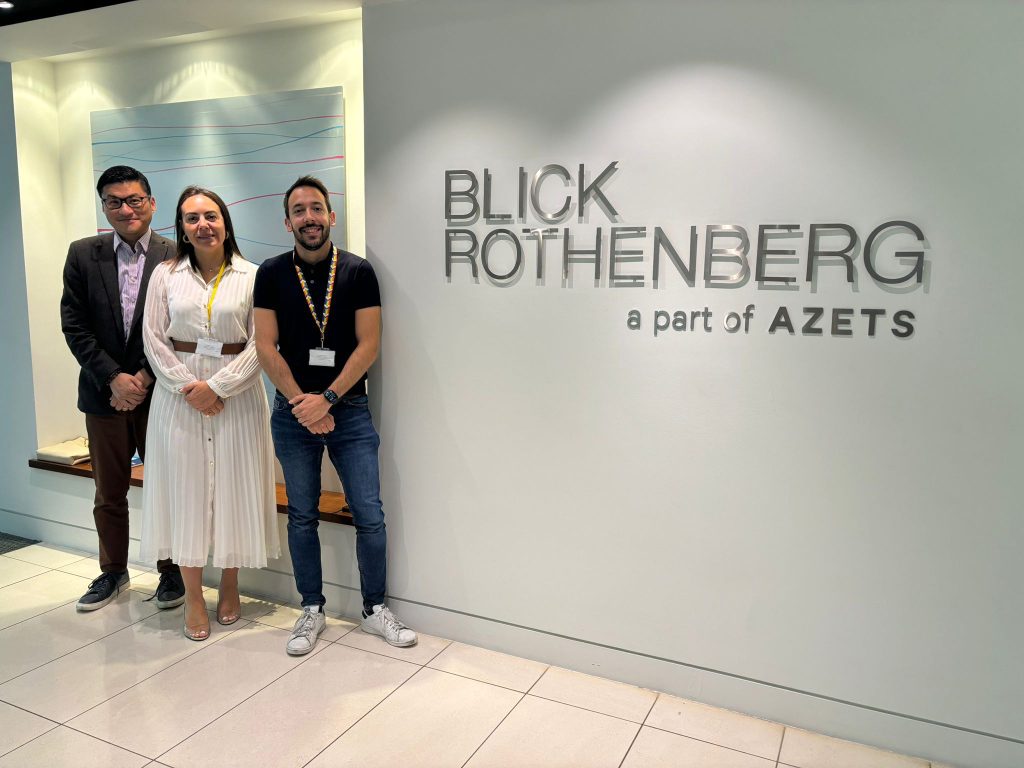
Miriem Diouri García’s Visit to Blick Rothenberg in London to Explore Market Synergies

We are pleased to share that our Managing Partner, Miriem Diouri García, visited the offices of Blick Rothenberg in London. Blick Rothenberg is a company with a long-standing reputation in accounting and taxation, known for its expertise and professionalism.

During the visit, Miriem had the opportunity to meet with the Blick Rothenberg team to explore potential synergies between both markets. This collaboration represents an important step towards strengthening our international relationships and exploring new opportunities for our clients.

We are excited about the potential of this alliance and the benefits it may bring to both organizations. We will continue to work closely together to provide innovative and effective solutions in the field of accounting and taxation.

Happy Holidays and Happy New Year 2025 !

Dear customers, partners and friends,

As 2024 comes to a close, we would like to express our sincere thanks for your trust and support throughout this year. It has been an incredible year that would not have been possible without each and every one of you.

It is with great excitement that we look forward to the new year 2025, when we will celebrate the 15th anniversary of our firm. We are excited to continue growing and evolving together with you, always committed to offering the best service, quality and innovation.

We wish you a happy holiday season full of joy and a prosperous new year. May 2025 be full of success and unforgettable moments.

Thank you for being part of our history!

With best wishes,

MDG Advisors team.

Normative modifications in ITP in the acquisition of a squatted property: acquisition value or reference value

It is noticeable that the Christmas holidays are approaching, with the illusion in the streets full of people, the children running down the street, the Christmas lights of our beloved Calle Larios, and from MDG Advisors, we want to join in that joy, and inform you of a recent consultation of the Directorate General of Taxes, which on this occasion, is not to the detriment of the taxpayer.

As we know, and this is nothing new, article 10 of the revised text of the Law on Transfer Tax and Stamp Duty, approved by Royal Legislative Decree 1/1993, of 24 September, establishes that ‘the taxable base is constituted by the value of the property transferred or of the right that is constituted or transferred’.

In the case of real estate, its value will be the reference value provided for in the regulations governing the land registry, at the date of accrual of the tax.

However, if the value of the real estate declared by the interested parties, the price or agreed consideration, or both, are higher than the reference value, the higher of these values will be taken as the taxable base.

And in line with the above, and with the aim of providing you with the good news that we mentioned at the beginning of the blog, the Directorate General of Taxes in the binding consultation V2002-24, establishes that in cases where a property is acquired that is occupied, tax may be paid on the acquisition of the same at the acquisition value instead of the reference value, representing a tax saving for the taxpayer, since normally when a property is acquired that is occupied, the acquisition value is lower than the value determined by the Cadastre (reference value).

This is due to the fact that according to the Resolution of the General Directorate of Cadastre, in the case of residential real estate, where there is no legal regime regulating the relationship between owner and occupier (when the two do not coincide), and this prevents the free disposal of the property by the owner, this is a situation which may imply, where applicable, that the reference value of a real estate does not exist.

Taking into account this change of criteria, we are reviewing all the deeds of purchase of real estate that our clients have made in order to request the return of undue income in favour of our clients.

If you find yourself in a similar situation, we remain at your disposal to provide you with the best advice on the regularisation of your tax situation.

Leticia Cayuela Mayor

Malaga: The Boom as Best Expatriate Destination

In recent years, Malaga has established itself as one of the most attractive destinations for expatriates from all over the world. According to a study published by Internations, an expat website with more than 5 million users, Malaga has been voted the best expat destination worldwide.

From its vibrant cultural life and enviable climate to its growing infrastructure and the quality of life it offers, this Andalusian city has earned a top spot on lists of the best places to live outside your home country. So what makes Malaga so special for expats? Let's break it down.

···

One of Malaga biggest attractions is its Mediterranean climate. With over 300 days of sunshine a year, the city is a paradise for those looking to escape the cold winters and constant rain. Mild temperatures throughout the year allow for outdoor living, whether on the beach or strolling in the nearby parks and mountains. This not only improves the quality of life, but also has a positive impact on overall health and well-being.

Attractive Cost of Living

Compared to other major European cities, the cost of living in Malaga is relatively low. Although prices have increased in recent years due to the growing interest in the city, it is still more affordable than other destinations such as Madrid, Barcelona, London or Paris. Est

The Expatriate Community in Malaga

The presence of a growing expatriate community has been one of the driving forces behind Malaga rise as a preferred destination. Increasing numbers of British, German, French, Nordic, and other nationalities are moving to the city, creating a vibrant cultural mix. This phenomenon has prompted the creation of groups, associations and services to help new residents integrate, share experiences and adapt to their new home.

In addition, the Spanish language is a great asset for expatriates who wish to learn Spanish and immerse themselves in the local culture. Many expatriates take advantage of Spanish classes and other services to facilitate their integration.

Professional and Business Opportunities

Although Malaga was historically known as a tourist destination, in recent years it has experienced a boom in the technology and business sector. The growth of technology companies, startups and the development of spaces such as the Parque Tecnológico de Andalucía (PTA) have attracted entrepreneurs and professionals in the digital sector.

The city is also known for being an excellent connection point for international business due to its proximity to Africa and the rest of Europe. Business initiatives and events have multiplied, making Malaga a hub of opportunities for expatriates looking to develop professionally.

For all of the above reasons, Malaga is the perfect destination for expatriates looking for a mix of sunshine, quality of life, a welcoming international community and professional opportunities. Its climate, infrastructure, competitive cost of living and relaxed lifestyle have
made this Andalusian city one of the most sought after for those wishing to start a new life in Spain. With more and more foreigners choosing Malaga as their home, the city continues to evolve, living up to its title as one of the best expatriate destinations in Europe.

Pablo Mallo Bárcena – MDG Advisors

Technological boom drives growth in traditional sectors in Malaga

Business Malaga is benefiting from the demand for services in the technology sector Consultancies, law firms, international schools, offices, furniture shops and real estate agencies are growing in the heat of this specific clientele.

Technological Malaga is a reality that is more than established in the local economy and can be seen from different perspectives. One of them is the direct and indirect impact that the ‘tech’ sector is having on the more traditional business fabric, in many cases reconverted to supply products and services to a type of client with very specific and mostly international needs. From consultancies to furniture shops, the technological manna is feeding different types of companies in Malaga.

Discovering the Economic Activities Tax (IAE)

In the world of taxes, the Tax on Economic Activities occupies a special place in Spain. This local tax is levied on the exercise of business, professional or artistic activities. Therefore, if you are doing business in Spanish territory, the IAE is something you should be aware of.

Entities with a net turnover of €1,000,000 or more are obliged to file a tax return. This applies both to local companies and to Non-Resident Income Tax (IRNR) taxpayers operating in Spain through a permanent establishment.

To calculate the INCN, all the economic activities you carry out are taken into account. If you are part of a group of companies, the INCN is calculated taking into account all the entities in the group.

The management of the IAE is mainly the responsibility of the local councils, and those entities that must file the tax return will do so by means of form 840 for the additions, cancellations or variations to be reported on an annual basis.

It is important to mention that not all taxpayers are obliged to pay IAE, and there are several important exemptions to take into account:

– State, autonomous communities and local entities.

– Entities that start a new activity in Spain will not have to pay IAE during the first two years.

– Individuals

– Entities with an INCN of less than 1.000.000 €.

– Entities managing the Social Security.

– Public research bodies and certain educational establishments

– Associations and foundations dedicated to the assistance and rehabilitation of people with disabilities. In this case, it has a mandatory nature

– Spanish Red Cross.

– There are exemptions included in certain international agreements.

This December it is especially important to review the obligations of this tax, as if an entity previously enjoyed one of the exemptions listed above and as of 2025 knows that it will no longer do so, it must notify this in December. If you have any doubts about this ·procedure, MDG Advisors is at your disposal.

Isabel María Díaz Rubio

What’s new in the draft law for a new tax reform.

oday, the new tax reform is being debated in Congress, which may bring with it important measures for taxpayers who are affected by it, in the event of its final approval in the Plenary.

Among the measures that have been debated in this tax reform, the following stand out:

a) Tax cuts for SMEs and micro-SMEs: Progressive rates will be established to reduce the taxation of companies, with a significant reduction in the coming years.

b) Increase in capital income: the taxation of savings income in personal income tax (IRPF) will be increased from 28% to 30%.

c) Tax relief for recapitalisations: Companies, both large and small, will be able to reduce their corporate income tax base depending on their recapitalisation. This relief may be up to 30% of the increase in equity if the company increases its workforce by 10%. The reduction could be up to 20% of the tax base, or 25% in the case of SMEs.

d) Reductions in corporate tax: progressive reduction in the tax rate for companies with a turnover of less than one million euros.

Other measures that have been debated during these days and that will have to await final approval are the tax on energy companies, the tax on banks and the tax on tourist rentals, among others.

At MDG Advisors we will keep a close eye on the latest developments in the tax reform project to find out which measures are finally approved and to analyse how they will affect the taxation of our clients and anyone else who requests it. Do not hesitate to contact our MDG Team for more information.

Jesús Raya Zamora.

The tax on large inheritances

For some days now, Congress has been debating the introduction of a new tax: the tax on large inheritances.

The party SUMAR has brought the debate to the table of the Congress, demanding the approval of this new tax as a fundamental requirement to give its support to the Government in the approval of the general budgets.

This new state tax would mean the harmonization of Inheritance and Gift Tax, forcing all inheritances and gifts over one million euros to be taxed, regardless of the relationship between the parties and the Autonomous Community of residence.

As already happened with the Wealth Tax and the Solidarity Tax for large fortunes, this new proposal is already generating a lot of commotion among taxpayers and deep controversy in the world of tax advice. For this reason, at MDG Advisors we will continue to report on the status of this tax proposal.

Pablo Mallo Bárcena

Countdown to comply with the new obligations on electronic invoicing – “VERIFACTU”··

After finishing the third tax quarter and already with a view to complying with the census obligations that November brings with it with the Tax Agency and checking the obligations entailed by Form 232 – Informative declaration of related transactions and of transactions and situations related to countries or territories qualified as tax havens, we have had to stop with a new publication in the BOE, as the countdown to comply with the new obligations on electronic invoicing (known as Verifactu) has begun.

On October 28, 2024, Order HAC7/1177/2024, of October 17, 2024, was published in the BOE, developing the technical, functional and content specifications referred to in the Regulation that establishes the requirements to be adopted by the computer or electronic systems and programs that support the invoicing processes of businessmen and professionals, in force since October 29, 2024.

The publication of this Ministerial Order means the beginning of the computation of the maximum period of nine months in which manufacturers and marketers of invoicing systems for businessmen and professionals must market products adapted to the regulation, so this period will end on July 29, 2025.

However, it is expected that the deadline will be delayed until January 1, 2026 for corporate taxpayers and July 1, 2026 for individuals with economic activity, according to the proposed amendment of the Verifactu Regulation that has been published in the prior public consultation process, but as it is not a final text, it may undergo modifications until its official publication.

The most important objectives of this Ministerial Order are:

  • To reinforce the obligation to issue invoices for all transactions carried out by businessmen and professionals.
  • To ensure that all transactions are recorded in the computer system in a secure, non- manipulable, accessible manner and with a standard structure and format to facilitate the legibility of the records, the automated analysis and the simultaneous submission to the Tax Administration.
  • Facilitate compliance with tax obligations.

It should be noted that this obligation to exchange invoices automatically with the Treasury affects companies with a turnover of less than 6 million euros, since those that exceed that figure are already obliged to send the information to the Treasury through the SII since the 2017 financial year.

From our firm we will take care of updating this information so that our clients can properly comply with the deadlines involved in the well-known Verifactu.

Leticia Cayuela Mayor