

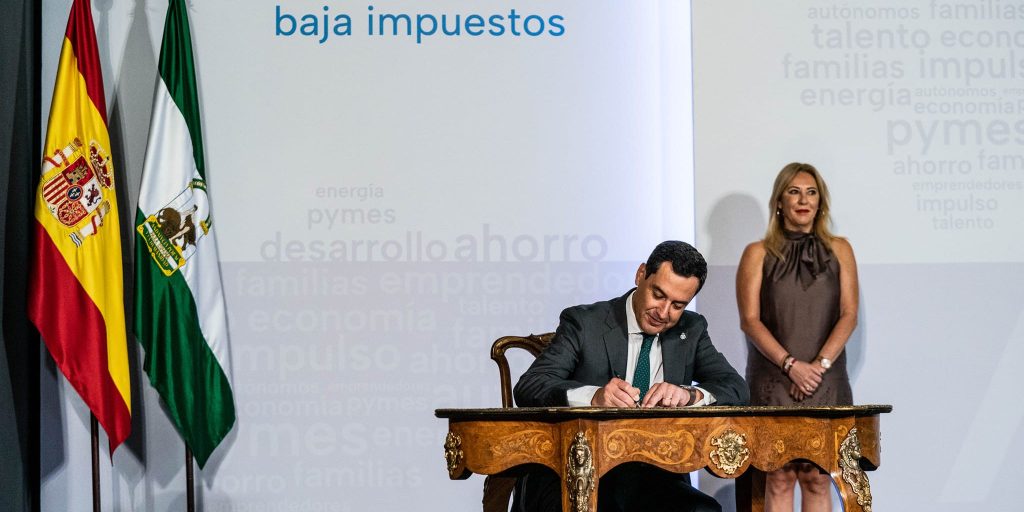
Andalusia abolishes wealth tax and deflates the regional rate of personal income tax.
As we mentioned a few days ago, the Andalusian government, led by Juanma Moreno, announced new tax measures for Andalusians. On 21 September 2022, Decree-Law 7/2022 of 20 September was published in the Official Gazette of the Andalusian Regional Government, amending Law 5/2021 of 20 October on Taxes Assigned by the Autonomous Community of Andalusia, which comes into force on 22 September.
The most important measures included in the aforementioned law are as follows:
1.- Wealth Tax.
With effect from 2022, a 100% regional rebate is introduced, which will be applied to the positive tax liability resulting from the application of the deductions and rebates regulated by state legislation.
2.- Personal Income Tax.
With regard to the regional part and with effect from 1 January 2022:
Regional scale: The regional scale applicable to the general taxable base is deflated, raising the amounts of its first three brackets and remaining as follows:
Taxpayer and family minimums. The amounts of the personal and family minimums are increased:
- The taxpayer’s minimum will generally amount to 5,790 euros per year. However, when the taxpayer is over 65 years of age, the minimum will be increased by 1,200 euros per year; and if the taxpayer is over 75 years of age, the minimum will be increased by an additional 1,460 euros per year.
- The minimum for descendants for each of said descendants who are under 25 years of age or disabled (whatever their age), provided that they live with the taxpayer and do not have an annual income (excluding exempt income) of over 8,000 euros, shall be:
2,510 euros per year, for the first descendant.
2,820 euros per year for the second descendant.
4,170 euros per year for the third descendant.
4,700 euros per year for the fourth and subsequent descendants.
When the descendant is under three years of age, the minimum will be increased by an additional 2,920 euros per year.
- The minimum for ascendants will be 1,200 euros per year for each ascendant over 65 years of age or disabled (whatever the age), who lives with the taxpayer and does not have an annual income (excluding exemptions) of more than 8,000 euros. When the ascendant is over 75 years of age, this amount will be increased by 1,460 euros per year.
- The minimum for disability will amount to the following amounts:
- Disability of the taxpayer:
3,130 euros per year, in general.
9,390 euros per year, if the taxpayer proves a degree of disability equal to or greater than 65%.
The minimum will be increased by 3,130 euros per year for assistance expenses, when the taxpayer proves the need for assistance from third parties or reduced mobility, or a degree of disability equal to or greater than 65%.
- Disability of ascendants or descendants:
3,130 euros per year, in general, for each of the disabled ascendants or descendants, whatever their age.
9,390 euros per year, for each of said ascendants or descendants who accredit a degree of disability equal to or greater than 65 per cent.
This minimum will also be increased by 3,130 euros per year for assistance expenses, for each ascendant or descendant who accredits needing help from third parties or reduced mobility, or a degree of disability equal to or greater than 65%.
3.- Deferrals and instalments.
Various measures have been regulated to make the conditions for deferrals and instalments more flexible. Among these measures is the increase to twelve years of the maximum period for granting deferrals and instalments, provided that the resolution corresponds to the Tax Agency.
Exceptional measures are also regulated to exceed the twelve-year threshold, subject to authorisation by the Governing Council, in cases in which the Presidency of the Regional Government is responsible for the amount involved.
These measures will be applied to those requests for deferment and instalments that are being processed at the date of entry into force of Decree-Law 7/2022.
For more information and to find out how you could benefit from these measures, please do not hesitate to contact our MDG Team.
Abolition of wealth tax in andalusia.
Juanma Moreno, president of the Junta de Andalucía, has announced the abolition of the Wealth Tax.
On the one hand, in the coming days, the regional government intends to abolish the wealth tax in Andalusia by subsidising it by 100%, as has already been done in the Community of Madrid, in an attempt to reduce the tax burden and thus attract more investment.
On the other hand, regarding the regional part of the Personal Income Tax, the government intends to deflate the rate in the first three income brackets and will increase by 3.5% the amounts exempt from taxation by this tax.
At MDG Advisors we will be keeping a close eye on any new developments regarding these tax measures. If you have any questions, please do not hesitate to contact our team.
Presentation of our new brand mdg advisors
Dear clients:
We are contacting you to inform you that we have recently made a change in our corporate image, becoming MDG Advisors.
Due to the growth we have experienced in the last few years not only nationally but also internationally, the new brand aims to respond to this development in a global and solid way without leaving behind our already consolidated principles and values.
This change has also affected the corporate emails of our professionals. That is why, from now on, any communication with our team will be done through @mdgadvisors.es, with the name of the professional assigned at the beginning, as we were doing before. Please note that our old @mdgasesores.com emails are no longer operational as of today, so we cannot guarantee the reception of any information sent to this address.
MDG Advisors will continue working in our constant search for excellence.
Yours sincerely,
MDG Advisors Team.
New law 12/2022: pension plans and their tax implications
On 1 July, Law 12/2022 of 30 June came into force in the Official State Gazette (BOE), regulating the promotion of occupational pension plans, which brings with it a series of tax implications, both in Income and Corporate Income Tax, as well as in Wealth Tax.
What are these tax implications?
– Personal income tax:
In relation to Personal Income Tax, a new limit is established for reducing the taxable base for contributions and contributions to social welfare systems in addition to the general limit of €1,500 per year, and applicable to contributions to simplified employment pension plans for self-employed or newly created self-employed workers and, on the other hand, of bringing the tax treatment of pan-European individual pension products (regulated in Regulation (EU) 2019/1238, of the European Parliament and of the Council, of 20 June 2019) into line with that of pension plans.
– Corporate income tax.
In relation to this tax, a new deduction of 10% is regulated in the gross tax liability for company contributions to company social welfare systems attributed in favour of workers with gross annual remuneration of less than 27,000 euros.
If the remuneration is equal to or higher than the aforementioned amount, the new deduction will be applied to the proportional part of those contributions that correspond to the gross annual remuneration received.
– Wealth Tax.
The exemptions typified in this tax are extended and this exemption is included for economic rights derived from contributions to pan-European individual pension products, as mentioned above in the case of personal income tax. This corrects the discrimination that has existed up to now against pension plans constituted in another EU Member State.
All these repercussions will have a positive impact on the taxation of taxpayers who have a pension plan constituted outside the European Union, in addition to the domestic implications.
If you have a pension plan, do not hesitate to ask our professionals about the new tax implications and how you can benefit from them.
New tax forms for monitoring cryptocurrency transactions
Recently, the Tax Agency has approved two new forms, 172 and 173, in order to carry out a more exhaustive monitoring of the traffic of virtual currencies and their declaration.
Both forms are for the informative declaration of virtual currency balances (172) and for the informative declaration of transactions with virtual currencies (173).
The filing deadlines for both forms will be annual and must be filed in January of the year following the year to which the information declared corresponds.
MDG Asesores will be happy to help you and answer any questions you may have regarding the possession of virtual currencies.
To access the complete link to the Tax Agency, click here (in Spanish).
Virtual currencies and their tax implications
For years, virtual currencies, also known as cryptocurrencies, have been increasingly present in different transactions in national and/or international commerce and have always been exempt from taxation.
However, one of the new features of the 2021 income tax return is the declaration of cryptocurrencies through a specific box for this purpose, thus raising various questions or doubts about these monetary instruments.
Due to this and the repercussions they are having on tax matters, we feel it is necessary to briefly analyse their declaration to the Treasury in each of the taxes that could affect them:
– Personal Income Tax.
In Personal Income Tax, there may be different cases in which the income can be attributed to one or other of the incomes of this tax, depending on the origin of this income:
- Income from Movable Capital: in this income, interest, stacking (works similar to a fixed-term deposit) or other income generated by cryptocurrencies would have to be declared.
- Income from economic activities: in this case, if a person mines cryptocurrencies, it is understood that he/she is carrying out an economic activity (he/she would have to register with the IAE) and will be taxed on income from economic activities, as the Directorate General of Taxes has pointed out in recent consultations.
- Capital Gains and/or Losses: it goes without saying that the mere purchase of cryptocurrencies does not imply their declaration in the IRPF as there is no capital variation until the moment of their sale.
That said, as with shares, a sale of cryptocurrencies will be taxed as Capital Gains and Losses, for the difference between the transfer value and the acquisition value to be computed in the Savings Tax Base. If instead of sale it is an exchange, the valuation rules for exchanges will be applied and it will be included in the Savings Tax Base. If there are partial sales acquired at different times, the FIFO method will be applied to calculate the capital gain or loss.
– Wealth Tax.
In this case, if an asset (excluding the main residence) exceeds 700,000 Euros, including a certain amount of cryptocurrencies, they must be declared in this tax as would be done with a capital in foreign currency, valued at market price on the date of accrual of the tax.
– Form 720.
The controversial Form 720, which we have already dedicated an entry in our blog to the recent jurisprudential dispute, is not subject to the declaration of cryptocurrencies held abroad in the financial year 2021. This is what the AEAT has recently stated in an informative note in which it declares that “the 720 model does not report virtual currencies […] and is not required for the 2021 financial year”.
However, everything suggests that it will be for the financial year 2022, as it is a requirement established in the recent anti-fraud law. In addition, the possibility is being considered that the Tax Agency may prepare an autonomous information obligation of Form 720 for the declaration of cryptocurrencies abroad. What many experts in the field have dubbed form 721.
– Value Added Tax.
In relation to VAT, the transfer of virtual currencies is exempt from taxation in accordance with Article 20.1.18 of the VAT Law, as the Directorate General for Taxation has stated in various consultations (V1885-21), considering cryptocurrencies to be foreign currency and hence their exemption.
In conclusion, cryptocurrencies, regardless of their type or origin (Bitcoin, Ethereum, Dogecoin, Binance Coin, etc.), are beginning to be targeted by the Tax Agency to avoid any type of tax evasion in our country, so if you are a user of these types of currencies and have doubts about the taxation of these monetary instruments, do not hesitate to contact our MDG team to solve all your questions.
Las monedas virtuales y su implicación fiscal.
Desde hace años, las monedas virtuales, o también llamadas criptomonedas, han venido acompañando cada vez con más presencia las distintas transacciones en el comercio nacional y/o internacional y siempre ajenas a su tributación.
No obstante, una de las novedades de la declaración de la Renta de 2021 es la declaración de las criptomonedas a través de una casilla específica para ello, suscitando así diversas cuestiones o dudas acerca de estos instrumentos monetarios.
Debido a ello y a la repercusión que están alcanzando en materia tributaria, vemos necesario hacer un breve análisis de su declaración a la Hacienda Pública en cada uno de los impuestos que les pudiese afectar:
- Impuesto sobre la Renta de las Personas Físicas.
En el IRPF pueden darse distintas casuísticas para imputar la renta en uno u otro de los rendimientos de este impuesto, según la procedencia de esta renta:
-
- Rendimientos de Capital Mobiliario: en este rendimiento, habría que declarar los intereses, stacking (funciona similar a un depósito a plazo fijo) u otros rendimientos generados por criptomonedas.
- Rendimientos de Actividades Económicas: en este caso, si una persona se dedica al minado de criptomonedas, se entiende que realiza una actividad económica (tendría que darse de alta en el IAE) y tributará por rendimientos de actividades económicas, como ha señalado la Dirección General de Tributos en recientes consultas.
- Ganancias y/o Pérdidas Patrimoniales: huelga decir, que la mera compra de criptomonedas no implica su declaración en el IRPF al no haber una variación patrimonial hasta el momento de su venta.
Dicho esto, al igual que ocurre con las acciones, una venta de criptomonedas tributará como Ganancias y/o Pérdidas Patrimoniales, por la diferencia entre el valor de transmisión y el de adquisición a computar en la Base Imponible del Ahorro. Si en lugar de venta es una permuta, se aplicará las reglas de valoración de las permutas y se integrará también en la Base Imponible del Ahorro. Si se produjesen ventas parciales adquiridas en distintos momentos, se aplicará el método FIFO para el cálculo de la ganancia o pérdida patrimonial.
- Impuesto sobre el Patrimonio.
En este caso, si un patrimonio (excluyendo la vivienda habitual) supera los 700.000 Euros entre las que se incluyen una determinada cantidad de criptomonedas, las mismas deberán ser declaradas en este impuesto al igual que se haría con un capital en divisas, valorándose a precio de mercado a la fecha de devengo del impuesto.
- Modelo 720.
El polémico modelo 720, que ya hemos dedicado en nuestro blog una entrada a la reciente disputa jurisprudencial del mismo, no es objeto para la declaración de las criptomonedas que se encuentren en el extranjero en el ejercicio 2021. Así lo ha señalado recientemente la AEAT en una nota informativa en la que declara que “en el modelo 720 no se informa de monedas virtuales […] y no es exigible respecto al ejercicio 2021”.
No obstante, todo apunta a que sí lo sea para el ejercicio 2022, ya que es una exigencia establecida en la reciente ley antifraude. Además, se baraja la posibilidad de que la Agencia Tributaria prepare una obligación informativa autónoma del modelo 720 para la declaración de las criptomonedas en el extranjero. Lo que muchos expertos en la materia han bautizado como el modelo 721.
- Impuesto sobre el Valor Añadido.
En relación al IVA, la transmisión de las monedas virtuales están exentas de tributación de acuerdo al artículo 20.1.18º LIVA, como así lo ha venido señalando la Dirección General de Tributos en diversas consultas (V1885-21) al considerar a las criptomonedas como divisas y de ahí, su exención.
En conclusión, las criptomonedas, con independencia de la tipología o procedencia de las mismas (Bitcoin, Ethereum, Dogecoin, Binance Coin, etc.), empiezan a estar en miras de la Agencia Tributaria para evitar cualquier tipo de evasión fiscal en nuestro país, por lo que, si eres usuario de este tipo de monedas y tienes dudas acerca de la tributación de estos instrumentos monetarios, no dudes en ponerte en contacto con nuestro equipo MDG para solventar todas tus cuestiones.
Taxation on vacant properties owned by non resident companies in spain : changes in tax office criteria
During the latest years, it has been (surprisingly) understood by the Tax Authorities in Spain, that a property situated in our country owned by a Non Resident entity, was supposed to “generate” rental income in Spain, for the mere availability of the asset for related parties such as directors or shareholders of the entity, and consequently, the entity had to pay Non Resident Taxes in our country.
The criteria of the Tax Authorities has been maintained during a long period, and it was supposing that the foreign entities had to declare in Spain rental income when the real estate assets were used by nobody, at market values.
A recent tax consultation of “Dirección General de Tributos” (consulta vinculante v2993-21 ), has led to a massive change on this criteria : the entities will not have to pay taxes in Spain if the properties have been vacant and the company can prove it sufficiently.
This change of criteria will minimize significantly the tax cost of having a property in Spain, owned by a foreign entity.
We trust you find this information useful, and we remain at your disposal for any clarification you may need.
MDG Advisors – Non Residents Department
Tributacion de propiedades vacias de empresas no residentes en españa: cambios en el criterio de la agencia tributaria
Durante los últimos años, la Agencia Tributaria española ha entendido ( sorprendentemente) que una propiedad situada en nuestro país, propiedad de una empresa no residente, generaba un supuesto ingreso por arrendamiento, por la simple disponibilidad del inmueble para las partes vinculadas de la empresa tales como administradores o socios, y consecuentemente, la entidad debía tributar en el Impuesto Sobre la Renta de No Residentes en España.
El criterio de las autoridades fiscales ha sido mantenido durante un largo período, y suponía que las entidades extranjeras tenían que declarar ingresos por arrendamiento cuando las propiedades no eran usadas por nadie, utilizando valores de mercado para dichos ingresos.
Una consulta vinculante reciente de la Dirección General de Tributos ( consulta v2993-21) ha supuesto un cambio masivo en el criterio : las entidades no tendrán que pagar impuestos en España si sus propiedades están vacías y pueden aportar pruebas suficientes de ello.
Este cambio de criterio minimizará significativamente el coste fiscal de tener una propiedad en España, cuyo dueño es una entidad extranjera.
Esperamos que esta información sea útil, y como siempre, permanecemos a su disposición para cualquier aclaración al respecto.
MDG Asesores – Departamento de No Residentes