2020 ENG

EXTRAORDINARY BOJA Nº88 – New measures in Andalucía

We would like to inform you that past 10th December, the Andalusian Regional Government approved new temporary and exceptional measures to contain COVID-19 during the Christmas period. Published in the “BOJA Extraordinario” Nº88 of 11th December 2020. It consists of two periods: from 12 to 17 December and from 18 to 10 January.
Please find attached these new measures for its reading.
The new measures are specified below:
Period 1: From the 12th of December to the 17th of December:
  •  Mobility is permitted between municipalities in the province of Malaga.
  • Shops open until 21.00
  • Hostelry open until 18.00. Take-away food may be collected from the premises until 9.30pm. Home orders until 22.30, delivery until 23.30.
  • Curfew from 22.00 to 07.00.
Period 2: From 18 December to 10 January: 
  • Free mobility throughout the Autonomous Community of Andalusia.
  • Shops, opening and closing in usual hours.
  • Hostelry: split schedule. From the morning until 18.00H // From 20.00H to 22.30H. Take-away food remains the same.
  • Curfew from 23.00 to 06.00
* From 23th December to 06th January: entry into and exit from the Community of Andalusia to other residences for the purpose of family reunification is permitted.
* On 24th, 25th, 31th and 01rd, meetings of 10 people are permitted with a curfew until 01:30. The rest is kept at 6 people.
MDG Team,

Changes introduced in the Royal Decree-Law 34/2020 of 17 November

Find below a summary with the latest news, published in the BOE number 303 of 18th November, Royal Decree-Law 34/2020 of 17th November to support business solvency, the energy sector and tax matters:
1.- Extension of the grace periods and guarantees for ICO loans
 
The expiration deadline of the guarantees regulated under RDL 8/2020 may be extended by a maximum of three years, provided that  the borrowers comply with the requirements set out in the article and  the guaranteed operation does not exceed eight years from the date of initial formalisation of the operation.
The grace period for the repayment of the principal of the guaranteed operation may be increased by a maximum of twelve additional months, provided that it complies with the requirements listed in the article and that the total grace period does not exceed 24 months.
Please find below main requirements indicated in this RDL, in order to be able to apply for an extension of the term or grace period for repayment:
  • Submit the application on time
  • The financing operation is not in arrears
  • The debtor has no outstanding debts in the CIRBE (Central de Información de Riesgos del Banco de España)
  • The financial institution has not notified the guarantor of any default on the guaranteed transaction with the debtor at the date of the extension
  • The debtor is not subject to bankruptcy proceedings and that the debtor complies with the limits established by the European Union’s State aid regulations.
 
2. Modifications to the Law on Capital Companies with regards to the holding of shareholders’ meetings telematically
I. In the case of Public Limited Companies, even if the Articles of Association do not provide for it, the Board of Directors may provide in the notice of the General Meeting for attendance by telematic means and distance voting under the terms provided in Articles 182 and 189 of Royal Legislative Decree 1/2010 of 2 July and Article 521 of the same legal text, in the case of listed public limited companies, as well as the holding of the meeting in any place in Spain.
II. In the case of Limited Liability Companies , even if the articles of association do not regulate  it, the general meeting may be held by videoconference or multiple telephone conference, provided that all persons entitled to attend or those representing them have the necessary means, the secretary of the body recognises their identity, and states this in the minutes, which shall be immediately sent to the email addresses.
III. Exceptionally, during 2021, even if the Articles of Association have not regulated it, the meetings or assemblies of members or partners of the other legal persons under private law (associations, civil societies and cooperative societies) may be held by videoconference or by multiple telephone conference provided that all persons entitled to attend or those representing them have the necessary means, the Secretary of the Body recognises their identity and states so in the minutes, which shall be immediately sent to the e-mail addresses.
IV. Exceptionally, during 2021, even if the articles of association have regulated it, the meetings of the board of trustees of the foundations may be held by videoconference or by multiple telephone conference, provided that all the members of the body have the necessary means, the secretary of the body recognises their identity, and so states in the minutes, which shall be immediately sent to the e-mail addresses of each of the attendees.
3.- Modifications in the VAT of masks and certain medical equipment
 
With effect from 1 November 2020 and in force until 30 April 2021, the rate of 0 percent Value Added Tax shall be applied to the supply of goods, imports and intra-Community acquisitions of goods referred to in the Annex to this Royal Decree-Law whose recipients are public law entities, clinics or hospital centres, or private entities of a social nature referred to in section three of Article 20 of Law 37/1992, of 28 December, on Value Added Tax. These operations will be documented in the invoice as exempt operations.
In addition, the rate of 4% VAT shall be applied to the supply, import and intra-community acquisition of disposable surgical masks referred to in the Agreement of the Interministerial Commission on the Price of Medicines, of 12th November 2020, which revises the maximum amounts of sale to the public, in application of the provisions of Article 94. 3 of the rewritten text of the Law on Guarantees and Rational Use of Medicines and Healthcare Products, approved by Royal Legislative Decree 1/2015, of 24 July, published by Resolution of 13 November 2020, of the General Directorate of the Common Portfolio of Services of the National Health and Pharmacy System.
4.- Modifications to Corporate Tax
  • Deduction for investments in film productions, audiovisual series and live performances of performing and musical arts.
  • Increase in the deduction on Corporation Tax for technological innovation activities in production processes in the automotive industry value chain.
5.- Modifications to the Bankruptcy Law
Until 14th March 2021, the debtor who is in a state of insolvency will not have the duty to request the declaration of bankruptcy, whether or not the competent court has been notified the opening of negotiations with creditors to reach a refinancing agreement, an out-of-court settlement or adhesion to an anticipated proposal for a settlement.
Until 14 March 2021, the judges will not admit for consideration any application for the necessary insolvency proceedings filed after 14 March 2020. If the debtor has submitted an application for voluntary insolvency proceedings up to and including 14 March 2021, the application will be admitted in preference, even if it is submitted after the date of the application for insolvency proceedings.

Support plan for Medium sized companies and Self-employed by “Junta de Andalucía”

Last 16th November, the Andalusian Regional Government (“Junta de Andalucía”) signed an agreement with the Andalusian Confederation of Businessmen, in which it has been created a new Support Plan to self-employed and medium sized companies based in Andalucia, that includes measures and aids totalling 666.6 million euros, which will come in the form of direct aids (223 million), more liquidity (350 million in guarantees) and advantageous tax measures (94 million in indirect aids).
Please find attached the document of the agreement.
This Support plan consists of 10 specific lines, summarised below:
Line 1: Rentals for the self-employed, the hotel industry, small businesses, nightlife and children’s entertainment.
  • 25,2 million euros
  • This aid is in a one-off payment, for the payment of rent to the self-employed, generally in the form of a single payment of 1,200 euros.
  • Aid for activities linked to nightlife and children’s recreation will be a one-off payment of 4,000 euros.
Line 2: Plan for the maintenance of productive activity for self-employed people in the hotel and hospitality, small shops and taxi sectors.
  • 80 million euros
  • This will take the form of a single payment of 1.000 euros to self-employed workers in these sectors.
Line 3: Support plan for medium and small size entities in the hospitality industry and small shops.
  • 44.6 million euros.
  • This aid will consist of a contribution of 1,000 euros to pymes( medium and small size companies) with registered office in Andalusia dedicated to the hostelry and catering trade and retail trade, including itinerant trade or online trade with certain requirements.
Line 4: Liquidity plan for industrial pymes.
  • 50 million euros.
  • This is aimed specifically at companies with less than 250 employees whose turnover has fallen by more than 25% in the first half of the year compared to the same period in 2019.
Line 5: Line of guaranteed loans for SMEs and the self-employed through “Garantia” and “IDEA”.
  • 300 million of guaranteed loans for all types of pymes and self-employed workers.
  • This line will run at least until 31 March 2021 and consists of guarantees for loans of a minimum amount of 12,000 euros and a maximum of 100,000, with a term of 3 to 5 years, grace period of up to 12 months and a fixed interest rate of up to 2%.
  • A 100% guarantee line is also established for self-employed persons for loans of between 9,000 and 15,000 euros.
Line 6: Tax relief plan.
  • 13.8 million euros
  •  This line includes a 50% rebate on the gambling rate for the last quarter of 2020 for establishments with gaming machines.
Line 7: Plan for the digitalisation of economic activity in commerce, hotels and restaurants and tourism for pymes and the self-employed.
  • 19 million euros
  • This line aims to digitally transform the Andalusian business fabric, with a special focus on the sectors most affected by the COVID-19 crisis, over a period of several years.
  • with a budget of 4.8 million euros for 2021.
Line 8: Incentive plan to reduce rents.
  • guarantees in the amount of 80 millions
  • This heading provides for a plan to encourage rent reductions through loans guaranteed by Garantia, which will be linked to negotiations with the lessor for a reduction in rent of between 20% and 50% for at least six months.
Line 9: Plan for aid to basic supplies.
  • This will consist of a social bonus to help self-employed people who have seen their turnover reduced by the pandemic, similar to those who were already in place until 21 July
Line 10: Aid lines for pymes and self-employed people in the cultural and public entertainment sector.
  • 4 Millions euros
  • This line provides subsidies aimed at artistic creation and the acquisition of books, as well as aid in the event of the closure of cultural spaces.
All these measures are still to be published. When that happens, it will be regulated basis, requirements and deadlines. Once it is published, the applications will be channelled through an Integrated Management Office that will be created expressly for this purpose, except for line 8, which will be referred to an office managed jointly by the Andalusian Regional Government and the Andalusian Confederation of Businessmen.
Finally, we would like to inform that the Andalusian Regional Government has specified this morning that it is possible to apply for all these aids simultaneously.
MDG Advisors Team,

MDG informs / new measures for Andalucía BOJA november 8th 2020

We would like to inform you that from 00:00, Tuesday 10th November until 00:00, 24th November, the following measures approved by the Andalusian Regional Government with regards to Covid-19 prevention will come into force. Please find attached the entire new regulation for your verification.

Malaga is at alert level 3 and affected by level 1 measures associated with the establishment of time and travel restrictions between provinces and municipalities. The measures are the same as those published on 29 October 2020, but now they are affected by more severe time limitations.
 
Should Malaga goes forward to Grade 2, we will inform you of any changes on the activities restrictions as soon as possible.  

Please, find below the measures to be applied :

1. Limitation of night-time mobility or curfew from 10pm to 7am:

Exceptions:
a) Purchase of medicines, medical devices and other essential goods.
b) Assistance to health centres, services and establishments.
c) Assistance to veterinary care centres for emergency reasons.
d) Compliance with labour, professional, business, institutional or legal obligations.
e) Return to the place of usual residence after carrying out some of the activities provided for in this section.
f) Assistance and care of the elderly, minors, dependants, disabled persons or particularly vulnerable persons.
g) Refuelling at petrol stations or service stations, when necessary for carrying out the activities foreseen in the previous paragraphs.
h) The matches of officially recognised professional and state sports competitions, and the international matches organised by FIFA, UEFA, FIBA and the Euroleague Basketball League.
i) Activities of fish auctions, first sales dispatch centres, central markets and food and agriculture product supply auctions.
j) Due to force majeure or a situation of necessity.
k) Any other activity of a similar nature, duly accredited

2. Perimeter closure in all the municipalities of Andalusia. Unless there is a justified reason, there may be no movement of people between them, in addition to the corresponding limitation of geographical mobility to other Autonomous Regions:
Exceptions:
 A) Assistance to centres, services and health establishments.
 B) Compliance with labour, professional, business, institutional or legal obligations.
 C) Assistance to university, teaching and educational centres
 D) Return to the place of habitual residence or family.
 E) Assistance and care of the elderly, minors, dependents, disabled persons or particularly vulnerable persons.
 F) Travel to financial and insurance entities or refuelling stations in neighbouring territories.
 G) Required or urgent actions before public, judicial or notarial bodies.
 H) Renewal of permits and official documentation, as well as other administrative procedures that cannot be postponed.
  I) Carrying out official examinations or tests that cannot be postponed.
  J) Travel for the carrying out of collection acts in vegetable gardens by their owners or tenants, care and feeding of domestic animals.
  K) Travel for the purchase of food products by those who have their usual residence in localities which, being within another municipal district, lack establishments allowing the purchase of such products and are adjacent to municipalities with mobility limitations.
  L) Assistance to veterinary care centres for emergency reasons.
  M) Travel of absolute category, high level or high performance sportsmen and women, coaches, judges or federated referees, for sporting activities
  N) Due to force majeure or a situation of necessity.
  Ñ) Any other activity of a similar nature, duly accredited.
3. All non-essential activities must be closed at 6pm, except in Granada, which will be more demanding, where businesses that are not essential activities may not be opened at all:
Essential activities:
a) Industrial activity.
b) Food, drinks, product and basic necessities shops.
c) Health centres, services and establishments.
d) Professional services and domestic employees.
e) Social and health services.
f) Veterinary centres or clinics.
g) Commercial establishments engaged in the sale of fuel for motor vehicles.
h) Vehicle inspection stations.
i) Home delivery services.
j) Canteens and other establishments for the delivery and distribution of food on a charitable basis.
k) Wake services.
l) Sports centres for carrying out physical activity in the open air, provided that these are not contact sports and sports centres for the practice of federated sport in space.
m) Family meeting points.
n) Early Childhood Care Centres and Outpatient Treatment Centres.
o) Non-university teaching activity, school canteens, morning classroom and school transport.
p) University activities.
q) Vocational training centres.
r) Conservatories, language schools, academies, adult continuing education centres and similar.

4. The maximum number of people for any meeting will be 6, both in public and in private areas.
Lastly, attached to this email you can also find the certificate templates to justify the mobility of workers, as well as the certificates to justify travel for work during curfew hours.We remain at your disposal for any questions you may have.

MDG Advisors,

Update: MDG informs/ New curfew certificate

Dear clients,


After publishing the Royal Decree 926/2020 in BOE and the President’s Decree 8/2020 in BOJA, it has been regulated, as you all may know, the curfew between 23.00 hours and 6.00 hours. The Junta de Andalucía has maintained this same timetable, therefore there are no modifications related to the rules published by the Government.


Please find attached the two certificates that allow the movement for workers during the curfew in Andalucía. Please, ask the workers that need it to sign it and carry it with them during the night shift in the curfew, in order to avoid penalties.
Should anyone need this same certificate for workers in other Comunidades Autónomas, please do let us know and we will send the certificate, in accordance to the regulation of each Comunidad Autónoma, as soon as possible.
We remain at your entire disposal for any question you may have.


MDG Advisors,


UPDATE: The Junta de Andalucía, dated 08th November 2020, has modified the curfew timetable as follows: from 22.00 hours to 07.00 hours. Please find attached new curfew certificate for those workers that need it. 

Covid 19 implications on 2020 personal income tax

COVID 19 IMPLICATIONS ON 2020 PERSONAL INCOME TAX

There is no doubt that 2020 Personal Income Tax ( PIT) campaign, that will begin in April 2021, will be an unprecedented one, taking into consideration the numerous legal changes and the exceptional COVID 19 situation .

Thus, it is convenient to comment some implications that the current COVID 19 crisis and the fiscal measures associated to it during 2020, will provoke on the elaboration of 2020 PIT:

  1. Earnings received as a result of an ERTE.

It is commonly known that the negative impact of the pandemic, eased the access to ERTE, and many companies have used such possibility.

From the employee’s point, the perception of the referred benefits is not exempt from taxation on the PIT, and will be considered as a work earnings, having important consequences:

  1. a) Obligation to declare: the employee will have two payers, and consequently, if the Job Office ( SEPE) has paid more than Euros 1,500 to the individual, the limit to declare will decrease from Euros 22,000 to Euros 14,000 per year.
  2. b) It is highly likely that the declaration result will be to pay, since SEPE has been applying the minimum withholdings rates, in most of the cases.

A possible way to avoid this situation could be that the employee asks its company ( if already working ) or SEPE ( if still under unemployment)  for an increase on the withholdings rate.

  1. Sick leaves.

Since the employee has two payers, we could be under the same scenario previously commented (ERTE) ; the limit to declare will be decreased, because after a certain period of time, regardless the sick leave is due to COVID or not, the company will stop paying the salaries, being the payer the Social Security.


  1. Maternity benefits.

Same as in previous tax years, mothers with children under 3 years old, with rights to apply the descendents allowance, could decrease their tax quotas in Euros 100 per month, only if they are working for a company or self-employed, and duly registered before the Social Security.

In accordance with Social Security legislation, in case the ERTE suspends their contracts,the employees will be unemployed to all effects.

Consequently, they will stop from being employees and therefore, they will not fulfill the requirements to perceive the maternity benefits. The only way of keeping the employee status is when the ERTE is partial.

The Tax Office criteria is that mothers in full time ERTE will not be entitled to receive maternity benefits until the ERTE ends, considering they will be unemployed during such time.

  1. Mortgage deferrals.

Those individuals to whom their banks granted deferrals on the payments of their mortgages due to COVID-19, will have a lower expense on their main residence investment.

This will provoke that tax payers who have been applying the deduction of main residence investment in the PIT, will have a lower base to apply it, and taking into consideration that this deduction has maximum limits, they could lose the right to apply the deduction on those amounts in subsequent periods.

  1. Non-Monetary earnings: use of company´s car.

The alarm status and the mobility restrictions, will not affect the consideration of the use of a company car as a non-monetary contribution. The Tax Office understands that such consideration only depends on the mere availability of the vehicle, and not on the actual use of it.

  1. FreeLancer benefits (“prestación por cese de actividad”)

Freelancers that have been perceiving these benefits ( “Prestación por cese de actividad”) will  need to treat them on their PIT as if they were salaries ( work earnings).

There are other implications as a result of the pandemic, hence we are at your disposal for any clarification of doubt you may have.

Brexit: The end of the transitional period

BREXIT: THE END OF THE TRANSITIONAL PERIOD


Next 31st December 2020 the transitional period of Brexit will end. Even though there is a lot of uncertainty regarding the possibility of having a special tax agreement between UK and the EU, at present day, there is none and consequently, UK will be considered as a third country to all effects from 1stJanuary 2021.

Historically, there has always been a very strong trade relationship between UK and Spain, and therefore, it is important for Spanish companies to understand the new tax scenario and prepare for it. Furthermore, especially in Costa del Sol, there is a significant number of property owners with British nationality, who will have different tax treatments in comparison with the current situation.

COMPANIES

The main aspects that all entities should take into consideration are as follows:

  • Border taxes: import of goods from UK will be subject to customs duty. The Spanish Tax Authorities will not let any goods come in our country without paying the import taxes, in case it applies. Likewise, when sending goods to United Kingdom, the British Border Authorities will require their import taxes, in accordance with UK tax legislation.


  • VAT: when exchanging goods with the UK, we will be talking about imports or exports, instead of EU Operations. This implies a big difference: whilst currently no VAT is to be paid when buying/selling from/to UK, from 1st January 2021, the buying company will have to pay the VAT on the border of its country, in accordance with the VAT rates of such country, otherwise the goods will remain in the border.


  • British companies owning a property in Spain will be taxed at 24%, instead of the current 19%. This will increase significantly the tax quotas, not only for the tax rate increase of five points, but also because it will not be accepted to deduct any rental expense.

INDIVIDUALS

It is commonly known that a huge amount of British citizens own properties in Spain, either for personal use or for rental purposes. Brexit will increase their tax bills in Spain as indicated below:

  • Non Resident Taxes: EU citizens pay in Spain annually 19% of a deemed rent (2% of the cadastral value of the property, 1.1% if the cadastral value has been revised during the previous ten years). However, Non EU citizens should pay 24%.


When the property is used for rental purposes, EU citizens pay 19% of the rental profit, but Non EU citizens´ tax rate arises to 24%, with no deduction of expenses, which makes the tax quotas considerably greater for citizens outside the EU.


  • Wealth Tax: Non Residents in Spain with properties located in our country with a total value of Euros 700,000 (or above), are subject to Wealth Tax each year. EU citizens can decide whether they are taxed according to the national legislation or autonomic legislation. However, Non EU Citizens cannot do so. Most of the times, the national Wealth Tax legislation is more tax expensive than the autonomic ones and therefore, the British Wealth tax bills are likely to increase after Brexit.

There are other tax implications which could affect in other cases. Companies that normally operate with UK and British citizens owning properties in Spain should plan for the post-Brexit era, always following the advice of professionals.

At MDG we are at your entire disposal to help you with any doubt you may have.

During the month of November, MDG will participate in the regional awards of AJE.

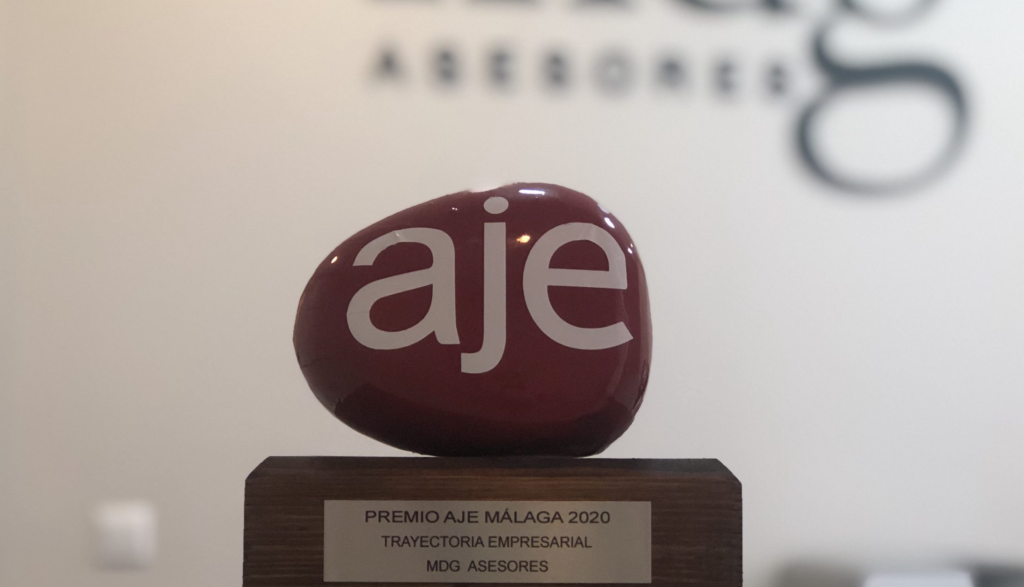
We are pleased to announce that on September 17th MDG Advisors received the Award for Best Business Trajectory 2020 from AJE. Among others, the jury included important personalities from the Malaga Town Hall, Technological Park of Malaga, Bic Euronova, University of Malaga, Junta de Andalucia and AJE Board of Directors.

MDG and the telecommuting challenge

At MDG we have adopted telecommuting as most things are adopted in life, with the urgency of a close deadline and where there was no room for procrastination. We had organised the remote system many months before but had hardly used it unless for the very extraordinary days we could not go to the office for medical reasons.

We started working from home overnight and were lucky to have all systems previously installed. Since the early beginning of our firm we were always concerned about adopting technology to our routines and investments in this field were done every year. It was our target for 2020 to become a digital firm, we could have never imagined a more radical launch.

But it is not just the technological structure that conditions a proper adaptation to telecommuting, it is also essential the cohesion and commitment of the team with the project. Working from home is a litmus test for the communication and productivity skills of any company.

After 4 weeks working from home, the balance so far could not be better, our levels of productivity haven`t been affected and the compromise of all the team, from managers to juniors has been remarkable. If there is something positive we get from the Covid-19 crisis, it is the record adaptation of our firm and the opportunity to confirm the level of engagement and commitment of the MDG team.

Publishment of the “real decreto” 9/2020 and 10/2020

From MDG, we would like to inform you about the principal measures taken in this regulation. However, we would like to inform you also that as from tomorrow, there will be more measures published and the ones we already have will be clarified. We are living a confusing time and little rigour in the regulation recently published, due to this unusual COVID-19 crisis, hence we recommend patient and caution.

These measures are the following ones:

1. Suspension of all economic activity NOT indispensable. You can access the list of these essential activities, at the following link: https://www.boe.es/buscar/doc.php?id=BOE-A-2020-4166

2. The new recoverable paid leave is adopted between March 30 and April 9. For those workers of the companies that have to suspend their activity because it is not essential, this permission is provided. Their salaries will continue to be paid , but the hours corresponding to that salary must be recovered after the State of Alarm is overcome. This is mandatory, even if it is called “permission”, and the hours will be gradually recovered. It does NOT apply to companies that can work remotely.

3. Dismissal for objective reasons is limited, in other words, force majeure and economic, technical, organizational causes … for the termination of contracts will not be considered as objective cause, therefore the dismissal will not be fair. The Government pretends to limit the extinctions of contracts, and to facilitate the suspensions of contracts.

4. Interruption of the calculation of duration in the suspension of temporary contracts. If the suspension of temporary employment contracts has been agreed, its computation will restart after the conclusion of the Alarm State.

5. Facilitation of the unemployment benefits for workers affected by ERTES. The application for unemployment benefits will be made collectively by the employer, and not by each worker individually.

6. The ERTES requested on the occasion of COVID-19, both those based on force majeure and objective causes, will only last as long as the Alarm State is maintained.

7. Warning to companies that, if they act in fraud of law or with falsification of data, both in ERTES and in the reception of any benefit, will be sanctioned accordingly, as well as the Government remark that necessary measures will be taken to review and control that such actions do not occur.