2023 ENG

Optimising the financial structure of a company: Tax advantages of increasing shareholders’ salaries or distributing dividends and how they compare in terms of personal income tax and corporate income tax.

In the business world, strategic financial decision-making plays a crucial role in the success and sustainability of a company and must also be in line with the requirements of tax compliance and corporate compliance. Among the options available to managers for the improvement of remuneration by the company are an increase in their own salary, provided that this is not linked to remuneration for their directorship, or the distribution of dividends. Beyond the economic and employment implications, it is essential to analyse the tax advantages associated with each of these decisions.


Increased salaries for partners: Tax implications and advantages.

Increasing salaries for a firm’s partners can offer several tax advantages that contribute to sustainable growth and financial strength.

Firstly, the salary, for corporate tax purposes, is considered a deductible expense, which reduces the company’s taxable base, and always bearing in mind whether the salary is received for work performed by the partner himself or for remuneration as a director, in which case, there would be some specifications to take into account. In either case, this tax deduction can be significant, as it decreases the entity’s overall tax burden.

In addition, higher salaries may generate additional benefits by increasing contributions to social security and retirement plans.


Dividend payouts: Optimising accountability to shareholders.

In contrast to salary increases, dividend distributions also have key tax advantages that can influence a company’s financial decisions; however, it should be noted that there are a number of corporate requirements to be complied with, such as those set out in Articles 274 and 275 of the Spanish Companies Act (Ley de Sociedades de Capital):

  • After the distribution of dividends, there must not be an equity imbalance, i.e. the net assets of the company must not be less than the share capital.
  • In the event of losses from previous years, the profit must be used to cover such losses.
  • 10% of the profit must be allocated to the legal reserve.

On the other hand, the dividend distribution policy can also be beneficial in terms of tax flexibility. By allocating dividends, the company can adapt its profit distribution structure according to its objectives and market conditions. This allows for more agile and efficient management of financial resources, especially in volatile economic environments.


Strategic considerations for sound decision making: Tax efficiency in the area of personal income tax and corporate income tax.

The choice between increasing salaries or distributing dividends should not be based solely on tax advantages. Factors such as the company’s financial situation, long-term goals, talent retention and shareholder perception should be carefully considered.

As far as personal income tax (IRPF) taxation is concerned, it should be borne in mind that salary will be taxed as employment income in the general tax base at a maximum rate of 47%. On the other hand, dividends will be taxed as income from movable capital in the savings base at a rate of 19/28%.

Likewise, and as already indicated, as far as corporate income tax is concerned, the salary, and provided it is not remuneration for the position held as a director for which certain requirements must be met, will be deductible in corporate income tax, whereas dividends will not produce a saving in corporate income tax.


In conclusion, both salary increases and dividend distributions offer valuable tax advantages for companies and their shareholders. It is crucial to conduct a cost-benefit analysis that includes not only the short-term tax implications, but also the long-term impact. In many cases, a balanced combination of both strategies may be the most prudent option.


Jesús Raya Zamora.
New regulation approved: computerised invoicing requirements

Recently, on 6 December, Royal Decree 1007/2023 of 5 December was published in the Official State Gazette (BOE), approving the Regulation that establishes the requirements to be adopted by the computer or electronic systems and programmes that support the invoicing processes of entrepreneurs and professionals, and the standardisation of invoicing record formats.

This new regulation came into force on 7 December, and taxpayers must have the computer systems adapted to the characteristics and requirements in place by 1 July 2025, so the following is a summary of the main points to bear in mind before the end of this period:

  1. To whom does this new regulation apply?

– Corporate taxpayers.

– Taxpayers of personal income tax who carry out economic activities.

– Non-resident income taxpayers who obtain income through a permanent establishment.

– Entities under the system of attribution of income that carry out economic activities, without prejudice to the attribution of income that corresponds to their members.

It shall also apply to the producers and marketers of computerised invoicing systems, in matters relating to their respective activities of production and marketing of the computerised systems made available to taxpayers.

Exception: It will not apply to taxpayers who keep their books of records through the AEAT’s Electronic Headquarters by means of the electronic supply of invoicing records (SII).


Nor will it apply to certain operations such as the following:

– Those under the special VAT regime for agriculture, livestock and fishing.

– Those carried out by entrepreneurs or professionals in the course of their activities to which the special equivalence surcharge regime applies or those under the simplified VAT regime.

– Those related to certain deliveries of electrical energy or those invoiced by the National Energy Commission.

– Those documented in invoices for transactions carried out through permanent establishments abroad.


  1. What is the main change in the Billing Regulation?

The purpose of this new regulation is really to regulate the requirements and technical specifications that the computer systems used by those who carry out economic activities must comply with when carrying out invoicing processes. In other words, the computerised invoicing systems used by taxpayers must comply with a new series of requirements in order to be considered valid and to correctly transmit the information contained in them. Above all, the regulation establishes that the computer systems must guarantee the integrity, conservation, accessibility, legibility, traceability and unalterability of the invoicing records.

Furthermore, the computer system must be capable of sending the tax administration, by electronic means, all the invoicing records generated, continuously, securely, correctly, fully, automatically, consecutively, instantaneously and reliably, and must have an event log that automatically records, at the time they occur, certain interactions with the computer system, operations carried out with it or events occurring during its use, storing the data corresponding to each of them, which must be able to be consulted from the computer system itself.

In the computer systems, access to information with tax implications shall be duly dissociated from access to possible confidential information of a non-property nature, so that the tax administration may have direct access to the consultation and the rest of the functionalities required for the information in the invoicing and event records.

  1. What computer system can be used with this new regulation?

Taxpayers may comply with the new obligations using the following options:

– An own computer system, which must have a responsible declaration certifying that said computer system complies with the regulation, among other requirements.

– The computer application that the Tax Administration may develop for this purpose.


You can find more information at the following link:        https://www.boe.es/boe/dias/2023/12/06/pdfs/BOE-A-2023-24840.pdf

If you have any doubts about these new invoicing obligations, please do not hesitate to contact MDG Advisors.


Marina Guerrero Castronuño

The Tax on Economic Activities and its census obligation in the month of December

Most of us tax advisors are working on the annual accounting and tax pre-closing of companies in order to be able to offer our clients the best tax advantage to reduce their tax burden for the financial year 2023.

However, in view of this workload, we cannot forget that during the month of December there is a new census obligation to comply with and to communicate any variation in the Tax on Economic Activities. This notification must be made to the Tax Agency (Form 840) or to the City Council (Form 010) where the company has its tax domicile, depending on the powers of each Administration.

Before going into the tax obligations to be filed with the Census, we would like you to familiarise yourselves with the tax to be dealt with:

The Tax on Economic Activities (hereinafter, IAE), which is regulated in articles 78 to 91 of Royal Legislative Decree 2/2004, of 5 March, which approves the revised text of the Law Regulating Local Treasuries, is a tax levied on the exercise of business, professional or artistic activities in Spanish territory.

It is a local tax that is applied at municipal level and is managed by the local councils. It is worth mentioning that not all activities are subject to IAE, and there are exemptions and bonuses applicable in many cases.

Some key points to highlight about the IAE:

– Scope of application: individuals or legal entities and the entities referred to in Article 35.4 of Law 58/2003, of 17 December, General Tax Law, which carry out business, professional or artistic activities in Spanish territory, are taxable persons subject to this tax.

However, it should be borne in mind that individuals, whether or not they are resident in Spanish territory, are exempt from the tax.

– Rates: IAE rates vary according to the nature of the activity and the net turnover. There are specific headings that classify activities, and each one has an assigned rate.


– Exemptions and allowances: There are activities that are exempt from IAE, and in some cases, local councils can establish reductions in the tax rates.

With regard to exemptions, the following two are worth mentioning:

  1. Taxpayers who start their activity in Spanish territory are exempt during the first two tax periods of this tax in which they carry out their activity.
  2. Corporate taxpayers, civil companies and the entities of article 35.4 of Law 58/2003, of 17 December, General Tax Law, are exempt provided that they have a net turnover of less than 1,000,000 Euros.


– Municipal management: Although it is a national tax, it is managed by the local councils. Each municipality establishes the specific rates and conditions, within the limits set by national legislation.


– Self-assessment: This is where the census obligation that we mentioned at the beginning of the article falls.

IAE taxpayers must submit a census declaration during the month of December (form 840 or form 010, depending on the jurisdiction of each territory) in which they notify the competent body of any event that entails, with effect for the financial year 2024, the cancellation or registration in said tax.

The following is a brief example that summarises the procedure to be carried out:

A company that is not newly created, and during the financial year 2021 had a net turnover of 750,000 Euros and during the financial year 2022 this figure increased to 1,250,000 Euros, is obliged to notify, by means of Form 840 or 010, that it no longer enjoys the exemption established in article 82.1.c) of the Royal Decree mentioned at the beginning of the article, with effect for the financial year 2024. This census notification must be made in December2023.

The range of possibilities for this tax is very wide depending on the type of each client and the activity to be carried out, so if you would like further information on this article, we remain at your disposal to clarify any doubts you may have in this respect.


Leticia Cayuela.

The revocation of a company’s CIF: tax and commercial implications.

Although at first sight it may seem to be an abstract action that rarely happens, it is more common than we think that the Spanish Tax Agency may revoke the NIF or Tax Identification Number of a company and it can happen for several reasons.

Some of the most common reasons may be that a provisional tax identification number has been assigned to an entity, but the necessary documentation to obtain a definitive tax identification number is not provided within the established period, or that the entity has tax debts with the Spanish Tax Agency. Also included in the grounds for revocation are the failure to file tax obligations such as the corporate income tax for three consecutive periods or the annual accounts for four consecutive periods, all these non-compliance actions could lead to the revocation of a company’s tax identification number.

It is true that, the most frequent is the revocation of NIF to those companies that are inactive and sometimes even those that have a reduced turnover. This activity of the Tax Agency entails that the administrators of these companies are unable to carry out operations with the Public Administrations and that the registration page of the Mercantile Registry is closed.

In addition to the aforementioned consequences, the entity will not be able to make debits and credits to the accounts opened in credit institutions and will not be able to obtain tax certificates.


What should I do if this happens?

It is important to bear in mind that the agreement to revoke the NIF will require the prior hearing of the taxpayer for a period of 10 days, counted from the day following the notification of the opening of said period. The revocation will be published in the Official State Gazette and the taxpayer will be notified, following a publication schedule on Mondays, Wednesdays and Fridays of each week.

On the Tax Agency’s web page, in the Electronic Headquarters, it is possible to consult whether a specific NIF is revoked or not, as well as the date of publication in the BOE of this revocation.

Fortunately, the revocation of the NIF does not have to be irreversible and the Tax Agency can reactivate it as long as the circumstances that motivated them to take this action have ceased. To do so, they must expressly prove that the causes that motivated the revocation have ceased and provide the required documentation.

Mainly, when a NIF has been revoked and the entity needs its activation it can be for two basic points: either for the entity to be liquidated or for the entity to continue with its activity. In both cases, there is a common documentation and other complementary documentation depending on the purpose.

Whichever option it is, it is obligatory to provide proof of filing of the Corporate Taxes, of course, of the fiscal years not prescribed at the date of notification, as well as the accreditation of not having outstanding debts with the Spanish Tax Agency, since the NIF is inactive and it is not possible to obtain the tax certificates, it must be studied if the entity is registered as a Failed Debtor in the Collection unit.

However, this documentation in itself is not enough to reactivate the NIF, but it will have to be accompanied by complementary and different documentation, if the purpose of the reactivation is to liquidate the company or to continue with our activity.

Consequently, from all the above mentioned, the revocation of a NIF should be understood more than as a sanction as an administrative act of control in which legal entities that do not comply with their tax obligations or that have moved away from their activity.

For further information, please do not hesitate to contact our MDG Team.


Carmen Moya López.

Measures To Avoid International Double Taxation

On numerous occasions, individuals and entities may be exposed to being taxed on the same income, profit, or asset in more than one country due to discrepancies in tax regulations between jurisdictions. This tax issue can generate a duplicate tax burden, negatively impacting those individuals and legal entities that carry out their operations internationally.

For this, it is essential to put in place measures to prevent international double taxation in the tax area, ensuring fairness and efficiency in the taxation of income that could be taxed in more than one country. These measures are mainly divided into unilateral and bilateral measures.


UNILATERAL MEASURES:

Unilateral measures refer to decisions taken individually by individual states within the scope of their domestic legislation. In the context of Spanish legislation, this includes the provision on the deduction for international double taxation, applicable to both natural and legal persons, and regulated in the Personal Income Tax (IRPF) and Corporate Income Tax (IS) regulations, respectively.


BILATERAL MEASURES:

Bilateral measures arise from the collaboration between two States that sign a Double Taxation Avoidance Convention (DTA). These agreements seek to clarify and unify the tax situation of individuals and entities involved in international activities. The Double Taxation Conventions, of which Spain has signed several with different countries, seek to address and resolve these issues. The provisions established in these treaties and conventions take precedence over domestic tax regulations, being automatically and compulsorily applicable, with no possibility of waiver.

The provisions established in these treaties and conventions take precedence over domestic tax regulations, being automatically and compulsorily applicable, with no possibility of waiver. The Double Taxation Conventions, of which Spain has signed several with different countries, seek to address and resolve these issues. Therefore, the first step in determining the tax treatment of income obtained in Spain by a non-resident is to identify the country of tax residence and verify the existence and content of the Double Taxation Agreement with that country, in order to define the tax treatment corresponding to that income.


In conclusion, international double taxation involves complex challenges for individuals and entities with international operations. Both unilateral and bilateral measures are essential pillars to ensure fairness and efficiency in cross-border taxation, preventing duplication of tax burdens and establishing a robust framework to address tax complexity in an international environment.

Sandra Gámez Chaves

The limited verification procedure of the Tax Agency and its importance in tax management.

The Tax Agency, in its tax collection work, has various tax procedures to verify and audit the economic activity of taxpayers within the tax administration itself, where it finds its regulatory motivation in articles 117 and 123, among others, of the General Tax Law (hereinafter, LGT).


One of these procedures is the limited verification procedure, a tool that allows the tax administration to review certain aspects of the tax return without carrying out a full audit. In this article, we will explore what the limited verification procedure consists of, how it works and its importance in the field of taxation and tax compliance.


What is the limited audit procedure?


The limited verification is an audit procedure that the Tax Agency regulates in article 136 et seq. of the LGT. This procedure is carried out to verify the correctness of certain aspects of a taxpayer’s tax return without the need to review the taxpayer’s entire tax situation. Unlike a full inspection, which involves an exhaustive analysis of all tax aspects of a person or company, the limited verification focuses on specific and concrete issues.


This procedure is used when the tax administration detects indications of tax irregularities or non-compliance in one or more items of the tax return. Instead of initiating a full inspection, which can be costly and time-consuming, the limited audit focuses on resolving the identified doubts or irregularities.


How does the limited audit procedure work?


The limited audit procedure starts with a notice to the taxpayer informing him that a review of certain aspects of his tax return will be carried out. This notice usually details the items or concepts that will be subject to review. For his part, the taxpayer must cooperate with the Tax Administration by providing the information and documentation requested within the deadline established for this purpose.


During the limited verification process, the Tax Agency reviews the documentation provided by the taxpayer and carries out the necessary checks to verify the correctness of the items being investigated. This process may include the review of invoices, contracts, financial statements and any other relevant documents that provide reliable information about the liquidation of a certain tax.


Once the review is completed, the Tax Agency issues a report with the results of the limited audit. If tax irregularities or non-compliance have been identified, the taxpayer will be notified and given the opportunity to make representations and correct the discrepancies.


Importance of the Limited Audit.


The limited audit plays a fundamental role in the tax system, as it allows the Tax Agency to verify the correctness of tax returns without having to carry out full inspections on all taxpayers. This streamlines the audit process and allows the tax administration to focus on the cases with the highest risk of non-compliance.


In addition, the limited audit promotes transparency and voluntary compliance with tax obligations. Taxpayers who know that the tax administration can review certain aspects of their tax returns are more likely to file accurate returns and comply with their tax obligations.


On the other hand, the limited audit also protects taxpayers’ rights, as it avoids intrusive and costly inspections when they are not necessary to the specific case. This helps to maintain a balance between tax control and the protection of taxpayers’ privacy and rights.


In conclusion, the limited verification procedure of the Tax Agency is an essential tool to verify the correctness of taxpayers’ tax returns. It allows a targeted review of specific aspects, streamlining the audit process and encouraging voluntary compliance with tax compliance. At the same time, it protects taxpayers’ rights by avoiding costly and/or unnecessary inspections. In short, the limited audit is an effective mechanism to guarantee the integrity of the tax system.


Jesús Raya.

Impatriate regime: The so-called Bekcham Law also has census obligations in November

Our firm advises taxpayers covered by the Special Regime for Workers Posted to Spanish Territory to review their tax situation for the 2024 tax year in November, as some of them may have to comply with certain census obligations.

This special regime, also known as the Beckham Law, allows individuals who have acquired their tax residence in Spain as a result of moving to Spanish territory for work purposes to pay Non-Resident Income Tax.

Following the publication of Law 28/2022, of 21 December, on the promotion of the start-up ecosystem, this regime has undergone changes, which came into force on 1 January 2023:

  • Previously, it was required not to have been resident in Spain in the ten tax periods prior to the move to Spanish territory, reducing this figure to just five years.
  • The move had to take place as a result of an employment contract or appointment as a director in a non-related entity. Currently, the fact of being a related entity does not exclude the regime, as long as it is not an asset-holding company, and it is allowed to apply for new employment reasons, such as the performance of an entrepreneurial activity or an activity performed by a highly qualified professional providing services to emerging companies. There is also the option of applying as a spouse or child under the age of 25 or a child with a disability of a taxpayer covered by this scheme.


It lasts for 5 years, in addition to the year in which tax residence in Spain is acquired. However, there is the possibility of renouncing in the event that the taxpayer’s situation undergoes changes that result in less advantageous taxation. This renunciation should be made expressly in November and December, prior to the beginning of the calendar year, and with effect from the beginning of the calendar year. In the event that the taxpayer no longer complies with the requirements under which he/she joined the scheme, he/she must opt out of the scheme within one month of the non-compliance. Unfortunately, in both situations the taxpayer loses the possibility to opt back into the scheme in the future.

If you need help to opt out of this special regime, or to complete the census obligation to opt out this November, we are at your disposal.

Isabel María Díaz Rubio.

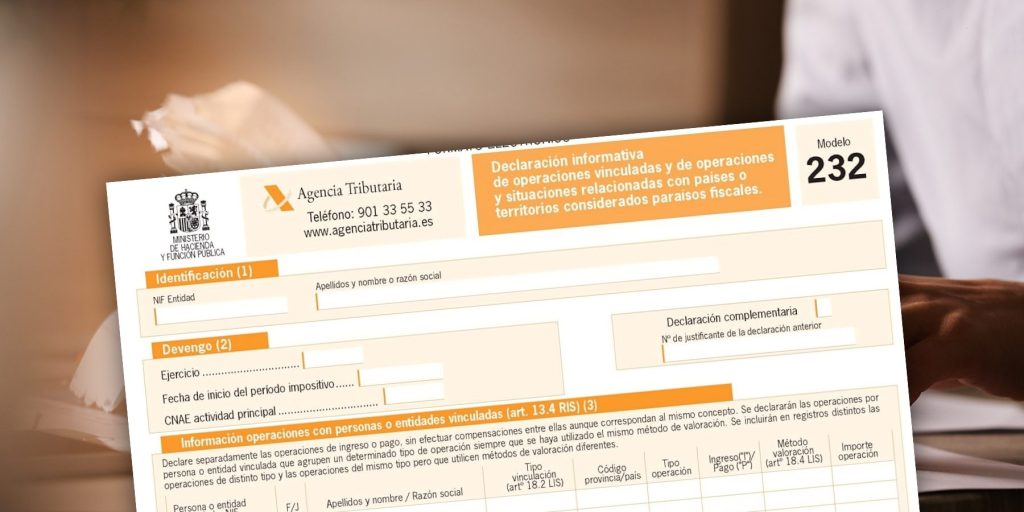
Form 232 and its implications for reporting related parties

Form 232 is an information return in which the Tax Agency is informed of related-party transactions and transactions and situations related to countries or territories classified as tax havens.

Related-party transactions are regulated in Article 18 of the Corporate Income Tax Act.

The deadline for filing this form is within the month following the ten months after the end of the tax period. Therefore, if a company ends its tax year on 31 December, the deadline for filing is November.

There is an obligation to file this return when transactions are carried out with related persons or entities, according to the following assumptions:

  • – Transactions carried out with the same person or related entity for an amount greater than 250,000 euros.
  • – Specific transactions carried out, provided that the total amount of each of these types of transaction in the tax period exceeds 100,000 euros. Specific transactions are regulated in article 18.3 of the Corporate Income Tax Act.
  • – Transactions of the same type which in turn use the same valuation method carried out with a related person or entity accounting for more than 50% of the net turnover of a company.
  • – Transactions with countries considered tax havens.
  • – When the reduction in the tax base provided for in Article 23 of the Corporate Income Tax Act is applied for the assignment of certain intangible assets to related persons or entities.

In short, this is yet another tax obligation that companies must comply with if they are obliged to do so, so please do not hesitate to contact our team to resolve any queries you may have.

Sara Gámez Córdoba

Vat monthly refund register (redeme): advantages and disadvantages for companies

During the month of November, companies based in Spain have the possibility of voluntarily applying for inclusion in the monthly VAT refund register (REDEME). This register has an interesting financial attraction for those companies that need to improve their cash-flow in terms of VAT refunds as, through monthly returns, they will be able to apply for such a refund, which is normally quicker than the general annual refund that takes place in January for companies filing quarterly returns.

Being on the monthly refund register implies greater obligations, such as settling VAT on a monthly basis (form 303) and the obligation to keep the VAT register books through the AEAT’s Electronic Headquarters with the well-known SII (Immediate Supply of Information), increasing the administrative cost for the company.

However, the advantages provided by this system in conjunction with the SII are greater:

– Obligations are reduced, as there will be no need to file Forms 347, 340 and 390.

– The information provided by each company can be easily compared with that of other companies using the SII.

– Errors are reduced and management is simpler. Minimising errors can also avoid penalties and surcharges from the tax authorities.

– The deadline for filing monthly self-assessments is extended by 10 days.

– The time taken by the tax authorities to issue refunds is reduced because the checks are carried out more quickly.

– The information requests made by the tax authorities are reduced, as the information is already in their possession and they do not have to ask companies for it.

Weighing up the advantages and disadvantages and depending on the organisational and financial structure of the company, it may be interesting to opt for this system in November for the 2024 financial year. If you have any doubts about REDEME or SII, please do not hesitate to contact MDG Advisors.

Marina Guerrero Castronuño.

The Importance of anticipating the accounting and fiscal year end.

In the tax advisory world, November has historically been a month of “little” workload or during which we take the opportunity to dust off certain files and close them. This is mainly due to the fact that, in this month, there are no excessive filing deadlines, which gives us a certain margin for “creativity”.

Since the creation of our firm, we have always performed accounting and tax pre-closings in November for several reasons:

  • It is necessary to anticipate possible high results in the Corporate Tax, avoiding cashflow issues.
  • As a general rule, companies close their fiscal year on December 31st , so that a closing in November and a meeting with the client is a highly valued action, since it gives the possibility of adopting measures before the closing that help to reduce the tax burden: bonus distribution, investments, etc.
  • Proactive advice: this concept is always an added value. With the era of digitalization, our role has been shedding the label of accountants to give more room to that of advisors. Therefore, our job is to advise the client and this is not achieved without proactivity. In our experience, clients place considerable value on receiving news about the performance of their companies before it is too late.


For these reasons it is necessary and advisable to anticipate the year-end closings to the month of November, giving flexibility to all our clients.

We hope you find this information useful. Should you have any queries, please get in touch with us.

Pablo Mallo.