2023 ENG

Is there discrimination against foreign investment in Spain? New tax paradigm of Law 38/2022

Law 38/2022, of December 27, 2002, brought important regulatory changes affecting the taxation of non-resident companies in Spain.


The first aspect to highlight would be the implementation, already for the financial year 2022, of the Temporary Solidarity Tax on Large Estates, hereinafter referred to as ITSGF.


This new tax, with which we should familiarise ourselves, is a direct, personal and complementary tax to the Wealth Tax, which is levied on the net wealth of individuals with a value of more than Euros 3,000,000.


So far, both resident and non-resident taxpayers in Spain will have a new tax obligation with the Spanish tax authorities in July.
But what happens with the Euros 700,000 exemption established in this tax? Well, this is where the possible “discrimination against non-residents in Spain” who have invested or intend to invest in our country comes into play, as the tax base will only be reduced by Euros 700,000 in the case of personal obligation. In other words, this reduction of Euros 700,000 CANNOT be applied to non-resident taxpayers in Spain, which could be a discrimination contrary to Community provisions.


However, what happens with the taxation limit for this tax? The full amount of this tax, together with the amounts of Personal Income Tax and Wealth Tax, may not exceed, for taxpayers subject to the tax by personal liability, 60% of the sum of the taxable bases of the former. Again, another limit, but only for the personal liability: what happens to those who are taxed under the real liability (non-residents in Spain)?


And, finally, we will deal with the criterion of personal and real obligation, a subject that serves as a prelude to comment on another regulatory change brought about by Law 38/20222, of 27 December. In the third final provision of the aforementioned Law, the Wealth Tax is modified, also for the financial year 2022.


With this amendment, who are the taxable persons for wealth tax from 2022 onwards, and therefore for the ITSGF?


  • By personal obligation, individuals who have their habitual residence in Spanish territory, with the tax being levied on the totality of their net wealth regardless of where the assets are located or where the rights can be exercised.
  • By real obligation, any other natural person for the assets and rights they own when these are located, may be exercised, or must be fulfilled in Spanish territory.
     MODIFICATION: For these purposes, securities representing equity interests in any type of entity, not traded on organised markets, at least 50% of the assets of which are directly or indirectly made up of real estate located in Spanish territory, shall be deemed to be located in Spanish territory.


In the recent resolution of the DGT consultation V0107-23, dated 1 February 2023, it was established that, with the new regulatory change, a non-resident in Germany, partner of a German company, holding a real estate property in Ibiza valued at 7,500,000 Euros, whose value means that at least 50% of the company’s assets are made up of real estate located in Spanish territory, will be taxed in Spain for all of the company’s assets, AND NOT only for the real estate in Spain.


This conceptual modification to the real tax obligation leads us to consider this “new concept” of real obligation as a hybrid between being a taxpayer by personal and real obligation, since, if the non-resident company has assets, at least 50% of which are made up, directly or indirectly, of real estate located in Spanish territory, it will have to pay tax in Spain on all the company’s assets, even if it is a non-resident company.


Due to the importance of foreign capital in our country, both the ITSGF and the new modification of the Wealth Tax have already been denounced before the European Commission. There is nothing left to do but wait for the resolution of this complaint, and in the meantime, we will be happy to analyse each specific case of our clients.
Collaboration agreement with SIMED

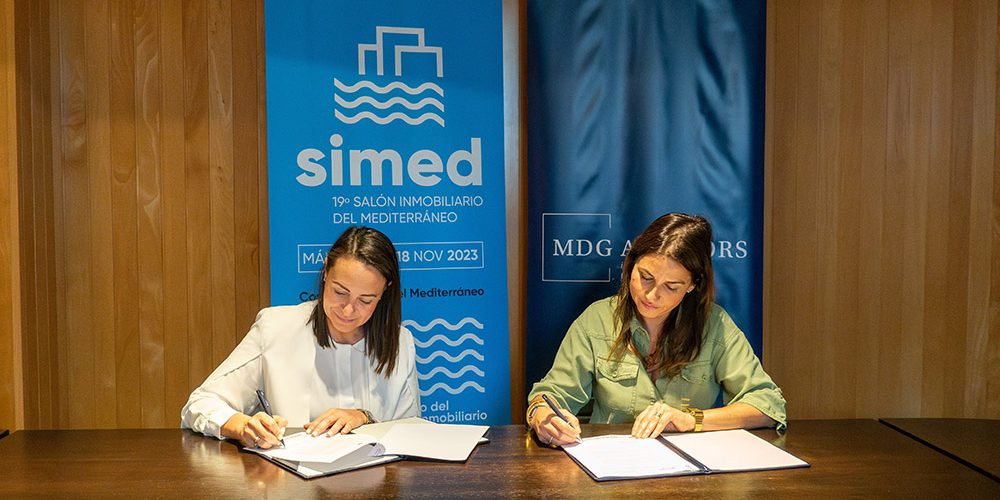
MDG Advisors is pleased to announce its collaboration agreement with SIMED, the Mediterranean Real Estate Exhibition, which will take place from November 16 to 18, 2023 at FYCMA, Malaga Trade Fair and Congress Center. SIMED is recognized as a key meeting point for professionals, companies and potential buyers and sellers in the real estate sector. We are excited to be able to contribute our experience and knowledge to this event and establish new business relationships.

Towards the digitisation of notarial services.

Last Tuesday, 9 May, the new Law 11/2023, of 8 May, was published in the Official State Gazette (BOE), which includes important new features in the way of relating with notaries and carrying out procedures before these professionals.

With the effects of the aforementioned Law and expected by the end of the year, the digitalisation of notarial procedures will take place, allowing this type of service to be provided online, without the need for the interested party to go to the notary in person. The procedure could be carried out by videoconference and the signing of the document would be carried out by specialised platforms that guarantee the authenticity of the signature, safeguarding the security of the information with important measures.

It should be borne in mind that this law is the transposition of a European directive, so that these new developments in the digitalisation of procedures before the notary would represent a further step in the bureaucratic integrity of the European Union, with a citizen of one Member State being able to carry out a procedure (incorporation of a company, legitimisation of a signature, power of attorney, cancellation of guarantees, etc.) in another Member State without the need to travel.

In conclusion, the digitalisation of this type of actions, and bearing in mind the recommendations established by the Directive itself on money laundering and the fight against tax evasion, will be an important technological advance that will allow greater freedom to be given to the market itself by eliminating bureaucratic barriers and travel at the time of carrying them out, as well as a reduction in the environmental impact.

We will have to keep an eye on future news on this issue to know exactly when these technological developments will take place.

MDG Asesores joins the fiscal debate at the XVI National Study Day AEDAF

MDG Asesores, represented by partner Leticia Cayuela, member of the national group of young experts, participated in the XVI National Study Day AEDAF, an essential event for all tax and fiscal professionals.

The conference covered topics of great relevance in the current panorama, such as the information obligations of intermediaries derived from DAC6, the new European directive on corporate sustainability information, the response to information requirements in verification procedures and its fit in the situation of verified versus investigated and the right to remain silent in the inspection procedure, the implementation of the Temporary Solidarity Tax on Great Fortunes and the novelties introduced by the Law on the Promotion of the Emerging Business Ecosystem and the Law on the Creation and Growth of Companies, covering mercantile and tax aspects.

Undoubtedly, this conference was a unique opportunity to update knowledge and stay up-to-date with the latest legislative and fiscal developments, as well as to exchange ideas and opinions with other experts in the sector.

MDG Asesores’ presence at this event is a testament to the firm’s commitment to providing its clients with a high-quality service based on a deep knowledge of legislation and constant updating of regulatory changes.

In conclusion, the XVI National Study Day AEDAF was a resounding success and MDG Asesores, through the participation of Leticia Cayuela, once again demonstrated its leadership in the tax and fiscal sector.

Should an English Company buy a Spanish Property?

I have an English limited company with money in it. Can the company buy a Spanish property ? I would like to rent the property for holiday lets and also use it. I am looking at the canaries and main land Spain.

The simple answer to this question is yes. An English company can buy a Spanish property.

The more complicated question which we will consider is whether 1) you should buy the Spanish property in the name of the English company or 2) incorporate a Spanish limited company and the English limited company becomes a shareholder in the local Spanish company or 3) incorporate a Spanish company and the English company loans monies to the Spanish company to buy a property.

Here to help us with this analysis is Miriem a Spanish accountant and owner of MDG Advisers which is a b 2 b firm of accountants.

Information Note 27/2022

On 24 December 2022, Law 31/2022 on the General State Budget was published in the Official State Gazette (BOE), which includes tax modifications, such as:

A) Personal Income Tax:

– With regard to reductions, the amount for obtaining earned income is increased for certain income thresholds. Also, economically dependent self-employed workers are increased in 2 income brackets and there is a 10% reduction in the income from activities in objective estimation.
– Taxpayers who receive only earned income from more than one payer are not obliged to submit a self-assessment if the sum does not exceed €15,000 are not required to do so.
– The deduction percentage for expenses that are difficult to justify is increased to 7%, without modifying the limit of €2,000.
– The absolute limit for contributions to pension plans, €1,500, is increased by €8,500, provided that the increase is from employer contributions or employee contributions.
– The scale of savings includes two brackets: 200.000€-300.000€ at a rate of 27% and from 300.000€ 28%.
– The scope of the deduction is extended to €1,200 per working mother with two children under the age of 3 if, at the time of the child’s birth, they are receiving contributory or welfare benefits from the unemployment protection system.
– The imputation of real estate income will be 1.1% for properties located in municipalities where the cadastral values have been revised, modified or determined in accordance with the regulations.

B) Corporate income tax

– The rate is reduced to 23% for entities whose net turnover in the previous tax period is less than €1,000,000 and which are not considered as a group.
– For the years 2023, 2024 and 2025, accelerated depreciation is allowed, by multiplying the maximum coefficients by 2, for investments in new vehicles for the purpose of economic activities and which enter into operation in those years.

C) Value Added Tax

– -An exemption regime, similar to that of the armed forces, is established for operations with any State party to the North Atlantic Treaty.
– Exceptions to the reverse charge are included when transactions are carried out by persons or entities not established in the territory where the tax is levied.
– Provisions are included to better define the rules concerning the place of intra-Community sales of goods. Also, for the application of the threshold, the supplier must be established in only one Member State and the goods must be dispatched from that Member State.
– Modification of the basis for uncollectible receivables, e.g. the time limit to proceed with the recovery of VAT from the moment it is declared uncollectible is extended to 6 months.
– Tampons, pads, panty liners, condoms and other non-medicated contraceptives are taxed at the reduced rate of 4%.

D) Special Regime for Worker Cooperatives

– The number of salaried workers with an open-ended contract may not exceed 20% of the total number of members, if the number of members is less than 5, one salaried worker may be hired. However, if the number of partners is between 6-10, 2 may be hired.
– The cooperative may employ employees through any other form of contract, provided that the number of working days worked during the year does not exceed 25% of the total number of legal working days worked by members.

E) General Tax Law: rules are issued for the deferral and instalment payment of tax debts and penalties in pre-insolvency situations with 6, 12, 24, 36 months with different requirements in the instalments.

F) In other regulations: the legal interest rate is set at 3.25% and the default interest rate at 4.0625%.

The new Excise Tax on Plastic Packaging

From 1st January 2023 in Spain there will be a special tax on non-reusable plastic packaging, whether it is presented empty or whether it is presented as containing, protecting, handling, distributing and presenting goods.

Non-reusable packaging containing plastic is included to the extent that it is designed to contain, protect, handle, distribute and present goods,

Packaging is not considered to be that which is necessary to contain, support or preserve it throughout its life cycle and is intended to be used, consumed or disposed of with it.

The applicable tax rate will be 0.45 euros per kilogram of non-recycled plastic contained in the products subject to the tax.

The accrual differs according to the following:

  • In manufacturing, the manufacturer is the taxpayer and the accrual of the tax occurs with the first delivery or making available, in Spanish territory, of the manufactured products or with the total or partial collection of the price, if payments are made in advance of the delivery or making available of the manufactured products.
  • In the case of importation, the importer is the taxpayer and the tax accrues when the import duties are accrued in accordance with customs legislation.
  • In intra-Community acquisition, the taxpayer is the intra-Community acquirer and the accrual of the tax occurs on the 15th day of the month following that in which the transport or dispatch to the acquirer begins or at the time the invoice is issued, if this is earlier.

In the case of intra-Community manufacture or acquisition, the settlement period is monthly or quarterly, depending on the VAT settlement period, in accordance with the volume of operations or other circumstances provided for in the tax regulations.

In the case of imports of products subject to the tax, the tax will be settled by customs in accordance with the provisions for customs debt in the customs regulations.

In case your company may be affected by this new tax, please do not hesitate to contact us.