2024 EN

Taxation of the gratuitous contribution of private assets to the community of acquisitions

The contribution of private assets without economic consideration to the community property is an operation worthy of being studied from a tax point of view, especially after the last ruling of the Supreme Court.


The subjection to the Tax on Onerous Patrimonial Transmissions is discarded, since in this case we speak of gratuitousness, instead of onerousness. This fact in turn raises its possible taxation in the Tax on Donations, since it is an intervivos delivery free of charge. However,

the marital partnership, given its lack of legal personality, is not a taxpayer of said tax, reasoning set forth in Supreme Court Ruling No. 295/2021, of March 3, 2021, and reiterated again in the new ruling of January 10, 2024.

On the other hand, it is particularly interesting to study the taxation in the Personal Income Tax. Specifically, the ownership of the assets of the marital partnership must be attributed to each spouse in equal halves, which implies an alteration in the assets of the contributor, and it must be determined whether the same is considered a capital gain or a capital loss. The latter will be calculated by the difference between the transfer value and the acquisition value of half of the property being contributed, in accordance with articles 35 and 36 of the LIRPF.


From our firm, we recommend seeking specialized tax advice before carrying out this type of operation to study its cost, or once it has already been carried out, to include it correctly in the tax return, especially now that the income tax campaign is approaching.


Isabel María Díaz Rubio

Equalisation of rights of non-residents in Solidarity Tax for Large Fortunes

On 27 December 2023, Royal Decree 8/2023 was published, amending the Law on the Solidarity Tax for Large Fortunes. This modification means that non-resident taxpayers who in 2022 were obliged to file Form 718 of the Solidarity Tax for Large Fortunes, can now recover part of the amount paid to the Tax Agency.

Prior to the publication, non-resident taxpayers in Spain, obliged to file the ISGF for their assets and rights located in our country (real obligation), were not entitled to the application of the minimum exemption of 700,000 euros, unlike resident taxpayers.

Consequently, a new possibility has been opened to request a refund of 11,900 euros plus the corresponding late payment interest for all those non-resident taxpayers who filed Form 718 in the 2022 tax year.

Should you require any further information, MDG Advisors will be pleased to advise you and help you receive your refund.

MDG Advisors Team

The choice between exemption or deduction for the avoidance of international double taxation cannot be changed after the voluntary deadline

Tax management is a crucial aspect of tax administration at both national and international level. In the area of international double taxation, the choice between exemption or deduction plays a fundamental role in optimising the taxes paid by taxpayers. However, it is important to note that this choice cannot be changed after the voluntary deadline, which underlines the importance of making informed and strategic choices from the outset.

International double taxation occurs when a taxpayer is taxed on the same income in two or more countries. To avoid this scenario, many countries have established double taxation agreements that allow taxpayers to choose between two options: exemption or deduction.

Exemption means that income earned abroad will not be taxed in the country of residence, while deduction allows taxes paid abroad to be deducted from the tax payable in the country of residence. Both options have significant tax planning implications and can greatly impact the taxpayer’s final tax burden.

It is crucial to understand that the choice between exemption or deduction is a strategic decision that must be made in an informed and conscientious manner.

Recently, the High Court of Justice of the Balearic Islands in a ruling of 4 December 2023 concluded that these are two different and incompatible tax regimes, so the taxpayer must opt for the application of one of them at the time of filing his self-assessment and that the taxpayer must opt for the application of one of them at the time of filing his self-assessment.

As we have mentioned throughout this article, the choice between exemption or deduction to avoid international double taxation is a crucial process in the tax management of taxpayers with international income. The impossibility of changing this choice after the voluntary deadline highlights the importance of careful consideration and tax planning. By understanding the implications of each option and seeking professional advice, taxpayers can optimise their tax situation and meet tax obligations effectively.

Carmen Moya López

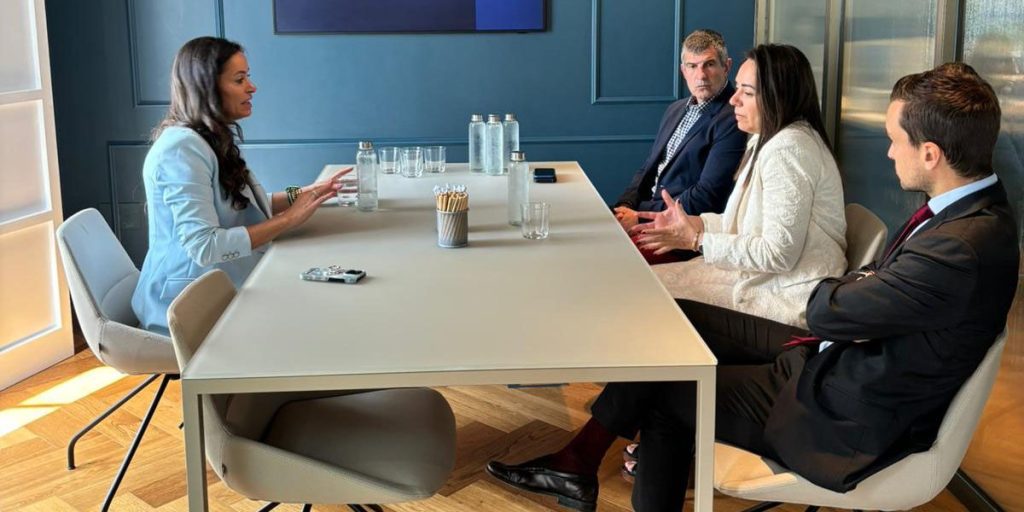
Visit of Alicia Izquierdo, Councillor for Innovation of Malaga City Council, to MDG Advisors: Exploring the digital transformation of traditional services in the province

We were honoured to receive a visit from Alicia Izquierdo, Councillor for Innovation at Malaga City Council, at MDG Advisors. During her stay, we explored the transformative impact that technological development has had on traditional services in the province of Malaga.

We discussed how the integration of technology has revolutionised various sectors, from customer service to administrative management, and how this has contributed to improving the efficiency and quality of services offered to citizens.

We thank Alicia Izquierdo for her visit and her interest in learning first-hand how MDG Advisors is contributing to innovation and technological development in our province. We are committed to continue collaborating with Malaga City Council and other entities to promote initiatives that drive progress and improve the lives of our citizens.

Digitalization of notarial services

As anticipated in a previous publication of this blog dated May 11, 2023, the enactment of Law 11/2023 of May 8, published in the Official State Gazette (BOE), has represented a relevant event in the modernization of the Spanish notarial system.

This law, by incorporating Directive (EU) 2019/1151 of the European Parliament and of the Council dated June 20, 2019, has introduced substantial changes in the field of company law, promoting the adoption of digital tools and processes.

The updated legal framework has generated significant modifications in the Notary Law, facilitating the performance of certain notarial and registry procedures telematically. This development eliminates the need for the physical presence of grantors or interested parties in certain procedures.

As for the innovations implemented, with effect from November 9, 2023, it is worth highlighting the establishment of a single electronic notary office at the national level, under the supervision of the General Council of Notaries. This centralized office not only reflects a change in notarial management, but also facilitates the execution of all digital notarial services.

In addition, the formation of an exclusive computerized index has been established, managed by the General Association of Notaries, which merges the indexes of documents notarized individually by each notary. In this sense, the Association will be in charge of informing the tax administrations about the relevant information contained in this index, having tax impact.

Similarly, it establishes the power for notaries to issue authorized copies through the use of qualified electronic signatures, the latter being equivalent in conditions to the traditional copies in physical format.

Additionally, the execution of various legal acts and transactions by videoconference and by means of the use of qualified electronic signature through the notary’s electronic office is authorized.

Likewise, those involved have the possibility of carrying out different procedures through electronic appearance, such as the presentation of background information, the formalization of legal acts or transactions, the request for copies, and the request for identification of notarial documents.

These modifications, among others, signal a notable advance in the execution of notarial procedures in Spain, adjusting to European guidelines and leading to a substantial improvement.

From MDG Advisors we advise you to stay informed about future updates to take full advantage of this digital evolution.

Sandra Gámez Chaves.

Economic activity of leasing for tax purposes.

Unlike other economic activities, property rental has been subject to certain requirements in order to be considered as such for tax purposes, which we will discuss below.

For Income Tax, according to Article 27 of the LIRPF, property rental is considered an economic activity when it is carried out by at least one person employed under a full-time employment contract. However, it is worth noting that it will be necessary to prove to the Tax Agency that the employee has a sufficient workload. Currently, the legislation is more permissive, no longer requiring the need to have premises used exclusively for the management of the rental of the property.

Therefore, if the aforementioned requirement is not met, the income obtained from the lease would be declared in the income tax return as income from real estate capital, in addition to being taxed for imputation of income for the period of the year not rented, while if it is met, it would be taxed for economic activities.

In relation to Corporate Income Tax, currently, in accordance with Article 5 of the LIS, the legislation requires the same measures as the previous tax, while in Value Added Tax, without the need for any additional requirements, the leasing of real estate is considered in itself an economic activity. This can be seen in Article 5 of the LIVA, which states, among the concepts of entrepreneur, “those who carry out one or several supplies of goods or services that involve the exploitation of a tangible or intangible asset with the aim of obtaining continuous income over time”.

On the other hand, it will be particularly relevant in Wealth Tax and Inheritance and Gift Tax whether or not the leasing of real estate is determined as an economic activity in Personal Income Tax, given that it will allow access or not to certain tax benefits in certain autonomous communities, such as the 99% reduction in Inheritance and Gift Tax in the Autonomous Community of Andalusia, for holdings in family businesses.

The latter demonstrates the importance of good tax planning to optimise the future tax burden, which is why, from our office, we advise you to consult a professional to study your case.

Isabel María Diaz Rubio.

Equalisation between non-residents and residents in Spain/Filing deadline for rental of real estate

After an intense month of January in professional offices, it ended with a pleasant surprise for non-resident taxpayers in Spain, with the introduction of modifications to the ministerial orders that approve the self-assessment forms 123, 210, 216, by means of Order HDA/56/2024, of 25 January, published in the BOE on 31 January 2024.


As a prelude to the explanation of the changes introduced by Order HDA/56/2024, of 25 January, it is worth reviewing the entire methodology of Form 210. This form must be used to declare any type of income obtained by a non-resident taxpayer (income, imputed income from real estate, and capital gains).


This form can be used both to declare each accrual of income separately and to declare several items of income obtained in a given period as a group, in accordance with the following rules:


  1. a) Income derived from transfers of real estate: Each accrual of income shall be declared separately. Exceptionally, when the property transferred is jointly owned by a married couple in which both spouses are non-residents, a single self-assessment may be made. In the case of losses, this self-assessment must also be submitted if you wish to exercise your right to a refund of the withholding that has been made.


  1. b) Rest of income: Several incomes obtained by the same taxpayer may be grouped together provided that they correspond to the same income type code, they come from the same payer, the same tax rate is applicable to them and, in addition, if they derive from an asset or right, they come from the same asset or right. However, in the case of income from rented or sublet property not subject to withholding tax, it may be grouped together with the same requirements except for income from the same payer, although when declaring income from property from several payers it will be necessary to indicate a specific code for the type of income, 35 (income from property not subject to withholding tax with grouping of payers).


Under no circumstances may the grouped income be offset against each other.


Having set out all the information related to Form 210, it is worth mentioning the modification that affects non-resident taxpayers, introduced by Order HDA/56/2024, of 25 January. This modification is related to the deadline for filing Form 210 for the lease or sublease of real estate rented by a non-resident taxpayer.


As from 2024, non-resident taxpayers with property rented in Spain will be able to file annually from 1 to 20 January of the following year, instead of continuing to do so on a quarterly basis, as they had been doing until the aforementioned modification. In other words, in the case of annual grouping of income derived from the lease or sublease of real estate, accrued from 1 January 2024, the filing period will be from 1 to 20 January of the year following the accrual year, i.e. from 1 to 20 January (15 January if the tax is to be paid by direct debit) of the 2025 tax year.


In this way, the discrimination that non-resident taxpayers in Spain had to file Form 210 on a quarterly basis is eliminated, with respect to a tax resident in Spain, who does so on an annual basis, for the same taxable event (the leasing or subleasing of real estate).


Leticia Cayuela Mayor.

Transfer of shares in a company owning real estate: commercial and tax implications, problems and effects

The sale of companies whose assets consist of real estate should, from a commercial and tax point of view, be studied in detail in accordance with the regulations in force, as otherwise it could be classified as tax avoidance by avoiding the legal transaction of the sale and purchase of the real estate in question.

Firstly, from a commercial point of view, it should be noted that the transfer of company shares is regulated in article 106 et seq. of the Capital Companies Act (LSC), which establishes the obligation to notarise the transfer of company shares; however, the Supreme Court ruling of 5 January 2012 establishes that the requirement to notarise the transfer will not be a constitutive requirement, but rather will confer evidentiary value and publicity value to the transfer.

From the point of view of taxation, we must differentiate whether we are dealing with the condition of transferor or acquirer:

In the case of the transferor of the shares, we must bear in mind that, as it is a company, he/she will incur a capital gain or loss which will be included in the taxable base for corporation tax.

On the other hand, in the case of the acquirer of the shares, Article 45. I, B, 9 of Royal Legislative Decree 1/1993, of 24 September, approving the revised text of the Law on Transfer Tax and Stamp Duty (TRLITPAJD) establishes that “transfers of securities, whether or not they are admitted to trading on an official secondary market, shall be exempt (…) in accordance with the provisions of Article 108 of Law 24/1988, of 28 July, on the Stock Market”.

Similarly, Article 314. 1 of the Securities Markets Law (LMV) exempts the transfer of securities, both from the point of view of ITP and VAT; However, the second paragraph of the aforementioned article states that “transfers of securities not admitted to trading on an official secondary market carried out on the secondary market are exempt from the provisions of the previous paragraph, which will be subject to the tax to which they are subject as transfers of real estate for valuable consideration, when such transfers of securities are intended to avoid payment of the taxes that would have been levied on the transfer of the real estate owned by the entities to which the securities represent”.

In this regard, the Directorate General for Taxation establishes in its CV V0096-19 the concurrence of three requirements for the application of the NON-exemption:

1.- That it is a transfer of securities carried out on the secondary market, which excludes the acquisition of newly issued securities, which would take place on the primary markets.

2.- That the securities transferred are not admitted to trading on an official secondary market, which excludes transfers of securities admitted to trading on such a market (without prior temporary admission requirement).

3.- The intention or intention to evade payment of the taxes that would have been levied on the transfer of the real estate owned by the entities to which these securities represent (animus defraudandi), which is a question of fact that cannot be determined a priori by this Management Centre, but must be sufficiently proven by the tax administration responsible for the management of the applicable tax.

The question we could ask ourselves is: in what cases does one act with the intention of avoiding payment of the corresponding tax? Article 314 of the LMV itself provides an answer to this question and establishes that, unless there is proof to the contrary, it will be understood that there is an intention to avoid payment when:

(a) Control is obtained over an entity at least 50 per cent of whose assets consist of real estate located in Spain that is not assigned to business or professional activities, or when, once that control has been obtained, the shareholding in it increases.

  1. b) Control is obtained over an entity whose assets include securities that enable it to exercise control over another entity at least 50 per cent of whose assets consist of real estate located in Spain that is not involved in business or professional activities, or when, once this control has been obtained, the shareholding in it increases.
  2. c) The securities transferred have been received for contributions of real estate made when companies are incorporated or their share capital is increased, provided that such assets are not used for business or professional activities and that no more than three years have elapsed between the date of contribution and the date of transfer.

Thus, it should be borne in mind that the presumption that at least 50% of the company’s assets are not assigned to an economic or business activity cannot be proven otherwise, since the requirements set by the legislator are specific and will be analysed in a later article. Otherwise, there may be other types of presumptions where it would be necessary to make allegations, but it will be up to the competent tax administration to prove the intention to avoid payment.

In summary, and in the case of this type of operation, it is essential to seek advice in order to avoid any type of regulatory risk which, as we have analysed, is not trivial in the case of transfers of shares in companies whose assets are made up of real estate.

At MDG Advisors we have a specialised team that will advise you in detail to your personal situation in order to obtain the best result for your needs.

Jesús Raya Zamora.

Form 347: Characteristics, obligations and recommendations

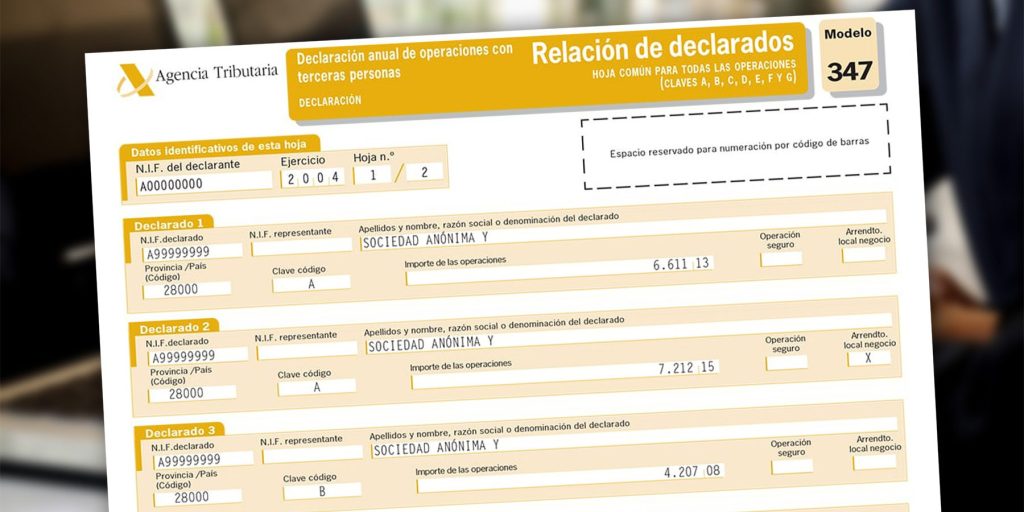
After a turbulent month of January fiscally speaking, February arrives bringing with it the Annual Informative Declaration of Transactions with Third Parties, which is filed by filling out Form 347. This form must detail the commercial transactions carried out with third parties during the previous fiscal year.

This informative declaration has annual character and is presented during the month of February, concluding the term of presentation corresponding to the fiscal year 2023, the next 29th.

The obligation to file Form 347 arises when the total amount of transactions, including taxes, exceeds €3,005.06 and, when calculating this limit, it is essential to accurately separate deliveries and acquisitions of goods and services, which are declared quarterly.

The responsibility for filing this return falls on individuals and companies that carry out business or professional activities, as established in the Value Added Tax Law. This includes communities of property under horizontal property regime, social entities and those who charge fees or rights on behalf of their associates.

However, there are exceptions and, among other circumstances, those operating outside Spain, individuals under specific tax regimes and those who do not exceed certain transaction limits may be exempt. Also excluded are those who keep electronic books through the electronic office of the State Agency of Tax Administration (Agencia Estatal de Administración Tributaria).

They are also excluded from the obligation to be declared:

  • Deliveries of goods or provision of services for which taxpayers are not required to issue and deliver invoices.
  • The operations that have been previously declared in other informative declarations, as it is the case of the operations declared in the Forms 180 and 190.
  • Transactions involving the delivery of goods to third countries (imports and exports of goods). However, those of services must be declared.
  • In case of a transaction with inversion of the taxpayer (acquisition of services from third countries), the corresponding box must be checked.
  • Deliveries and acquisitions of goods between the Spanish mainland or the Canary Islands, Ceuta or Melilla.
  • Deliveries of goods subject to VAT (exempt and non-exempt) must be declared separately.
  • The operations declared in the Form 349 (informative declaration of intracommunity operations).

Regarding the ways of filing Form 347, the Tax Agency distinguishes between individuals who may file their return with advanced electronic signature or using the signature system with access key in a previous registration as a user (Cl@ve PIN), while taxpayers attached to the Central Delegation of Large Taxpayers, legal entities and entities without legal personality, are required to file electronically by means of advanced electronic signature.

In summary, the Annual Declaration of Operations with Third Parties is a complex tax process that requires attention to ensure the accuracy of the declaration of business operations of the previous year, since it is necessary to analyze in detail the casuistry in each specific case. If you need more information about this declaration, do not hesitate to contact MDG Asesores and our tax team will be pleased to assist you.

Sandra Gámez Chaves

Modification of the rebate applicable to Wealth Tax in Andalusia

The publication of Law 12/2023, on the Andalusian Budget for 2024, has brought with it relevant modifications to the 100% regional rebate on the Wealth Tax (IP), introduced by Decree-Law 7/2022, which led to tax residents in Andalusia not paying this tax in 2022.

However, with the entry into force of the Solidarity Tax for Great Fortunes approved through Law 38/2022, of 27 December, it led to IP taxpayers in Andalusia with a wealth of more than 3.7 million euros to pay this tax.

All this has forced the Andalusian government to reform the regulation. This reform is contained in the new Transitional Provision 5 of Law 5/2021.

Transitional Provision 5 of Law 5/2021 introduces significant changes to the allowances applicable to Wealth Tax in Andalusia. Firstly, it establishes that, during the term of the ITSGF, Andalusian taxpayers have the option to choose between two types of relief, both of which are mutually incompatible.

The first option allows taxpayers to apply a rebate determined by the difference between the full amount of the Wealth Tax and the joint limit established by the regulations corresponding to the ITSGF, in accordance with the provisions of the State Law. This choice implies that the revenue generated by the tax remains in the Treasury of the Junta de Andalucía.

The second option consists of maintaining the 100% rebate on the full amount of the Wealth Tax, as previously established. However, in this case, taxpayers will be obliged to declare and contribute to the ITSGF, and the collection corresponding to this tax will be directed to the State Treasury.

Opting for either of the two alternatives does not result in any increase in the tax burden for the taxpayer, but simply changes the destination of the tax payable.

Sara Gámez Córdoba.