
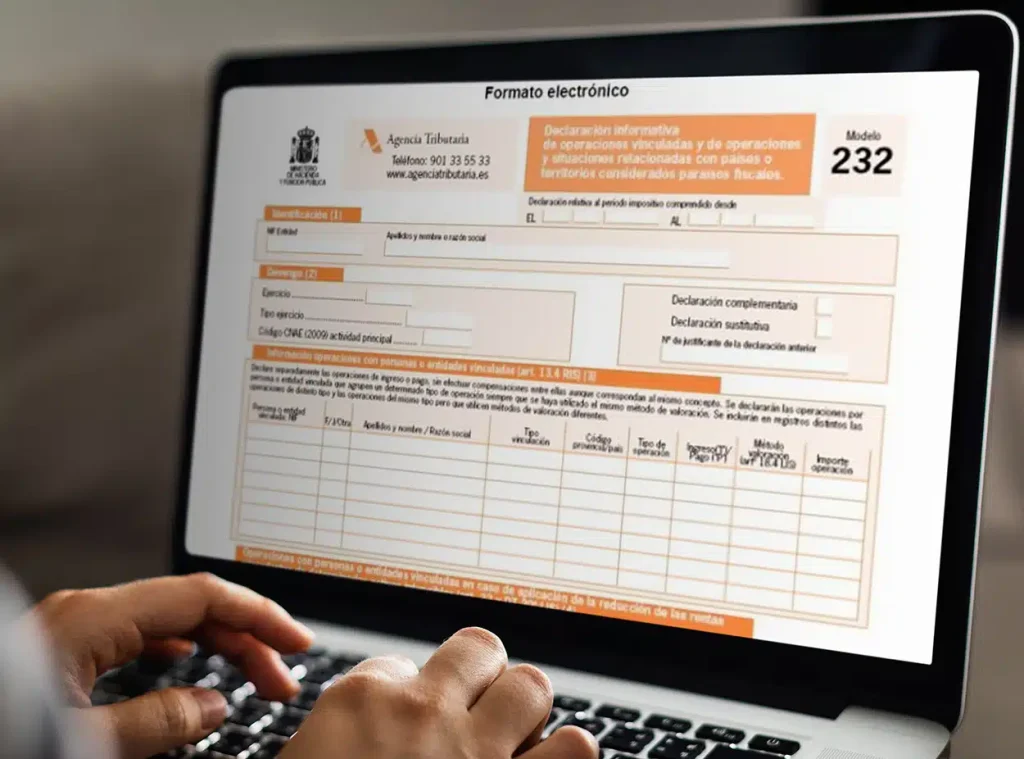
During the month of November, companies must comply with an important tax obligation: the filing of Form 232, an informative return concerning related-party transactions and transactions or situations involving countries or territories classified as tax havens.
What is Form 232?
Until the 2016 fiscal year, this information was included in Form 200 of the Corporate Income Tax return. However, for tax periods beginning on or after January 1, 2016, the Spanish Tax Agency requires this information to be filed separately through Form 232, with the aim of improving control and transparency in transactions between related entities.
Filing Deadline
Form 232 must be filed within the month following the ten months after the end of the tax period.
For example, if the fiscal year ends on December 31, the filing period will be from November 1 to November 30 of the following year.
Who Is Required to File?
The following must file Form 232: corporate income taxpayers, non-residents with a permanent establishment, and entities under the income attribution regime constituted abroad but with a presence in Spain, provided they carry out any of the following transactions:
- a) Transactions carried out with the same related person or entity when the total amount during the fiscal year exceeds €250,000, based on market value.
- b) Specific transactions (*) carried out with related persons or entities, when the total amount of each type of such transaction during the fiscal year exceeds €100,000.
- c) Transactions with related persons or entities of the same type using the same valuation method, when the total amount of such transactions during the fiscal year exceeds 50% of the entity’s net turnover.
- d) Transactions in which the taxpayer applies the reduction on income derived from certain intangible assets provided for in Article 23 of the Corporate Income Tax Law, because income is obtained from the transfer of such intangibles to related persons or entities.
- e) Transactions or holdings of securities in countries or territories classified as tax havens, regardless of the amount.
(*) The following are considered specific transactions:
(i) Those carried out by Personal Income Tax taxpayers engaged in an economic activity under the objective estimation method with entities in which they or their spouses, ascendants, or descendants hold, individually or jointly, 25% or more of the share capital or equity;
(ii) Transfers of businesses;
(iii) Transfers of shares or interests representing equity in entities not listed on regulated markets;
(iv) Transfers of real estate; and
(v) Transactions involving intangible assets.
Exemptions
The following transactions are exempt from reporting:
a) Transactions carried out between entities belonging to the same tax consolidation group.
b) Transactions carried out by Economic Interest Groupings (EIGs) and Temporary Business Associations (UTEs) (except when applying the regime established in Article 22 of the Corporate Income Tax Law).
c) Transactions carried out within the framework of public takeover bids or public offerings for sale.
Form 232 must be filed exclusively online, through the Electronic Headquarters of the Spanish Tax Agency (Agencia Tributaria).
The filing of Form 232 represents a key obligation for entities engaged in related-party transactions or those involving countries or territories classified as tax havens. Meeting this requirement accurately and within the established deadlines is essential to ensure transparency and proper compliance with tax obligations.
Sara Gámez Córdoba.