2025 ENG

Related-Party Transactions: Their Importance in Proper Formalization

During November, we focused on the preparation and filing of Form 232, the informative declaration for related-party transactions and transactions with non-cooperative jurisdictions. Based on this experience, we want to share some essential professional recommendations.

Related-party transactions must always be valued at market conditions, in accordance with Articles 17 and 18 of the Corporate Income Tax Law, and be properly documented.

For loans and credit lines between related parties, it is crucial to formalize agreements and set a market-based interest rate.

Commercial transactions between related parties should be valued using the most appropriate method depending on the goods or services provided.

To ensure regulatory compliance, we recommend documenting all transactions in the Transfer Pricing Manual, a key tool to demonstrate that the conditions applied are equivalent to those in transactions between independent companies, reducing tax risks.

We remain available to provide specialized advice and assist with any questions regarding Form 232 and related-party transactions.

New ruling on the deduction of expenses for non-residents

In July this year, the Spanish National Court issued a relevant ruling affecting non-resident owners with rented properties in Spain. Until now, only residents of the European Union were allowed to deduct expenses related to rental income, while residents of third countries were required to pay tax on the full amount received.

The National Court recognized this right for a taxpayer residing in the United States, considering that denying the deduction violates both the principle of free movement of capital under the Treaty on the Functioning of the European Union and the principle of non-discrimination set out in the Double Taxation Agreement between Spain and the United States.

Although this ruling does not establish legal precedent, it represents an important step towards equalizing the tax treatment of EU and non-EU residents. It is still too early to initiate claims for tax corrections or refunds for non-prescribed fiscal years, but the decision marks significant progress in addressing a long-standing discriminatory situation.

Avoid a €500,000 Shock: The Truth About Spain’s Solidarity Tax with Miriem Diori, MDG Advisors

Investing in Spain can be highly attractive, especially in Málaga and the Costa del Sol, but understanding the Solidarity Tax on Large Fortunes is essential to avoid unexpected costs.

Although Wealth Tax has been abolished in Andalusia, the national Solidarity Tax still applies to individuals with net assets exceeding €3.7 million per person.

  • Residents are taxed on their worldwide assets.

  • Non-residents are taxed on assets located in Spain, including real estate, bank accounts, and investment portfolios.

Without proper planning, some investors have faced annual tax bills of up to €500,000. Structuring investments correctly — for example, purchasing jointly with a spouse or partner — can significantly reduce or even eliminate this tax.

Early professional tax and legal advice is key to investing in Spain with confidence and peace of mind.

New court ruling: Wealth Tax limits for non-residents in Spain.

In Spain, tax residents face certain limits on their tax and solidarity contributions, based on their economic capacity and personal income tax (IRPF) situation.

A recent Supreme Court ruling confirms that these limits can also apply to non-residents, as restricting them to residents only could be considered discriminatory. This opens the door for non-residents to adjust their tax obligations based on their assets in Spain.

To understand how these limits affect your situation, it’s important to review your tax status and filings.

Christmas dinner 2025

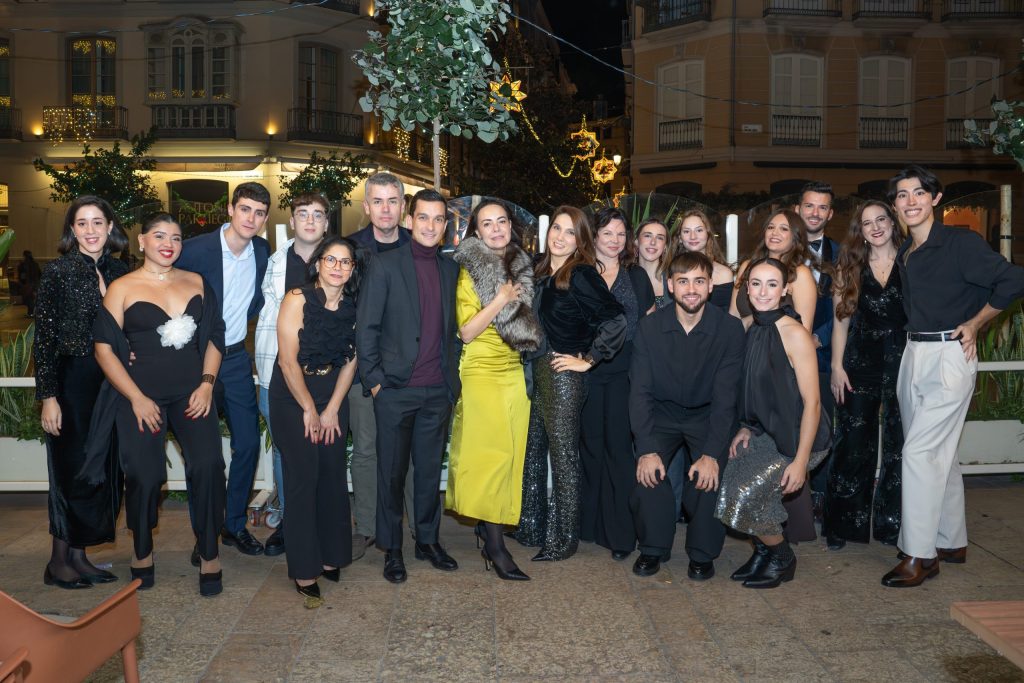
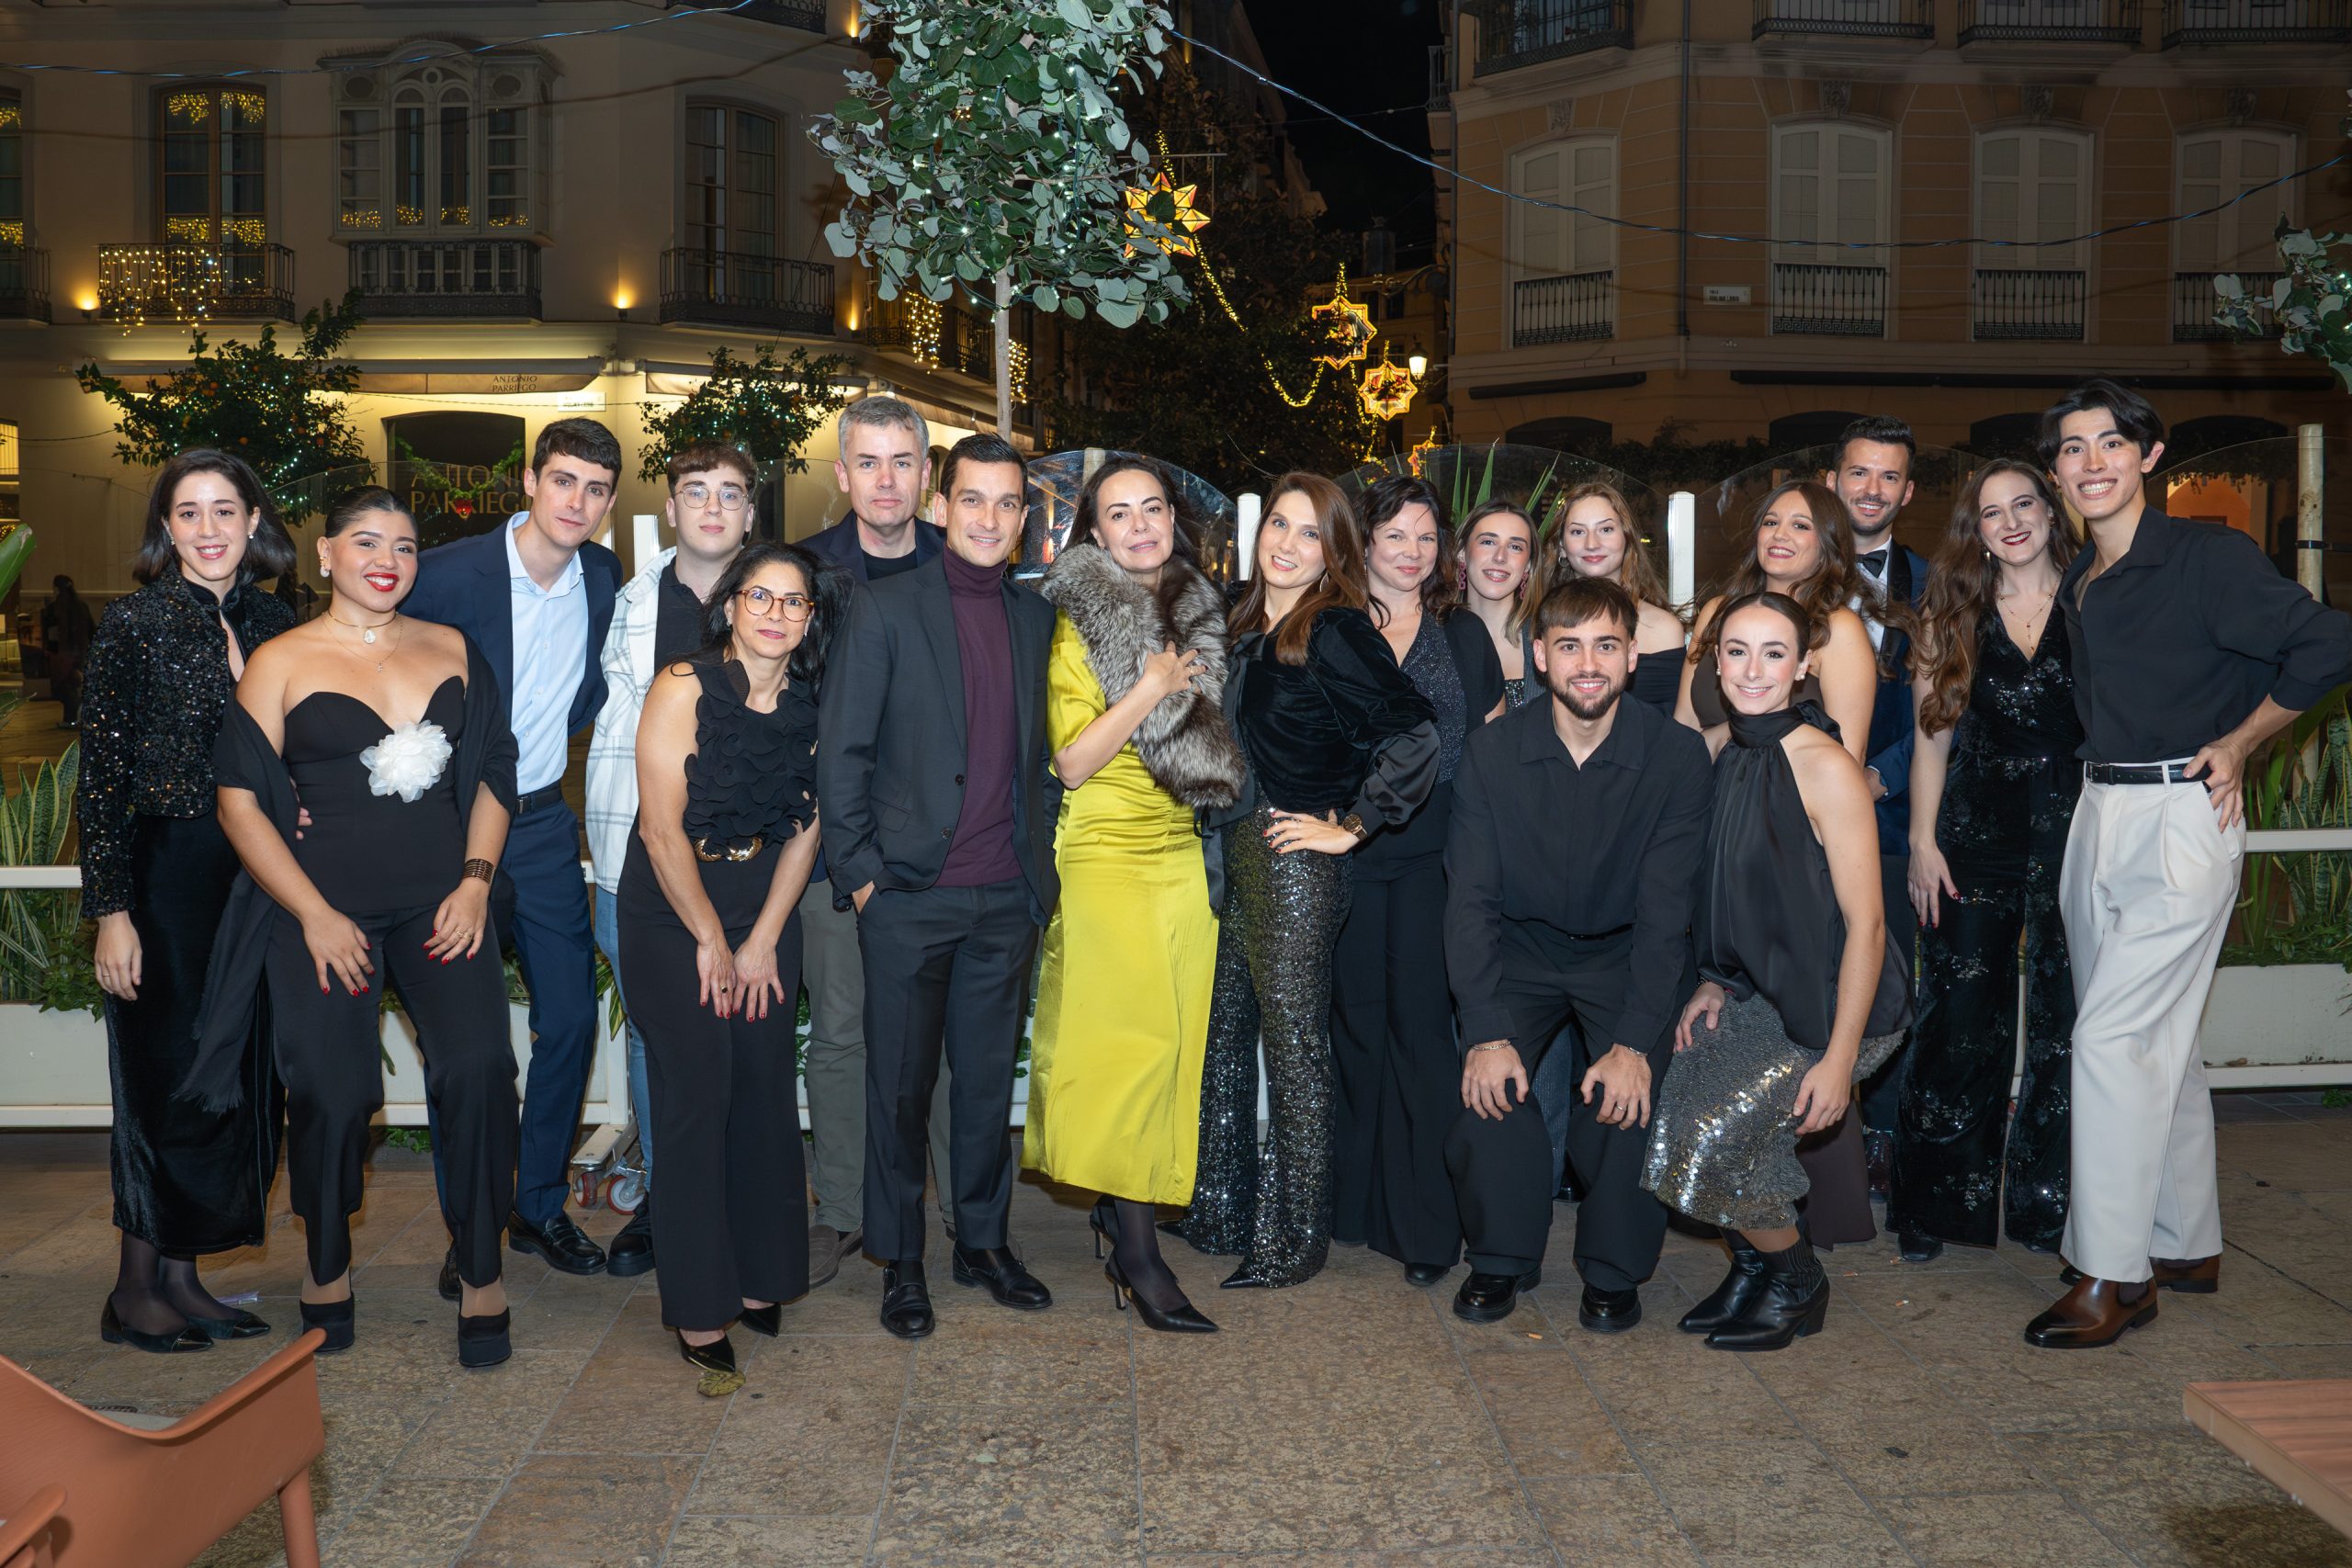
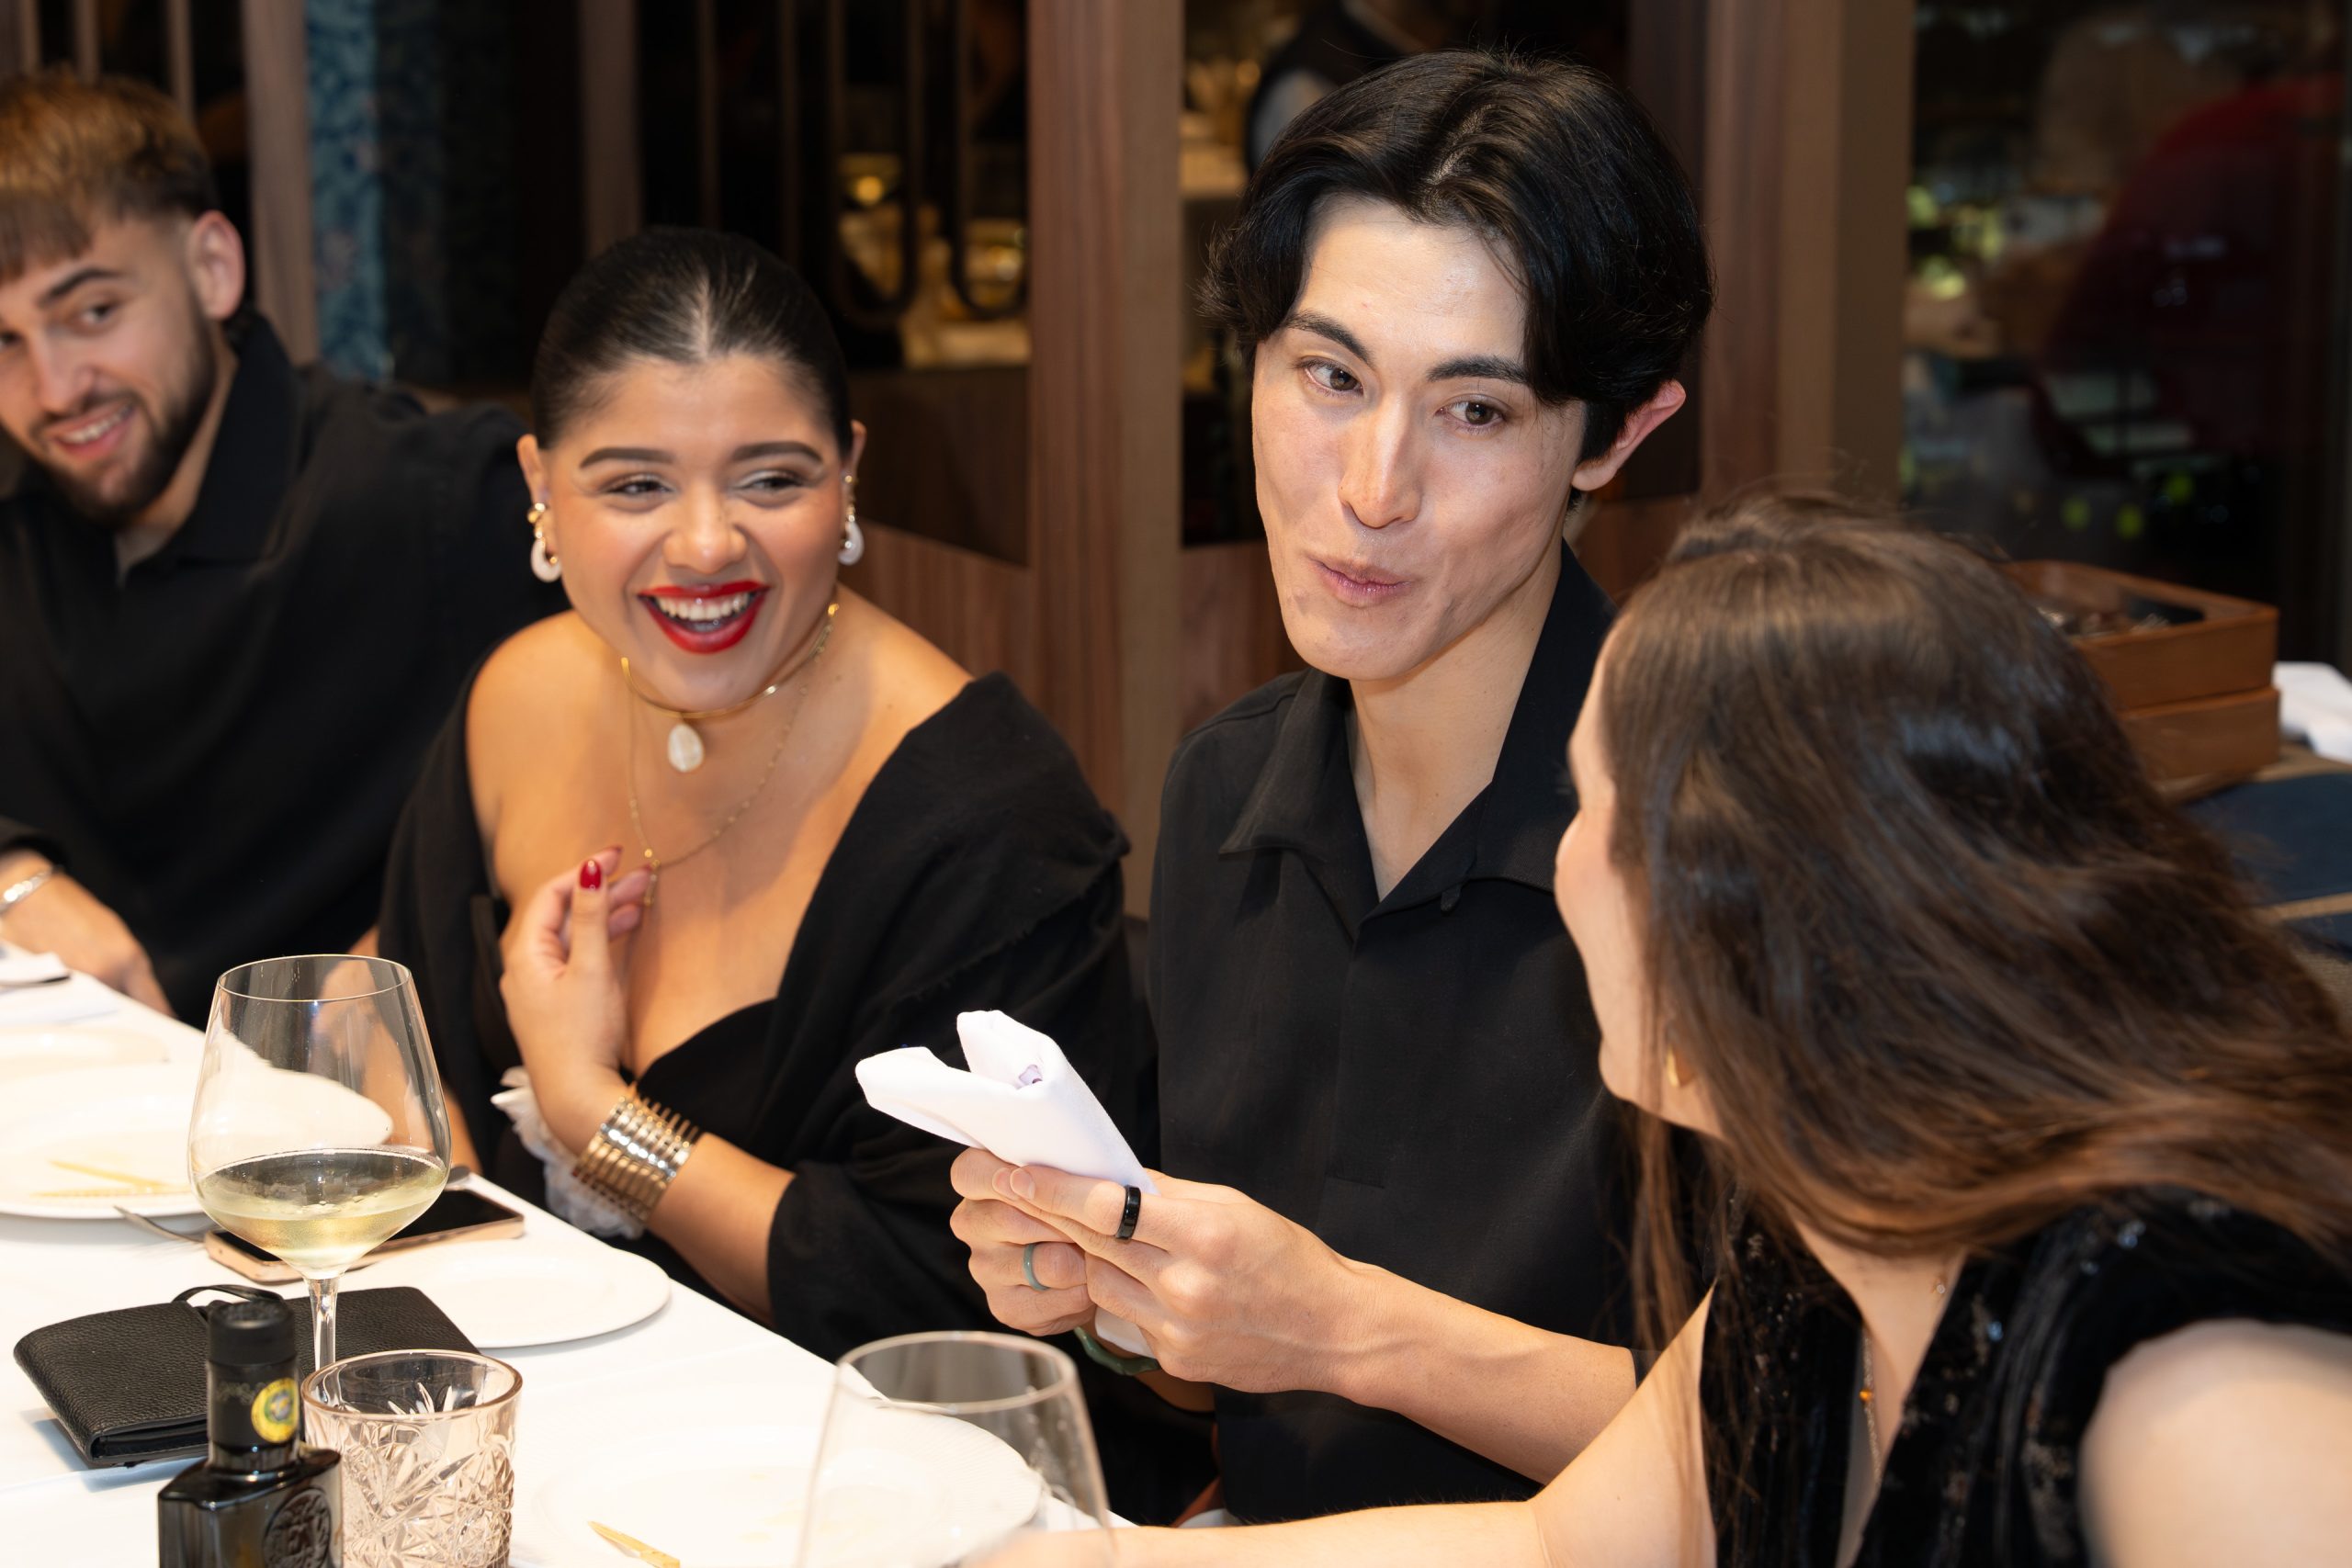
We would like to share some moments from our Christmas dinner, a time to pause, share, and give thanks for the great work done by the entire team throughout the year.

Laughter, good company, and lots of enthusiasm to continue growing together. Thank you to everyone who is part of MDG Advisors and makes this project possible every day.

✨ Here’s to a new year full of challenges and shared successes!


We wish you a Merry Christmas

From all of us at MDG Advisors, we wish you a Merry Christmas and a joyful holiday season. Thank you for your trust, collaboration, and continued support throughout the year.

Verifactu moratorium: What your company needs to know about this.

In December 2025, the Government approved a further extension of the obligation to implement the Verifactu verifiable invoicing system. (Legal News)

The new effective dates are:

  • For companies subject to corporation tax: 1 January 2027.
  • For all other companies and, where applicable, self-employed persons and professionals: 1 July 2027.

In practice, this means that the formal obligation to issue invoices under the Verifactu standard is postponed for an additional year.

What is Verifactu and why does it matter?

Verifactu is the electronic invoicing system designed by the Tax Agency (AEAT) whose objective is to guarantee the authenticity, integrity and traceability of invoices issued by companies and professionals.

Invoices issued under Verifactu must be generated using certified software, include a unique identifier and, where applicable, a QR code, and be securely recorded so that the AEAT can access them at any time.

The purpose of this regulation is to strengthen controls against tax fraud, improve transparency and standardise electronic invoicing in Spain.

What does the moratorium mean for your company?

The positives — more time to prepare for the transition

  • Additional time to adapt systems: If you have not yet incorporated compatible software or are in the process of implementing it, you now have more time, until 2027, to do so at your leisure.
  • Less rush for immediate technological investment: Avoid hasty decisions in December 2025 — you can plan ahead with greater foresight.
  • Opportunity to calmly review internal processes: Opportunity to coordinate accounting, invoicing, filing and internal reporting before the requirement comes into effect.

But that doesn’t mean you can leave everything to the last minute

  • The moratorium only postpones the requirement; the system is still planned. You must continue planning.
  • If your company had already begun the adaptation process — changing software, internal processes, training — you should review those plans in light of the new deadline (and anticipate that suppliers will update their software).
  • Regulatory uncertainty remains: the postponement reflects organisational difficulties, which underscores the importance of accompanying the transition with advice.

What our consultancy would recommend — steps to take now

As your consultancy, we propose the following actions to take advantage of the extra time and ensure an orderly transition:

  1. Evaluation of the current invoicing system
  2. Check whether your invoicing software meets the technical requirements of Verifactu (certification, unalterable registration, possibility of generating unique identifiers, etc.).
  3. Planning for technological adaptation
  4. If it is necessary to change or update software, define internal deadlines, costs, testing and staff training well in advance.
  5. Design of robust internal processes
  6. Prepare a standard procedure for issuing, archiving and backing up invoices in accordance with the new system; define responsibilities within the company.
  7. Internal communication and training
  8. Inform the entire team — finance, accounting, administration — about the importance of the new regulations and their correct use.
  9. Simulation of adaptation scenarios
  10. Conduct pilot tests with the new system before it becomes mandatory to detect errors or integration failures.

What this moratorium means for your company in the medium term

Although the moratorium may seem like a respite, it does not eliminate the obligation—it only postpones it. The ideal approach is not to wait until 2026 or 2027 to act, but to take advantage of this margin now to:

  • Calmly implement a modern invoicing system.
  • Reduce the risk of future penalties for non-compliance.
  • Optimise accounting and administrative processes, improving efficiency and thus saving time and costs.
  • Take advantage of the transition to implement good internal control practices and secure digital archiving.

Conclusion

The government’s decision to postpone the mandatory implementation of Verifactu until 2027 offers your company a valuable opportunity to adapt at your own pace. However, realistically speaking, the moratorium should not be interpreted as an indefinite delay: the system will become mandatory, and it is advisable to prepare as soon as possible.

Our tax advisory service is at your disposal to accompany you throughout the process: from evaluating your current system to implementing the new software, including training your team and defining internal processes. If you wish, we can organise an information session for clients, explain the regulations in detail and prepare a personalised action plan tailored to your structure.

Capital Gains from Selling a Home: Differences Between Improvements and Repairs

At MDG Advisors, we often see clients wanting to include all expense invoices when calculating capital gains from the sale of a property. However, this is not always allowed.

The Tax Agency clearly distinguishes between improvements and repairs or maintenance expenses. Only improvements—actions that increase the property’s value, enhance its livability, or extend its useful life—can be added to the purchase price, reducing the taxable gain. Examples include completely renovating a kitchen or bathroom, replacing electrical wiring, or installing efficient climate control systems.

Expenses aimed at keeping the property in normal condition, such as painting, fixing dampness, or replacing old windows, do not reduce capital gains, although they may be deductible if the property is rented.

In practice, the line between improvements and repairs is not always clear, leading to different interpretations. That’s why it’s essential to review each case carefully and maintain proper documentation. At MDG Advisors, we help our clients make the right decisions and optimize taxation when selling their property.

Allocation of real estate income under the expatriate regime (Beckham Law)

We would like to inform you of a recent interpretative change that affects taxpayers covered by the special tax regime for expatriates, commonly known as the Beckham Law, in relation to the treatment of their primary residence in Spain.

As is well known, this regime allows certain individuals who move to Spain to be taxed as if they were non-residents: in general terms, a fixed rate is applied to certain income obtained in Spain and they are not subject to income tax on their worldwide income. However, when it comes to its application, there have always been doubts as to the extent to which the rules of Non-Resident Income Tax (IRNR) or Personal Income Tax (IRPF) should be followed.

One of the aspects that had been causing the most uncertainty was the allocation of real estate income. In particular, there was a question as to whether the impatriated taxpayer should declare a presumed income for the property they own in Spain that is at their disposal, even when that property is their habitual residence and is not rented out.

Until recently, there were criteria that were more favorable to taxpayers. In particular, some court rulings had held that, applying the logic of personal income tax by analogy, the habitual residence of the impatriate should not generate income attribution, as is the case with the habitual residence of an “ordinary” resident taxpayer in Spain.

However, in a recent ruling, the Central Economic-Administrative Court (TEAC) has modified this approach and concluded that taxpayers covered by the Beckham Law must be taxed on the property they have at their disposal in Spain, even when it is their habitual residence. In practice, this means that the impatriate is treated, for these purposes, as a non-resident owner of an urban property for their own use.

From our firm’s perspective, this ruling reinforces the idea that: 

Special regimes, such as those for impatriates, can be very attractive from a tax point of view, but they are also particularly exposed to changes in the interpretative criteria of the Administration and the courts.

This context increases the level of review and control over this profile of taxpayers and makes an individualized analysis of each specific case even more advisable.


Selling a Property in Spain as a Non-Resident: What You Need to Know

If you are a tax resident in another country and are selling a property in Spain, you must pay taxes here, even if you don’t live in the country. This is regulated through the Non-Resident Income Tax (IRNR), which applies to the capital gain: the difference between the sale price and the purchase price, minus deductible expenses such as Property Transfer Tax (ITP)/VAT, renovations, and notary or registry fees.

The tax rate depends on your residence: 19% if you are an EU resident and 24% if you are a non-EU resident. Additionally, the buyer must withhold 3% of the sale price as an advance on the tax.

Key tip: keep all receipts and documents to calculate your gain correctly and minimize taxes.

At MDG, we help you comply with regulations and pay taxes correctly, avoiding mistakes and penalties.