2025 ENG

Form 347: The Key to Complying with your Tax Obligations and Avoiding Penalties

In February we are not free from tax obligations either. In this case, we have to file Form 347, an annual informative declaration that must be filed by businessmen and professionals who carry out transactions with third parties that, as a whole, exceed 3,005.06 euros during the fiscal year 2024.

Some of the transactions that must be declared in this form are:

  • Non-reimbursable subsidies and grants.
  • Operations of insurance companies.
  • Advances from customers and suppliers.
  • Leases not subject to withholding.
  • Deliveries and acquisitions of goods and services, both those subject to and not exempt from VAT and those not subject to or exempt from VAT.
  • Real estate transactions.

However, there are always some exemptions, such as taxpayers whose tax domicile, permanent establishment or place of business is not in Spain, or transactions considered as deliveries and acquisitions of goods between the Spanish mainland or the Canary Islands, Ceuta or Melilla, among others.

The information provided in Form 347 is crucial to guarantee transparency in business relations and ensure compliance with tax obligations, so that the Tax Agency can control tax fraud and ensure that transactions between companies and self-employed people are correctly declared.

In short, we consider that it is important to comply with this informative declaration to avoid legal problems and ensure compliance with current regulations.

If you are interested and need more information, do not hesitate to contact MDG Advisors. We can help you!

Lucía Luengo Aguado.


The New Regulation on Electronic Timekeeping: Changes and Repercussions for Companies in 2025

In recent years, the control of working hours has been one of the most debated issues in the workplace in Spain. The new regulation on electronic timekeeping is designed to ensure compliance with regulations on working hours and overtime, an issue that has become more relevant with the 2021 labour reform. This change requires all companies to keep a record of their employees’ daily working hours, a process that must be digitised and adapted to current technology. Below, we analyse the main aspects of this new regulation and its impact on companies.

What is electronic timekeeping?

Electronic clocking in and out is a tool that allows workers to record the start and end of their working day using digital means, such as computer systems, mobile applications or electronic cards. The main objective of this system is to guarantee transparency in the management of working time and to facilitate the control of hours worked, something essential to avoid fraud related to overtime and compliance with compulsory breaks.

New legal requirements

The regulation of electronic time and attendance was introduced following a series of amendments to the Law on the Workers’ Statute. According to current legislation, all companies are obliged to establish a system for monitoring working hours, recording the exact start and end times of the working day, as well as any overtime worked. This obligation affects all companies, regardless of their size or sector.

Electronic time and attendance is, therefore, one of the best solutions for complying with this regulation efficiently. Electronic systems allow records to be stored digitally, which facilitates access and management, as well as simplifying the task of the employees in charge of supervising time and attendance.

How does it affect companies?

With the implementation of electronic time and attendance, companies must ensure that the system they use is reliable, accessible and compliant with data protection regulations. Information on working hours must be stored for at least four years, and workers have the right to access these records if they wish.

Investment in these systems should be made with efficiency in mind and with a view to ensuring that there are no errors in the records. Companies should adapt as soon as possible to avoid sanctions and ensure that their workers have an efficient tool that respects their labour rights. Without a doubt, electronic timekeeping is here to stay and is set to transform the way we manage working time in the workplace.

Aaron Cheung Gallardo


Tax obligations in January: the first step towards year-end.

The beginning of the year marks a critical period for companies in terms of compliance with tax obligations. January is an intense month in which both quarterly and annual returns, VAT refund requests and the closing of the previous tax year must be attended to. Below we detail the main responsibilities that companies must manage in this period.

Quarterly returns:

One of the first tax commitments of the year is the filing of the quarterly returns corresponding to the fourth quarter of the previous year. These include:

  1. Quarterly VAT return. This reflects the operations carried out during the fourth quarter and determines the balance to be paid or offset in the following period.
  2. Quarterly personal income tax withholdings and payments on account on income from work and economic activities, prizes and certain income allocations.
  3. Quarterly return of withholdings and payments on account of Personal Income Tax (IRPF) on income or income from the rental or subletting of urban property.
  4. Quarterly return of payments on account of personal income tax, for business people and professionals.

These returns must be filed before 20 January, although the deadline may be slightly extended if you choose to pay by direct debit.

Annual returns:

January is also the month in which several annual information returns are filed, which are essential for tax control and to provide data to the Tax Agency. Among the most relevant are:

  1. Annual VAT summary, where all the operations carried out during the year are compiled and compared with the quarterly returns.
  2. Annual summary of withholdings and payments on account of Personal Income Tax (IRPF) on income from the rental of urban property.
  3. Annual summary of withholdings and payments on account of Personal Income Tax (IRPF) on income from work, economic activities, prizes and certain income allocations.

These returns must be filed before 31 January and are essential to close the tax year correctly.

Application for a VAT refund

Companies that have accumulated a VAT balance in their favour during the year can apply for a refund using Form 303 of the fourth quarter tax return. To do so, they must meet certain requirements, such as being registered in the Monthly VAT Refund Register (REDEME) or having carried out exempt transactions with the right to deduct.

Applying for a VAT refund is a process that requires precision, as the Tax Agency may require additional information or carry out checks before making the refund.

Closing the tax year

The closing of the tax year is a complex process involving the review and adjustment of the annual accounts. Some of the key actions to be taken include:

  1. Review of Income and Expenditure: Ensure that all income and expenses for the year are correctly recorded and adjusted.
  2. Depreciation and Provisions: Calculate and record asset write-offs and provisions necessary to cover possible losses or debts.
  3. Bank Reconciliation: Verify that all bank movements are correctly reflected in the company’s accounts.
  4. Inventory: Carry out a count and valuation of the inventory at the end of the financial year in order to adjust the stock.

A proper closing not only ensures compliance with tax obligations, but also provides a clear and accurate view of the company’s financial situation, facilitating strategic decision-making for the new year.

In conclusion, compliance with tax obligations in January is crucial to avoid penalties and ensure proper financial management. Companies must be attentive to the deadlines for filing quarterly and annual returns, as well as VAT refund claims and the closing of the tax year. Adequate planning and expert professional advice are key to successfully facing this important period of the year.

Jesús Raya Zamora.

The BOE publishes the government’s new tax package, effective as of Sunday 22 December.

The Official State Gazette (BOE) has published the Government’s new fiscal package, which came into force on Sunday 22 December 2024, one day after its publication in the BOE. BOE.

This reform introduces a number of significant measures to the Spanish tax system, which are detailed below. which are detailed below:

We come across a key component related to the bank levy, a tax that was initially set up as a temporary ‘property benefit’ under a decree motivated by the needs of the a decree motivated by the economic needs arising from the war in Ukraine, ending on 31 December. The transformation into a tax has a number of new implications new implications: its permanent nature and its decentralised management to the regional and autonomous communities. and autonomous communities; depending on them the disbursement of 7.2 billion euros coming from the 7.2 billion euros from European funds.

The tax on banks’ interest margins and commissions has been reconfigured. banks has been reconfigured. This tax, which is now progressive in nature, establishes the following tax rates tax rates: 1% up to EUR 750 million, 3.5% up to EUR 1.5 billion, 4.8% up to EUR 3 billion, 6% up to EUR 5 billion, 4.8% up to EUR 3 billion, 6% up to EUR 5 billion and 7% above EUR 5 billion. 5 billion.

On the other hand, actions are implemented to combat tax fraud in the commercialisation of hydrocarbons, especially against of hydrocarbons, especially against the operations of companies that misappropriate the VAT collected companies that appropriate the VAT charged on the supply of fuels to petrol stations, thus preventing the sale of products for

This prevents products from being sold below the market price and, as a result, less revenue being collected, less revenue is collected.

An increase in taxes on vaping devices and tobacco is introduced, with the aim of discouraging the sale of vaping products at below-market prices. to discourage consumption and improve public health. VAT is harmonised at European level for European level for short-term rentals of dwellings, mainly affecting tourist rental platforms. mainly affecting tourist rental platforms. The obligation to issue and electronic invoicing is extended to all commercial relations between entrepreneurs and professionals, with a view to professionals, seeking to improve transparency and fiscal control.

With regard to corporate income tax, the measures have been as follows:

A reform of the Corporate Tax for small companies is implemented. The companies with a turnover of less than one million euros will see a reduction in their corporate Corporate Income Tax. The taxable base up to 50,000 euros will be taxed at a rate of 17%, and the rest of the taxable base will be taxed at a rate of 17%. 50,000 will be taxed at 17%, and the rest of the taxable base will be taxed at 20%. This reduction will be gradual until 2027.

With regard to personal income tax, capital income above 300,000 euros will increase its taxation by two percentage points. 300,000 euros will increase their taxation by two percentage points, from 28% to 30%.

A measure has been approved to ensure that people with absolute permanent incapacity or severe disability do not lose their pension or severe disability do not lose their pension if they take up a job and are subsequently unable to continue with it. continue with it.

A bonus is established for hiring by non-profit, non-professional sports organisations, promoting professional non-profit sports organisations, promoting employment in the amateur sports sector. The reform also approves a provision on exceptional income from artistic activities.

The legislation is also amended to allow the funds from the Reserve for Investments in the Canary Islands (RIC) to be used for the refurbishment of subsidised housing for renting, while maintaining its tax for renting, while maintaining its tax regime.

This tax package aims to modernise the Spanish tax system, increase revenue and combat tax fraud, in order to and combat tax fraud, in line with the commitments made to the European Union. European Union.

If you have any doubts regarding the new tax reform, we remain at your disposal to to offer you the best advice on the regularisation of your tax situation.

Normative modifications in ITP in the acquisition of a squatted property: acquisition value or reference value

It is noticeable that the Christmas holidays are approaching, with the illusion in the streets full of people, the children running down the street, the Christmas lights of our beloved Calle Larios, and from MDG Advisors, we want to join in that joy, and inform you of a recent consultation of the Directorate General of Taxes, which on this occasion, is not to the detriment of the taxpayer.

As we know, and this is nothing new, article 10 of the revised text of the Law on Transfer Tax and Stamp Duty, approved by Royal Legislative Decree 1/1993, of 24 September, establishes that ‘the taxable base is constituted by the value of the property transferred or of the right that is constituted or transferred’.

In the case of real estate, its value will be the reference value provided for in the regulations governing the land registry, at the date of accrual of the tax.

However, if the value of the real estate declared by the interested parties, the price or agreed consideration, or both, are higher than the reference value, the higher of these values will be taken as the taxable base.

And in line with the above, and with the aim of providing you with the good news that we mentioned at the beginning of the blog, the Directorate General of Taxes in the binding consultation V2002-24, establishes that in cases where a property is acquired that is occupied, tax may be paid on the acquisition of the same at the acquisition value instead of the reference value, representing a tax saving for the taxpayer, since normally when a property is acquired that is occupied, the acquisition value is lower than the value determined by the Cadastre (reference value).

This is due to the fact that according to the Resolution of the General Directorate of Cadastre, in the case of residential real estate, where there is no legal regime regulating the relationship between owner and occupier (when the two do not coincide), and this prevents the free disposal of the property by the owner, this is a situation which may imply, where applicable, that the reference value of a real estate does not exist.

Taking into account this change of criteria, we are reviewing all the deeds of purchase of real estate that our clients have made in order to request the return of undue income in favour of our clients.

If you find yourself in a similar situation, we remain at your disposal to provide you with the best advice on the regularisation of your tax situation.
Leticia Cayuela Mayor

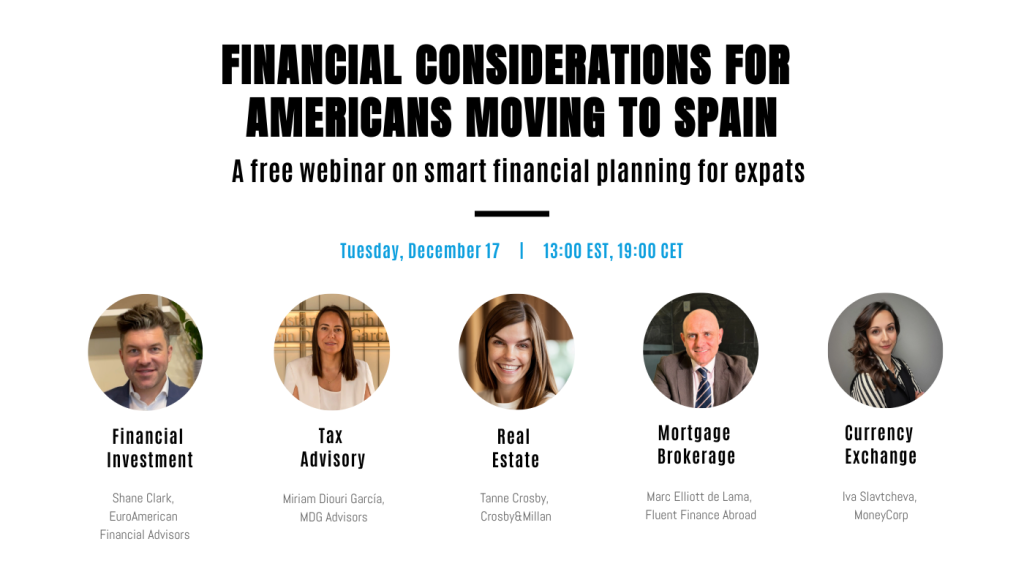
Are you considering moving to Spain?

Don’t miss this free webinar on smart financial planning for expats!

🗓 Date: Tuesday, 17 December
⏰ Time: 13:00 EST | 19:00 CET

📢 Experts in key areas will give you top tips:

💼 Financial Investing – Shane Clark, EuroAmerican Financial Advisors
📊 Tax Advice – Miriam Diouri García, MDG Advisors
🏠 Real Estate – Tanne Crosby, Crosby&Millan
🏦 Mortgage Broker – Marc Elliott de Lama, Fluent Finance Abroad
💱 Foreign Exchange – Iva Slavtcheva, MoneyCorp

This webinar is ideal for US expats who want to ensure a successful transition to Spain. Learn how to manage your investments, taxes, real estate and more.

📌 Register now and secure your place!


Malaga: The Boom as Best Expatriate Destination

In recent years, Malaga has established itself as one of the most attractive destinations for expatriates from all over the world. According to a study published by Internations, an expat website with more than 5 million users, Malaga has been voted the best expat destination worldwide.

From its vibrant cultural life and enviable climate to its growing infrastructure and the quality of life it offers, this Andalusian city has earned a top spot on lists of the best places to live outside your home country. So what makes Malaga so special for expats? Let's break it down.

···

One of Malaga biggest attractions is its Mediterranean climate. With over 300 days of sunshine a year, the city is a paradise for those looking to escape the cold winters and constant rain. Mild temperatures throughout the year allow for outdoor living, whether on the beach or strolling in the nearby parks and mountains. This not only improves the quality of life, but also has a positive impact on overall health and well-being.

Attractive Cost of Living

Compared to other major European cities, the cost of living in Malaga is relatively low. Although prices have increased in recent years due to the growing interest in the city, it is still more affordable than other destinations such as Madrid, Barcelona, London or Paris. Est

The Expatriate Community in Malaga

The presence of a growing expatriate community has been one of the driving forces behind Malaga rise as a preferred destination. Increasing numbers of British, German, French, Nordic, and other nationalities are moving to the city, creating a vibrant cultural mix. This phenomenon has prompted the creation of groups, associations and services to help new residents integrate, share experiences and adapt to their new home.

In addition, the Spanish language is a great asset for expatriates who wish to learn Spanish and immerse themselves in the local culture. Many expatriates take advantage of Spanish classes and other services to facilitate their integration.

Professional and Business Opportunities

Although Malaga was historically known as a tourist destination, in recent years it has experienced a boom in the technology and business sector. The growth of technology companies, startups and the development of spaces such as the Parque Tecnológico de Andalucía (PTA) have attracted entrepreneurs and professionals in the digital sector.

The city is also known for being an excellent connection point for international business due to its proximity to Africa and the rest of Europe. Business initiatives and events have multiplied, making Malaga a hub of opportunities for expatriates looking to develop professionally.

For all of the above reasons, Malaga is the perfect destination for expatriates looking for a mix of sunshine, quality of life, a welcoming international community and professional opportunities. Its climate, infrastructure, competitive cost of living and relaxed lifestyle have
made this Andalusian city one of the most sought after for those wishing to start a new life in Spain. With more and more foreigners choosing Malaga as their home, the city continues to evolve, living up to its title as one of the best expatriate destinations in Europe.

Pablo Mallo Bárcena – MDG Advisors

Non-resident income tax return filing deadline approaching

What is the Non-Resident Income Tax without permanent establishment?

The Non-Resident Income Tax is a tax that levies the incomes obtained in Spanish territory by individuals or entities that are not residents in Spain and do not operate through a permanent establishment.

This tax is declared through Form 210: a tax form that must be submitted by those who own real estate or rights in the country, such as properties, usage rights, habitation rights, and any other type of real right over real estate.

With Form 210, several types of taxes related to real estate and rights in the country can be declared. Below are the different cases:

 Income from Rented or Sublet Properties: income obtained from renting properties.
 Income from Non-Rented Properties: imputed income for owning vacant properties.
 Capital Gains: profits obtained from the sale of properties.
 Imputed Income from Urban Real Estate: imputed income for owning urban properties.
 Income Derived from the Transfer of Real Estate: income obtained from the sale of properties.

Failing to submit the form can lead to financial penalties and the imposition of late-payment interest, so it is important to comply with this tax obligation and its submission deadline to avoid legal and financial problems.

Specifically, given the proximity to the submission deadline, it is vital to remember the declaration of income from non-rented properties, commonly known as the imputation of rents. In other words, it is the obligation of non-residents to declare taxes for the days during
which their property has not been rented, always considering the cadastral value, whether it has been revised or not, and their fiscal domicile. This last variable will depend on whether the non-resident belongs to the European Union or not.

The submission deadline is December 31st, although for direct debit it is December 20th.

Finally, we consider it relevant to inform you that the submission deadline for income derived from the rental of real estate for the year 2024 is during the first 20 natural days of January ·····3·3···32025, being done annually for the first time.

Lucía Luengo Aguado