2025 ENG

MDG ADVISORS and Fuengirola Fencing Club: A partnership for sport and Spanish heritage

At MDG ADVISORS, we are deeply proud of our partnership with the Fuengirola Fencing Club. This partnership represents much more than just a sponsorship; it is a commitment to sport, culture and support for our community.

Our connection with the club is further strengthened by our partner, Miriem Diouri Garcia, a former fencer whose passion for the sport inspires us. For us, it is a true honor to be able to support a minority sport with such deep roots in Spanish history, and especially to support the club where Miriem cultivated her love for fencing for more than 20 years.

Did you know that fencing is the only Olympic sport with Spanish origins? The Spanish school of fencing, developed in the 15th and 16th centuries, laid the foundations for the modern techniques practiced today. From duels of honor to the Olympic stage, fencing remains a sport that demands strategy, speed and precision, qualities that we also value at MDG ADVISORS.

At MDG ADVISORS, we strive to reflect these same values in everything we do. Like fencing, we pursue excellence through strategy, agility and precision. We are proud to celebrate 15 years of trajectory, always in constant pursuit of excellence, as evidenced by our motto.

Fuengirola Fencing Club not only promotes the practice of this noble sport, but also preserves a valuable cultural heritage. We invite everyone to visit their website and social networks to discover more about their activities and how you can join this exciting community.

At MDG ADVISORS, we believe in the power of sport to transform lives and strengthen communities. Our partnership with the Fuengirola Fencing Club is a testament to our commitment to these values.

Artificial Intelligence and taxation: Transforming tax management in companies.

Artificial intelligence (AI) is revolutionising many sectors and taxation is no exception. Companies,
large and small, are beginning to take advantage of the capabilities of AI to transform the way they
manage their taxes. This evolution not only improves efficiency and accuracy, but also forces
professionals in the tax sector to adapt to new tools and methodologies. The impact of AI on taxation
is so profound that it is redefining the traditional tasks of white-collar professionals in the tax field.
Corporate tax administration has traditionally been a complex and laborious task: it requires careful
monitoring of income, expenses and the various tax regulations that can vary by region or type of
business. With the integration of AI into these processes, companies can automate much of the data
collection and analysis, enabling them to quickly detect inconsistencies or areas for improvement. AI
systems can process huge amounts of data in real time, reducing human error and allowing tax
teams to focus on more strategic tasks.
One of the most prominent applications of AI in taxation is the automation of tax return preparation.
Through the use of advanced algorithms, systems can automatically compare company transactions
with tax regulations, ensuring that all legal requirements are met. This not only optimises time, but
also reduces the risk of penalties for errors in tax returns. In addition, AI can offer recommendations
on how to optimise the tax burden, based on historical patterns and changes in tax policies,
providing a competitive advantage.
For this reason, the transition towards an increasingly digitalised and AI-based tax environment
requires companies to adapt quickly to new technologies. Companies must invest in specialised
software that integrates artificial intelligence and provide training to their teams to make the most of
these tools. This adoption of AI not only optimises tax compliance, but also improves financial
planning and risk management.
In this context, companies must be aware of the importance of cybersecurity. The use of AI involves
the collection and processing of large volumes of sensitive data, which requires robust protection
systems. Thus, protection against cyberattacks is essential to ensure that tax and financial
information is secure, especially when cloud platforms are used to manage data and perform tax
processes.
In addition, AI solutions can facilitate regulatory compliance in an increasingly complex global
environment. Many companies operate in different jurisdictions, which means they need to comply
with a variety of tax laws. AI-based systems can help automate this process by analysing the tax
regulations of different countries and automatically adjusting to changes in local laws.
In turn, the impact of AI is not limited to companies as such, but is also transforming the tasks of
‘white collar’ professionals such as accountants, auditors and tax advisors. While these professions
have historically been focused on data analysis and decision-making, AI is making these processes
more efficient and, in some cases, automatable.
For example, accountants no longer need to spend as much time on manual data entry. Instead, they
can focus on more strategic tasks, such as analysing and interpreting the tax results generated by AI.
AI-based systems can quickly identify anomalies and patterns that might otherwise go unnoticed by
professionals, allowing them to focus on making informed decisions.

In addition, tax advisors also benefit from AI, as they can use it to offer personalised advice based on
a company’s data in real time. Thanks to predictive models and data analysis, tax advisors can
anticipate potential problems and propose solutions before they become major issues.
Although AI is revolutionising white-collar professions, it also raises the question of how it will affect
future employability. Some fear that automation will eliminate jobs, but the reality is that AI, rather
than replacing professionals, will allow them to focus on higher value-added tasks, such as strategy
and innovation.
In conclusion, artificial intelligence is changing the way companies manage their taxes, from
automating tax returns to improving operational efficiency. This transformation not only improves
tax compliance, but also offers new opportunities for financial planning and tax optimisation.
Professionals in the tax sector must adapt to this new reality, using AI to optimise their work and
focus on more strategic tasks. At the same time, companies must ensure that they implement the
right tools and adopt security measures to take full advantage of the benefits that AI offers in tax
management. AI is not only transforming the tax sector, it is ushering in a new era of collaborative
work between humans and machines.
Jesús Raya Zamora.


The High Court of Justice of Madrid rules on the tacit acceptance of an inheritance and inheritance tax

On 14 October 2024, the High Court of Justice of Madrid (TSJM) issued a key ruling on inheritance tax. It analysed whether a person who initially rejected an inheritance should be considered an heir for tax purposes due to certain acts that could be interpreted as tacit acceptance of the inheritance.

The case: a repudiated inheritance and tax controversy

The case involved a taxpayer, Mrs Elvira, who formally rejected the inheritance from her sister who died in 2017. However, the Community of Madrid considered that she had carried out acts that showed tacit acceptance of the inheritance, such as the use of funds from the deceased’s bank account and the omission of the inheritance tax.

Initially, the Regional Economic-Administrative Tribunal (TEAR) of Madrid had ruled in favour of the taxpayer and revoked the tax assessment imposed. However, the Community of Madrid challenged this decision before the TSJM, arguing that the facts showed that the taxpayer had implicitly accepted the inheritance.

The decision of the TSJM

The court analysed the facts and concluded that there was sufficient evidence to consider that the taxpayer had tacitly accepted the inheritance. Among the reasons given in the judgement, the following stand out:

  • The taxpayer was listed as authorised on the deceased’s bank accounts.
  • The funds in the accounts were withdrawn in full in the same year as the death.
  • Certain payments were made with the deceased’s money, which could be interpreted as asset management typical of an heir.

Based on the Inheritance and Gift Tax Act, the court determined that these acts implied a tacit acceptance of the inheritance and, therefore, the taxpayer was obliged to pay the corresponding tax.

Consequences and recommendations

Although the court upheld the tax assessment, it decided to revoke the penalty imposed, as the Community of Madrid did not adequately justify the taxpayer’s guilt.

This case highlights the importance of properly managing the renunciation of an inheritance. To avoid tax problems, it is essential to:

  1. Formalise the renunciation before a notary as soon as possible.
  2. Avoid any management or disposal of the deceased’s assets, as this can be interpreted as tacit acceptance.
  3. Consult a tax advisor to determine the tax impact and the best legal options in each case.

Our firm recommends that anyone in a similar situation seek specialised advice to avoid adverse tax interpretations. If in doubt, we are at your disposal to guide you through the process and ensure compliance with your tax obligations.

Sara Gámez Córdoba.

New Corporation Tax Rates

The approval of Law 7/2024 has brought significant changes in the fiscal framework in Spain, particularly regarding the Corporate Tax (IS). These changes are designed to enhance the competitiveness of companies and promote sustainable economic growth.

For the fiscal year 2024, the corporate tax rates have remained largely consistent compared to previous years. The general rate remains at 25%. Likewise, Small and Medium-sized Enterprises (SMEs) will continue to apply a tax rate of 25%, and micro-enterprises, entities whose net turnover of the preceding fiscal year is less than 1 million euros, will apply a reduced tax rate of 23%. Additionally, the 15% rate for newly created entities is maintained.

The changes gain special significance starting from the fiscal year 2025. Law 7/2024 implements changes in the corporate tax rates, aiming to progressively reduce the tax burden on SMEs and micro-enterprises:

  • General Rate: The general corporate tax rate remains at 25%.
  • SMEs: For entities whose net turnover of the preceding fiscal year is less than 10 million euros, the tax rate will progressively reduce each fiscal year as follows:-
  • 2025: 24%
  • 2026: 23%
  • 2027: 22%
  • 2028: 21%
  • 2029 onwards: 20%.
  • Micro-enterprises: For entities whose net turnover of the preceding fiscal year is less than 1 million euros, the tax rate will be progressive:
  • 2025: 21% for the first 50,000 euros of taxable income and 22% for the remainder.
  • 2026: 19% for the first 50,000 euros of taxable income and 21% for the remainder.
  • 2027: 17% for the first 50,000 euros of taxable income and 20% for the remainder.

As a result, it can be observed that in the following fiscal periods, there is a reduction in tax rates, aiming to improve the competitiveness of companies and promote sustainable economic growth.

If you need further information, our firm will be pleased to provide you with the best advice.

Carmen Moya López

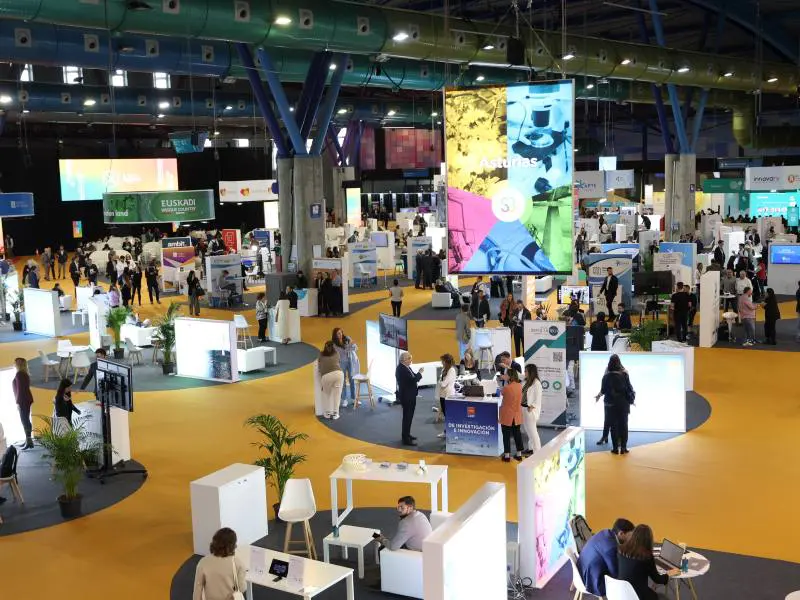
Attending Transfiere 2025 in Malaga

MDG Advisors will be present at Transfiere, Europe’s leading event on R&D&I and knowledge transfer, held at PYCMA, Málaga.

🔬 This key event brings together the Spanish innovation ecosystem, fostering international collaboration, scientific and technological development, and investment opportunities.

🇬🇧 The UK is the guest country this year, and our partner Miriem Diouri, who serves on the National Board of the British Chamber of Commerce in Spain, will be representing us.

Looking forward to connecting, innovating, and building global synergies! See you there! 👏

#Transfiere2024 #Innovation #R&D #BusinessNetworking

Elimination of administrative obstacles: 10% reduced rate of VAT for the purchase of housing without LPO (official planning permission) and without a certificate of occupancy

The Supreme Court, Administrative Disputes Division, through Ruling 82/2025, of January 28, reconciles the taxpayer’s position and removes administrative obstacles when applying the reduced rate of 10% as opposed to the general rate of 21% for the purchase of homes intended as primary residences without the need to obtain a first occupancy license and certificate of occupancy, since, according to the Supreme Court, these only serve to prove that the home meets certain pre-established administrative requirements for it to be used as a human residence.

In this recent ruling, the Supreme Court points out that what is decisive is not so much that the dwellings have a first occupation license as that they are finished and that this is their legal purpose; “suitable for use as dwellings” is exactly the expression to which Law 37/1992, on Value Added Tax, conditions in its article 91. One. 1.7º, the application of the reduced rate to the delivery of buildings or parts thereof by the parties involved in the transaction.

The ruling establishes the following three requirements to benefit from the reduced rate of 10%:

“1st) That it is a question of finished housing, since the delivery of the building, as long as it is not finished, follows the regime of the land on which it is built.

2) The rate applies to all transactions that, in accordance with Article 8 LIVA, are considered to be the delivery of housing, and not to transactions relating to housing that are considered to be the provision of services.

3) According to the usual notion of the term, it is necessary that it be suitable for use “as a room or dwelling for a natural person or family, constituting their home or the seat of their domestic dwelling”.

This last requirement is closely linked to the possible legal destination of the acquired property. Therefore, beware of the exponential growth that has been taking place in recent years within the real estate sector in the acquisition of homes for tourist use, since, as the Supreme Court indicates, it excludes the application of reduced VAT on the purchase of homes intended for tourist apartments, since these cannot be classified as housing because their destination, in no case, can be the habitual residence of a family or natural person.

Therefore, taking into account the regulatory changes to the VAT Law, and the continued growth of the real estate sector in our country, our office advises you to seek advice prior to the acquisition of any real estate due to the numerous tax implications involved in such acquisitions.

If you need further information, our firm will be happy to provide you with the best advice.

Leticia Cayuela Mayor

Easier Access to the Beckham Regime in Spain

Since January 1, 2023, new company directors in Spain have a smoother path to the Beckham tax regime. However, expert guidance is key for a successful relocation and compliance.

⚠️ Tax verifications are expected to increase in 1 to 3 years, so proper planning is essential. 📑

Modelo 720: the ultimate guide to declaring your assets abroad

If you are a tax resident in Spain and own assets or rights outside the country, you are likely familiar with the Modelo 720. While this declaration does not entail direct tax payments, it plays a crucial role in ensuring fiscal transparency. This article provides a comprehensive overview of the procedure and outlines everything you need to know.

The Modelo 720 is an informational declaration that must be submitted by tax residents in Spain who possess assets or rights abroad, provided that their value exceeds certain thresholds. Although it is not a tax payment form, it holds significant importance for the accurate declaration of these assets.

The Modelo 720 must be filed by all tax residents in Spain who hold assets or rights abroad that surpass certain established limits. The primary thresholds are as follows:

  • Bank accounts: If the combined balance of all foreign accounts exceeds 50,000 euros.
  • Securities, insurance policies, rights, and income: If the total value of these assets exceeds 50,000 euros.
  • Real estate: If the total value of real estate located outside Spain exceeds 50,000 euros.

If you have previously filed the Modelo 720, you will only be required to submit it again if there has been an increase in the value of these assets greater than 20,000 euros.

It is important to note that the Modelo 720 must be submitted between January 1st and March 31st of each year, with reference to the assets and rights held during the preceding fiscal year. As such, you are required to adhere to a specific deadline for this obligation, making it imperative not to delay the submission.

In terms of penalties for non-compliance, the consequences can be considerable. Failure to submit the Modelo 720, or submitting it incorrectly, can result in substantial fines. Initially, a fixed fine of 5,000 euros is imposed for each omitted data item or set of data, with a minimum fine of 10,000 euros. Furthermore, if the declaration of foreign assets or rights is incorrect, the penalties may be significantly higher, underlining the importance of ensuring compliance.

In Conclusion

The Modelo 720 is a fundamental tool to uphold fiscal transparency and avoid penalties for non-compliance. If you own assets abroad, it is essential to fulfill this annual obligation and accurately declare your assets. The filing period is between January 1st and March 31st, and you will only be required to submit it again if there has been an increase of more than 20,000 euros in the value of your assets.

Should you have any questions or require assistance with this procedure, please do not hesitate to contact MDG Advisors.


Sandra Gámez Chaves

3th April 2025: Last chance to get a Golden Visa in Spain

The Golden Visa programme, which for more than a decade has allowed foreign investors to obtain residence permits in Spain in exchange for making significant investments, is facing its final deadline. From 3 April 2025, the possibility of obtaining this visa through the acquisition of real estate will be closed, marking the end of an era for this legal instrument.

The Golden Visa was introduced in 2013 as part of a Spanish government plan to attract foreign investment in an adverse economic context, where the economic crisis and the collapse of the real estate market required urgent solutions. This visa allows non-EU investors to obtain a residence permit if they make investments that exceed certain established thresholds. Law 14/2013, on support for entrepreneurs and their internationalisation, was the one that opened this door for foreigners, at a time when the country needed external capital.

In its current version, those who wish to obtain a Golden Visa must make investments that can range from the acquisition of real estate worth more than 500,000 euros, to the investment of more than 2 million euros in Spanish public debt, 1 million in Spanish companies or funds, or in projects that generate employment and promote innovation. This option is especially attractive for those interested in investing in property, as it not only facilitates obtaining residency, but also allows access to a high-yield real estate market.

However, the new legislation approved in January 2025, Organic Law 1/2025 on measures regarding the efficiency of the Public Justice Service, introduces significant modifications to Law 14/2013. Specifically, the twenty-first final provision eliminates the articles that regulate residence permits for investors, putting an end to the possibility of obtaining a Golden Visa. This reform will no longer be valid for new applications after 3 April 2025, although those who have already started the process or have active visas will be able to continue with their procedures in accordance with the regulations in force at the time of the application.

Requirements and procedures for the Golden Visa

For those who want to take advantage of the last few days of this option, it is important that the process is fully completed before the deadline. In the case of investment in real estate, the property is required to be duly registered in the Property Registry, with documents proving that the acquisition was made and registered within the stipulated deadlines.

The specific documents required vary depending on the investment modality chosen. For the purchase of real estate, the applicant must prove ownership of the properties by means of certificates from the Registry, while for investments in public debt or investment funds, additional documentation is required to validate ownership of the investment during the established time frames.

In addition to the investment, certain common requirements must be met, such as being over 18 years of age, having health insurance in Spain, having sufficient financial means to support oneself during the stay, and having no criminal record either in Spain or in the country of residence during the last five years.

What will happen to ongoing applications and current visas?

The new law includes transitional provisions that protect acquired rights. Thus, those who have submitted their application before 2 April 2025 will be able to proceed with the process in accordance with the regulations in force at the time of their application, provided that the investment is correctly registered.

Golden Visas that are already in force will remain valid until their expiry date, and renewals may be processed in accordance with the regulations in force at the time of the original grant.

Alternatives for those interested in residing in Spain

With the elimination of the Golden Visa, the alternatives for investors who wish to reside in Spain in the long term will be reduced. However, there are other residency options, such as visas for job search or permits for social, family or work ties. These options, together with the new reforms that will come into force in May 2025, offer alternative routes for those who wish to settle in the country.

As for the reform of the legislation on non-lucrative residence, the proposal for new taxes on homes acquired by non-EU residents also stands out as part of the government’s measures to curb the housing crisis.

Conclusion

The deadline of 3 April 2025 marks a milestone in the history of the Golden Visa programme in Spain. While those still interested in this type of residence should hurry up with the paperwork, the recent reform opens up new options and challenges for those who wish to stay in Spain in the long term.

Sara Gámez Córdoba.