admin

New Corporation Tax Rates

The approval of Law 7/2024 has brought significant changes in the fiscal framework in Spain, particularly regarding the Corporate Tax (IS). These changes are designed to enhance the competitiveness of companies and promote sustainable economic growth.

For the fiscal year 2024, the corporate tax rates have remained largely consistent compared to previous years. The general rate remains at 25%. Likewise, Small and Medium-sized Enterprises (SMEs) will continue to apply a tax rate of 25%, and micro-enterprises, entities whose net turnover of the preceding fiscal year is less than 1 million euros, will apply a reduced tax rate of 23%. Additionally, the 15% rate for newly created entities is maintained.

The changes gain special significance starting from the fiscal year 2025. Law 7/2024 implements changes in the corporate tax rates, aiming to progressively reduce the tax burden on SMEs and micro-enterprises:

  • General Rate: The general corporate tax rate remains at 25%.
  • SMEs: For entities whose net turnover of the preceding fiscal year is less than 10 million euros, the tax rate will progressively reduce each fiscal year as follows:-
  • 2025: 24%
  • 2026: 23%
  • 2027: 22%
  • 2028: 21%
  • 2029 onwards: 20%.
  • Micro-enterprises: For entities whose net turnover of the preceding fiscal year is less than 1 million euros, the tax rate will be progressive:
  • 2025: 21% for the first 50,000 euros of taxable income and 22% for the remainder.
  • 2026: 19% for the first 50,000 euros of taxable income and 21% for the remainder.
  • 2027: 17% for the first 50,000 euros of taxable income and 20% for the remainder.

As a result, it can be observed that in the following fiscal periods, there is a reduction in tax rates, aiming to improve the competitiveness of companies and promote sustainable economic growth.

If you need further information, our firm will be pleased to provide you with the best advice.

Carmen Moya López

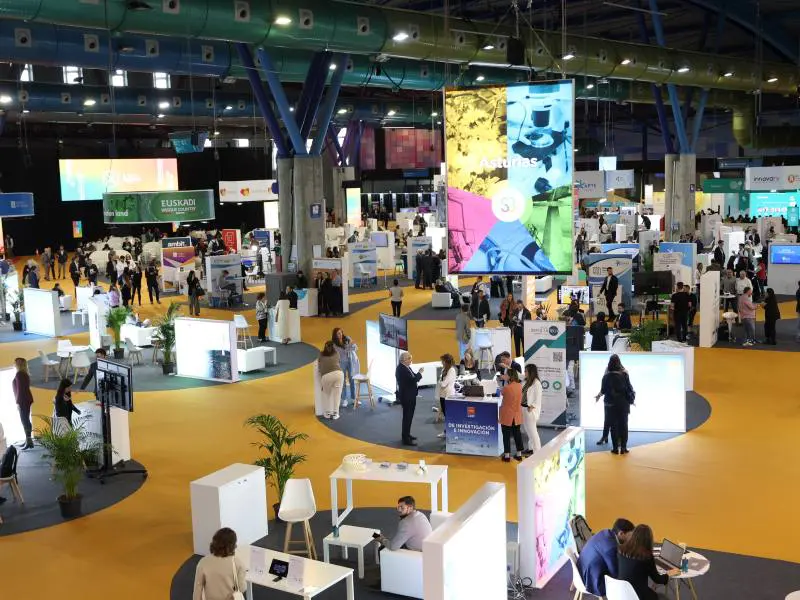
Attending Transfiere 2025 in Malaga

MDG Advisors will be present at Transfiere, Europe’s leading event on R&D&I and knowledge transfer, held at PYCMA, Málaga.

🔬 This key event brings together the Spanish innovation ecosystem, fostering international collaboration, scientific and technological development, and investment opportunities.

🇬🇧 The UK is the guest country this year, and our partner Miriem Diouri, who serves on the National Board of the British Chamber of Commerce in Spain, will be representing us.

Looking forward to connecting, innovating, and building global synergies! See you there! 👏

#Transfiere2024 #Innovation #R&D #BusinessNetworking

Elimination of administrative obstacles: 10% reduced rate of VAT for the purchase of housing without LPO (official planning permission) and without a certificate of occupancy

The Supreme Court, Administrative Disputes Division, through Ruling 82/2025, of January 28, reconciles the taxpayer’s position and removes administrative obstacles when applying the reduced rate of 10% as opposed to the general rate of 21% for the purchase of homes intended as primary residences without the need to obtain a first occupancy license and certificate of occupancy, since, according to the Supreme Court, these only serve to prove that the home meets certain pre-established administrative requirements for it to be used as a human residence.

In this recent ruling, the Supreme Court points out that what is decisive is not so much that the dwellings have a first occupation license as that they are finished and that this is their legal purpose; “suitable for use as dwellings” is exactly the expression to which Law 37/1992, on Value Added Tax, conditions in its article 91. One. 1.7º, the application of the reduced rate to the delivery of buildings or parts thereof by the parties involved in the transaction.

The ruling establishes the following three requirements to benefit from the reduced rate of 10%:

“1st) That it is a question of finished housing, since the delivery of the building, as long as it is not finished, follows the regime of the land on which it is built.

2) The rate applies to all transactions that, in accordance with Article 8 LIVA, are considered to be the delivery of housing, and not to transactions relating to housing that are considered to be the provision of services.

3) According to the usual notion of the term, it is necessary that it be suitable for use “as a room or dwelling for a natural person or family, constituting their home or the seat of their domestic dwelling”.

This last requirement is closely linked to the possible legal destination of the acquired property. Therefore, beware of the exponential growth that has been taking place in recent years within the real estate sector in the acquisition of homes for tourist use, since, as the Supreme Court indicates, it excludes the application of reduced VAT on the purchase of homes intended for tourist apartments, since these cannot be classified as housing because their destination, in no case, can be the habitual residence of a family or natural person.

Therefore, taking into account the regulatory changes to the VAT Law, and the continued growth of the real estate sector in our country, our office advises you to seek advice prior to the acquisition of any real estate due to the numerous tax implications involved in such acquisitions.

If you need further information, our firm will be happy to provide you with the best advice.

Leticia Cayuela Mayor

Easier Access to the Beckham Regime in Spain

Since January 1, 2023, new company directors in Spain have a smoother path to the Beckham tax regime. However, expert guidance is key for a successful relocation and compliance.

⚠️ Tax verifications are expected to increase in 1 to 3 years, so proper planning is essential. 📑

Modelo 720: the ultimate guide to declaring your assets abroad

If you are a tax resident in Spain and own assets or rights outside the country, you are likely familiar with the Modelo 720. While this declaration does not entail direct tax payments, it plays a crucial role in ensuring fiscal transparency. This article provides a comprehensive overview of the procedure and outlines everything you need to know.

The Modelo 720 is an informational declaration that must be submitted by tax residents in Spain who possess assets or rights abroad, provided that their value exceeds certain thresholds. Although it is not a tax payment form, it holds significant importance for the accurate declaration of these assets.

The Modelo 720 must be filed by all tax residents in Spain who hold assets or rights abroad that surpass certain established limits. The primary thresholds are as follows:

  • Bank accounts: If the combined balance of all foreign accounts exceeds 50,000 euros.
  • Securities, insurance policies, rights, and income: If the total value of these assets exceeds 50,000 euros.
  • Real estate: If the total value of real estate located outside Spain exceeds 50,000 euros.

If you have previously filed the Modelo 720, you will only be required to submit it again if there has been an increase in the value of these assets greater than 20,000 euros.

It is important to note that the Modelo 720 must be submitted between January 1st and March 31st of each year, with reference to the assets and rights held during the preceding fiscal year. As such, you are required to adhere to a specific deadline for this obligation, making it imperative not to delay the submission.

In terms of penalties for non-compliance, the consequences can be considerable. Failure to submit the Modelo 720, or submitting it incorrectly, can result in substantial fines. Initially, a fixed fine of 5,000 euros is imposed for each omitted data item or set of data, with a minimum fine of 10,000 euros. Furthermore, if the declaration of foreign assets or rights is incorrect, the penalties may be significantly higher, underlining the importance of ensuring compliance.

In Conclusion

The Modelo 720 is a fundamental tool to uphold fiscal transparency and avoid penalties for non-compliance. If you own assets abroad, it is essential to fulfill this annual obligation and accurately declare your assets. The filing period is between January 1st and March 31st, and you will only be required to submit it again if there has been an increase of more than 20,000 euros in the value of your assets.

Should you have any questions or require assistance with this procedure, please do not hesitate to contact MDG Advisors.


Sandra Gámez Chaves

3th April 2025: Last chance to get a Golden Visa in Spain

The Golden Visa programme, which for more than a decade has allowed foreign investors to obtain residence permits in Spain in exchange for making significant investments, is facing its final deadline. From 3 April 2025, the possibility of obtaining this visa through the acquisition of real estate will be closed, marking the end of an era for this legal instrument.

The Golden Visa was introduced in 2013 as part of a Spanish government plan to attract foreign investment in an adverse economic context, where the economic crisis and the collapse of the real estate market required urgent solutions. This visa allows non-EU investors to obtain a residence permit if they make investments that exceed certain established thresholds. Law 14/2013, on support for entrepreneurs and their internationalisation, was the one that opened this door for foreigners, at a time when the country needed external capital.

In its current version, those who wish to obtain a Golden Visa must make investments that can range from the acquisition of real estate worth more than 500,000 euros, to the investment of more than 2 million euros in Spanish public debt, 1 million in Spanish companies or funds, or in projects that generate employment and promote innovation. This option is especially attractive for those interested in investing in property, as it not only facilitates obtaining residency, but also allows access to a high-yield real estate market.

However, the new legislation approved in January 2025, Organic Law 1/2025 on measures regarding the efficiency of the Public Justice Service, introduces significant modifications to Law 14/2013. Specifically, the twenty-first final provision eliminates the articles that regulate residence permits for investors, putting an end to the possibility of obtaining a Golden Visa. This reform will no longer be valid for new applications after 3 April 2025, although those who have already started the process or have active visas will be able to continue with their procedures in accordance with the regulations in force at the time of the application.

Requirements and procedures for the Golden Visa

For those who want to take advantage of the last few days of this option, it is important that the process is fully completed before the deadline. In the case of investment in real estate, the property is required to be duly registered in the Property Registry, with documents proving that the acquisition was made and registered within the stipulated deadlines.

The specific documents required vary depending on the investment modality chosen. For the purchase of real estate, the applicant must prove ownership of the properties by means of certificates from the Registry, while for investments in public debt or investment funds, additional documentation is required to validate ownership of the investment during the established time frames.

In addition to the investment, certain common requirements must be met, such as being over 18 years of age, having health insurance in Spain, having sufficient financial means to support oneself during the stay, and having no criminal record either in Spain or in the country of residence during the last five years.

What will happen to ongoing applications and current visas?

The new law includes transitional provisions that protect acquired rights. Thus, those who have submitted their application before 2 April 2025 will be able to proceed with the process in accordance with the regulations in force at the time of their application, provided that the investment is correctly registered.

Golden Visas that are already in force will remain valid until their expiry date, and renewals may be processed in accordance with the regulations in force at the time of the original grant.

Alternatives for those interested in residing in Spain

With the elimination of the Golden Visa, the alternatives for investors who wish to reside in Spain in the long term will be reduced. However, there are other residency options, such as visas for job search or permits for social, family or work ties. These options, together with the new reforms that will come into force in May 2025, offer alternative routes for those who wish to settle in the country.

As for the reform of the legislation on non-lucrative residence, the proposal for new taxes on homes acquired by non-EU residents also stands out as part of the government’s measures to curb the housing crisis.

Conclusion

The deadline of 3 April 2025 marks a milestone in the history of the Golden Visa programme in Spain. While those still interested in this type of residence should hurry up with the paperwork, the recent reform opens up new options and challenges for those who wish to stay in Spain in the long term.

Sara Gámez Córdoba. 


Form 347: The Key to Complying with your Tax Obligations and Avoiding Penalties

In February we are not free from tax obligations either. In this case, we have to file Form 347, an annual informative declaration that must be filed by businessmen and professionals who carry out transactions with third parties that, as a whole, exceed 3,005.06 euros during the fiscal year 2024.

Some of the transactions that must be declared in this form are:

  • Non-reimbursable subsidies and grants.
  • Operations of insurance companies.
  • Advances from customers and suppliers.
  • Leases not subject to withholding.
  • Deliveries and acquisitions of goods and services, both those subject to and not exempt from VAT and those not subject to or exempt from VAT.
  • Real estate transactions.

However, there are always some exemptions, such as taxpayers whose tax domicile, permanent establishment or place of business is not in Spain, or transactions considered as deliveries and acquisitions of goods between the Spanish mainland or the Canary Islands, Ceuta or Melilla, among others.

The information provided in Form 347 is crucial to guarantee transparency in business relations and ensure compliance with tax obligations, so that the Tax Agency can control tax fraud and ensure that transactions between companies and self-employed people are correctly declared.

In short, we consider that it is important to comply with this informative declaration to avoid legal problems and ensure compliance with current regulations.

If you are interested and need more information, do not hesitate to contact MDG Advisors. We can help you!

Lucía Luengo Aguado.


The New Regulation on Electronic Timekeeping: Changes and Repercussions for Companies in 2025

In recent years, the control of working hours has been one of the most debated issues in the workplace in Spain. The new regulation on electronic timekeeping is designed to ensure compliance with regulations on working hours and overtime, an issue that has become more relevant with the 2021 labour reform. This change requires all companies to keep a record of their employees’ daily working hours, a process that must be digitised and adapted to current technology. Below, we analyse the main aspects of this new regulation and its impact on companies.

What is electronic timekeeping?

Electronic clocking in and out is a tool that allows workers to record the start and end of their working day using digital means, such as computer systems, mobile applications or electronic cards. The main objective of this system is to guarantee transparency in the management of working time and to facilitate the control of hours worked, something essential to avoid fraud related to overtime and compliance with compulsory breaks.

New legal requirements

The regulation of electronic time and attendance was introduced following a series of amendments to the Law on the Workers’ Statute. According to current legislation, all companies are obliged to establish a system for monitoring working hours, recording the exact start and end times of the working day, as well as any overtime worked. This obligation affects all companies, regardless of their size or sector.

Electronic time and attendance is, therefore, one of the best solutions for complying with this regulation efficiently. Electronic systems allow records to be stored digitally, which facilitates access and management, as well as simplifying the task of the employees in charge of supervising time and attendance.

How does it affect companies?

With the implementation of electronic time and attendance, companies must ensure that the system they use is reliable, accessible and compliant with data protection regulations. Information on working hours must be stored for at least four years, and workers have the right to access these records if they wish.

Investment in these systems should be made with efficiency in mind and with a view to ensuring that there are no errors in the records. Companies should adapt as soon as possible to avoid sanctions and ensure that their workers have an efficient tool that respects their labour rights. Without a doubt, electronic timekeeping is here to stay and is set to transform the way we manage working time in the workplace.

Aaron Cheung Gallardo


Tax obligations in January: the first step towards year-end.

The beginning of the year marks a critical period for companies in terms of compliance with tax obligations. January is an intense month in which both quarterly and annual returns, VAT refund requests and the closing of the previous tax year must be attended to. Below we detail the main responsibilities that companies must manage in this period.

Quarterly returns:

One of the first tax commitments of the year is the filing of the quarterly returns corresponding to the fourth quarter of the previous year. These include:

  1. Quarterly VAT return. This reflects the operations carried out during the fourth quarter and determines the balance to be paid or offset in the following period.
  2. Quarterly personal income tax withholdings and payments on account on income from work and economic activities, prizes and certain income allocations.
  3. Quarterly return of withholdings and payments on account of Personal Income Tax (IRPF) on income or income from the rental or subletting of urban property.
  4. Quarterly return of payments on account of personal income tax, for business people and professionals.

These returns must be filed before 20 January, although the deadline may be slightly extended if you choose to pay by direct debit.

Annual returns:

January is also the month in which several annual information returns are filed, which are essential for tax control and to provide data to the Tax Agency. Among the most relevant are:

  1. Annual VAT summary, where all the operations carried out during the year are compiled and compared with the quarterly returns.
  2. Annual summary of withholdings and payments on account of Personal Income Tax (IRPF) on income from the rental of urban property.
  3. Annual summary of withholdings and payments on account of Personal Income Tax (IRPF) on income from work, economic activities, prizes and certain income allocations.

These returns must be filed before 31 January and are essential to close the tax year correctly.

Application for a VAT refund

Companies that have accumulated a VAT balance in their favour during the year can apply for a refund using Form 303 of the fourth quarter tax return. To do so, they must meet certain requirements, such as being registered in the Monthly VAT Refund Register (REDEME) or having carried out exempt transactions with the right to deduct.

Applying for a VAT refund is a process that requires precision, as the Tax Agency may require additional information or carry out checks before making the refund.

Closing the tax year

The closing of the tax year is a complex process involving the review and adjustment of the annual accounts. Some of the key actions to be taken include:

  1. Review of Income and Expenditure: Ensure that all income and expenses for the year are correctly recorded and adjusted.
  2. Depreciation and Provisions: Calculate and record asset write-offs and provisions necessary to cover possible losses or debts.
  3. Bank Reconciliation: Verify that all bank movements are correctly reflected in the company’s accounts.
  4. Inventory: Carry out a count and valuation of the inventory at the end of the financial year in order to adjust the stock.

A proper closing not only ensures compliance with tax obligations, but also provides a clear and accurate view of the company’s financial situation, facilitating strategic decision-making for the new year.

In conclusion, compliance with tax obligations in January is crucial to avoid penalties and ensure proper financial management. Companies must be attentive to the deadlines for filing quarterly and annual returns, as well as VAT refund claims and the closing of the tax year. Adequate planning and expert professional advice are key to successfully facing this important period of the year.

Jesús Raya Zamora.