admin

New benefits of the 2025 capitalisation reserve

In this article, we address the capitalisation reserve, which is a tax incentive that allows
companies to reduce their tax base if they allocate part of their profits to increasing their own
funds, i.e. their share capital or reserves.

To benefit from this reduction, the company must meet certain conditions, which have been
modified as established in the seventh final provision of Law 7/2024, which has introduced
changes as of 1 January 2025 that seek to optimise this tax incentive.

Firstly, there has been an increase in the percentage reduction from 15% (reduction in force in
2024) to 20%, which is the new percentage included, applicable to the increase in their own
funds. This change reinforces the attractiveness of the capitalisation reserve to improve the
business solvency of Spanish entities.

However, the percentage reduction in the tax base is linked to the increase in the average
workforce of the taxpayer. To show this in a more visual way, it would follow this structure:
– A workforce increase of between 2% and 5% allows for a reduction of 23%.
– For increases of between 5% and 10%, the reduction rises to 26.5%.
– Increases of more than 10% can achieve a reduction of 30%.

In this way, they promote business capitalization, as well as job creation.
Another significant change is the reduction in the maintenance period for the increase in
equity capital. Instead of five years, companies will now only have to maintain the increase for
three years. This adjustment increases flexibility and makes financial planning linked to the
capitalisation reserve more attractive.

The regulations maintain the limit of 20% of the tax base for applying the reduction, with
exceptions for companies whose net income is less than one million euros.
As tax advisors, we understand the complexity of the new provisions and the significant impact
they can have on business management, optimizing tax planning and ensuring maximum use
of the benefits offered.

Carmen Moya López
Repair or improvement? How to classify expenses when you are selling your property.

In the context of the transfer of real estate in Spain, the calculation of capital gains can be a
complex process. An essential element lies in the correct classification of expenses related to
the property, differentiating between those that constitute “repairs” and those that are
categorized as “improvements.” This distinction is crucial, as it has a direct impact on the
determination of the tax base and can avoid possible revisions or future requirements by the
Tax Agency.

According to the Resolution of March 1st, 2013, of the Institute of Accounting and Auditing,
“improvement” is understood to be the set of activities by which an alteration is produced in
an element of the fixed assets, increasing its previous productive efficiency, either by
lengthening its useful life.

On the other hand, according to the jurisprudence of the Supreme Court, in general,
conservation or repair expenses are those whose purpose is to maintain the property in
normal conditions of use, to avoid damage to it or to repair any damage that has occurred,
provided that they do not cause a modification of the structure or habitable surface of the
property and are intended to maintain the useful life of the property and its productive or use
capacity.

It is worth noting that there are many cases in which the Tax Agency considers the existence of
repairs and conservation, rather than improvements and investments:
– Replacement of flooring, lining, scraping or painting of ceilings and walls.
– Complete remodeling of bathrooms and kitchen.
– New electrical and plumbing installation, and changes to taps.
– Replacement of old flooring, windows and air conditioning machines.
– Repair of the sewage system, roof and walls, and installation of beams.
– Renovation of aluminum and woodwork on doors and windows, as well as
waterproofing work.
– Pipe and tiling sanitation, damp and cracks, as they are essential to maintain the useful
life of the property.

In order to justify the disbursements made to the Tax Agency, it is essential to keep the
following detailed documentation for at least four years:
– Complete invoices
– Proof of payment
– Contracts or quotes for the works
– Licenses and permits
– Energy or technical certificates
– Before and after photographs
– Valuation reports

However, at MDG Advisors we are at your disposal for the analysis, preparation and
presentation of your capital gains to avoid possible sanctions.

Lucía Luengo Aguado

Procedure to follow after expired VAT: Possible actions before the Tax Agency

Now that the tax obligations for the first quarter of the 2025 financial year are beginning, and bearing in mind that VAT expires on a quarterly basis, we consider it advisable to recall the possible actions carried out with the Tax Agency in order to recover the expired VAT.

To this end, it is important to emphasise that once the expiry period for recovering VAT established in Law 37/1992 has passed, there are possible actions that can be taken with the Tax Agency to avoid losing unsolicited VAT within the 4-year period. To do this, we must refer to the provisions of Ruling 1443/2013/00/00 of 22 September 2015, which is available in this article.

According to this ruling, when the right to request compensation for the outstanding VAT balance expires, the right to obtain a refund is established with a new limitation period of 4 years, in order to guarantee the neutrality of the tax.

Consequently, once the expiry period stipulated in Article 99 of the VAT Act has elapsed, during which the taxpayer has not been able to offset the excess payments and has not requested a refund, a credit entitlement arises in favour of the taxpayer, subject to the general limitation period for tax matters. In other words, after four years of not being able to offset the outstanding balance, we have another four years to request a refund.

In other words, the taxpayer has a right to the refund of VAT payments that could not be offset as a result of the passage of four years and, therefore, this right does not expire, as it would somehow result in unjust enrichment for the Administration.

It should be borne in mind that the VAT Law does not contemplate any specific procedure for applying this right, so the taxpayer must expressly address the tax authorities in writing requesting the refund of the VAT amounts for which the right to deduct by offsetting has expired.

If we want to analyse the Ruling, based on a simple and practical example, we would have the following:

A company that does not qualify for the monthly VAT refund scheme (REDEME), on 4t2025 could request the VAT generated from 4t2021 to that date (without exceeding the 4-year expiry period), but what would happen to the VAT for the period 1t to 3t of 2021 if that VAT was not requested in 4t2024? Have I already lost it? Well, no, with the Ruling cited in the article, a new possibility of an additional 4 years to recover said VAT is opened up to us.

The review of the expiry of VAT by quarters is always a procedure to be taken into account when we are closing a quarter, but taking into account Ruling 1443/2013/00/00 of 22 September 2015, other possible courses of action are opened up so as not to lose said VAT.

Once again, we at MDG are at your disposal to offer advice on the mechanism for recovering VAT credit.

Leticia Cayuela Mayor.

News on the 2024 income tax return

Once again, the tax return campaign for the year 2024 is approaching. This year the filing period runs from 2 April to 30 June, which means that taxpayers will have practically 3 full months to prepare their tax return with dedication. Remember that the deadline for direct debit of the income tax payment is 25 June, so it is this final date that should be considered if the result of the tax return is to be paid in. 

With the publication in the BOE (Order HAC/242/2025, of 13 March) of the definitive form to be filed, and with access to the tax data for the 2024 tax year, we are able to report on the main new features that will undoubtedly affect many taxpayers: 

  • Obligation to file for the self-employed and beneficiaries of unemployment benefits.

From 2024, all self-employed workers who have been registered in the Special Regime for Self-Employed Workers (RETA) at any time of the year will be obliged to file a tax return, regardless of the income obtained. Likewise, recipients of unemployment benefits will also have to file their personal income tax return.

  • New limit on the obligation to file a tax return for workers with two or more payers. 

The limit excluding the obligation to file a tax return in cases where income from work is obtained from two or more payers is now €15,876. 

  • Modification of deductions for renting a home.

The Law on the Right to Housing, passed in May 2023, introduced changes to the deductions for renting in the IRPF from 1 January 2024. The general deduction for renting residential property was reduced from 60% to 50% of net income for contracts signed after 26 May 2023. However, for contracts in areas declared as stressed, if the landlord reduces the rental price by 5% compared to the previous rent, he can benefit from a deduction of up to 90%. 

  • Increase in the deduction for donations. 

As a new feature, for the 2024 tax year, the deduction base to which the 80% deduction applies has been increased (from the original 150 to 250 euros) and for the rest of the base, the deduction has been increased by 5 percentage points, from 35% to 40%. 

  • Extension of the deduction for energy efficiency improvement works. 

For the financial year 2024, this deduction may still be applied to amounts paid between 6 October 2021 and 31 December 2024.

  • Maintenance of the deduction for the acquisition of plug-in electric and fuel cell vehicles and recharging points. 

As in the previous section, this deduction has been maintained for the year 2024.

  • Implementation of the self-assessment rectification. 

Article 67 bis of the Personal Income Tax Regulations establishes the self-assessment rectification as the general way to modify a return already filed, leaving behind the previous system whereby supplementary returns or requests for rectifications were filed. 

  • Payment by credit card or bizum. 

Along with the traditional means, such as direct debit, there has been a commitment to updating the means of payment and payment by credit card is now permitted, under secure e-commerce conditions, or via Bizum.


From MDG Advisors, once again we are at your disposal for the preparation and filing of your tax return. 


Marina Guerrero Castronuño


The Power of Innovation in Spain: Tax Deductions for R&D

In Spain, companies that develop research, development, and innovation (R&D) projects can access
significant tax incentives. These benefits are designed to reward companies that invest in innovation, as
mentioned by Pablo Mallo in his Tax Pill from last February, where he explains how to take advantage of
these incentives according to current legislation.

Reduction in Social Security Contributions

One of the main advantages for companies involved in R&D projects is the reduction of up to 40% in
Social Security contributions for employees working on these projects. This incentive alleviates labor
costs and makes it easier for companies to strengthen their research and development teams.

Tax Deduction on Corporate Tax

In addition to the reduction in Social Security contributions, companies are entitled to deduct up to 42%
of expenses related to R&D in Corporate Tax. This deduction applies to expenses related to research,
development, and technological innovation, including salaries, materials, equipment, and other
necessary expenses to carry out these projects.
Spanish legislation establishes that companies investing in R&D can deduct a percentage of their
expenses. For research and development expenses, the deduction is 25%, with a possible increase to
42% if a certain threshold of investment in previous years is exceeded. An additional 17% deduction is
also available for expenses related to personnel exclusively assigned to R&D activities.

Applicable Legislation

The R&D deduction is primarily regulated in Article 35 of the Corporate Tax Law, which establishes the
conditions and applicable percentages for research, development, and technological innovation activities.
This law defines the activities that fall within the scope of R&D and sets the limits and criteria for
accessing the deductions.
In addition to the LIS, the Corporate Tax Regulation also plays a crucial role in the practical application of
these deductions. The regulation details how expenses should be presented, the conditions for an
activity to be considered as research or development, and the procedures for applying for tax benefits.
It is important to note that to apply for the R&D deduction, companies must meet certain formal
requirements, such as submitting a favorable report from the Ministry of Economy and Competitiveness.
This report certifies that the activities carried out are indeed research, development, or technological
innovation and not activities outside the scope of the deduction, such as industrial production or the
distribution of goods and services.

Who Can Apply for the R&D Deduction?

The deduction is available to all Corporate Tax taxpayers who carry out research, development, and
technological innovation activities. This includes commercial entities, civil societies with a commercial
purpose, foundations, associations, temporary business unions, among others. Even investment entities
such as pension funds or venture capital funds can access these deductions if they meet the legal
requirements.

Conclusion

Companies involved in R&D projects in Spain can benefit from significant tax incentives, such as
reductions in Social Security contributions and tax deductions in Corporate Tax. These benefits are
designed to encourage investment in innovation and allow companies to continue developing new
products, services, and processes that enhance their competitiveness.
To access these deductions, it is essential to meet the requirements set out in the Corporate Tax Law
and its development regulation. Companies must ensure that the activities they carry out fit within the
legal criteria for R&D and, if in doubt, seek advice from an expert in the field.
For any inquiries, please don’t hesitate to contact MDG Advisors. We will be happy to assist you
in optimizing your access to these tax benefits.

Sandra Gámez Chaves

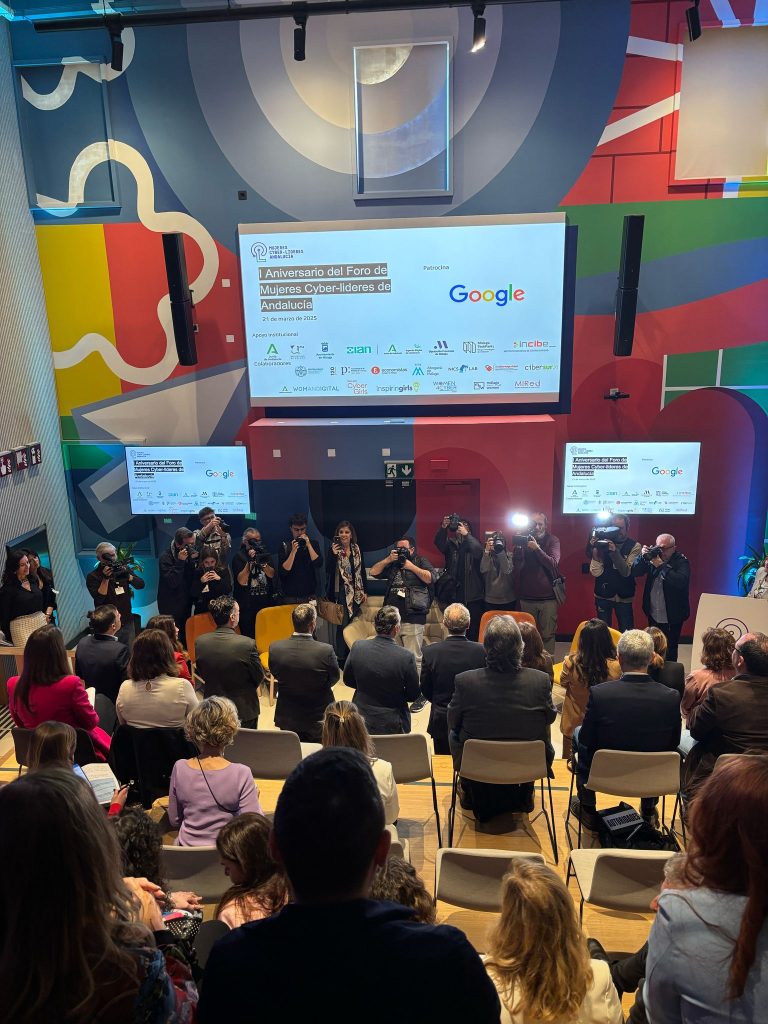
MDG present at the First Anniversary of the Andalusian Cyber-Leader Women’s Forum

Today, MDG has been present at the I Anniversary of the Andalusian Cyber-Leader Women’s Forum, a key event for the promotion of female leadership in the field of cybersecurity and technology. From the Google offices, we have shared experiences, knowledge and our commitment to innovation and inclusion in the digital sector.

At MDG, we believe in the transformative power of technology and the importance of fostering spaces where women leaders can continue to grow and make a difference. We will continue to support initiatives that promote diversity and talent in the digital era.

#MDG #Cybersecurity #FemaleLeadership #Innovation #WomenCyberForum.

Is the Public Treasury becoming more aggressive? Recent trends in inspections

In recent years, society has perceived a tightening of the Spanish Public Treasury’s collection policies. This change stems, in part, from the government’s need to balance public accounts following the economic challenges posed by the pandemic and the energy crisis.

One of the most notable trends in tax inspections is the use of big data tools and artificial intelligence to identify potential tax irregularities. These technologies allow the Tax Agency to detect behavioral patterns that might indicate fraud, leading to increased efficiency in inspections.

Additionally, there has been a greater focus on taxpayers showing external signs of wealth that don’t align with their tax declarations. These inspections aim to identify cases where a person’s lifestyle does not correspond to their declared income and assets, such as high-value homes, luxury cars, trips, or stays at exclusive locations.

To this end, social media platforms like Instagram have started to be monitored—an innovative approach that is helping to detect discrepancies and potential cases of tax fraud, leveraging the unintended transparency social networks generate.

Moreover, there has been intensified scrutiny over transactions carried out via Bizum, with the goal of ensuring that these electronic transfers are not used to conceal undeclared income or facilitate operations outside the fiscal radar.

Adapt or perish is not just a challenge for private companies, but also for public institutions, and the Public Treasury is no exception. Therefore, it may not be about a more aggressive Public Treasury, but rather about an institution trying to adapt to a constantly changing environment.

Isabel María Díaz Rubio


MDG ADVISORS and Fuengirola Fencing Club: A partnership for sport and Spanish heritage

At MDG ADVISORS, we are deeply proud of our partnership with the Fuengirola Fencing Club. This partnership represents much more than just a sponsorship; it is a commitment to sport, culture and support for our community.

Our connection with the club is further strengthened by our partner, Miriem Diouri Garcia, a former fencer whose passion for the sport inspires us. For us, it is a true honor to be able to support a minority sport with such deep roots in Spanish history, and especially to support the club where Miriem cultivated her love for fencing for more than 20 years.

Did you know that fencing is the only Olympic sport with Spanish origins? The Spanish school of fencing, developed in the 15th and 16th centuries, laid the foundations for the modern techniques practiced today. From duels of honor to the Olympic stage, fencing remains a sport that demands strategy, speed and precision, qualities that we also value at MDG ADVISORS.

At MDG ADVISORS, we strive to reflect these same values in everything we do. Like fencing, we pursue excellence through strategy, agility and precision. We are proud to celebrate 15 years of trajectory, always in constant pursuit of excellence, as evidenced by our motto.

Fuengirola Fencing Club not only promotes the practice of this noble sport, but also preserves a valuable cultural heritage. We invite everyone to visit their website and social networks to discover more about their activities and how you can join this exciting community.

At MDG ADVISORS, we believe in the power of sport to transform lives and strengthen communities. Our partnership with the Fuengirola Fencing Club is a testament to our commitment to these values.

Artificial Intelligence and taxation: Transforming tax management in companies.

Artificial intelligence (AI) is revolutionising many sectors and taxation is no exception. Companies,
large and small, are beginning to take advantage of the capabilities of AI to transform the way they
manage their taxes. This evolution not only improves efficiency and accuracy, but also forces
professionals in the tax sector to adapt to new tools and methodologies. The impact of AI on taxation
is so profound that it is redefining the traditional tasks of white-collar professionals in the tax field.
Corporate tax administration has traditionally been a complex and laborious task: it requires careful
monitoring of income, expenses and the various tax regulations that can vary by region or type of
business. With the integration of AI into these processes, companies can automate much of the data
collection and analysis, enabling them to quickly detect inconsistencies or areas for improvement. AI
systems can process huge amounts of data in real time, reducing human error and allowing tax
teams to focus on more strategic tasks.
One of the most prominent applications of AI in taxation is the automation of tax return preparation.
Through the use of advanced algorithms, systems can automatically compare company transactions
with tax regulations, ensuring that all legal requirements are met. This not only optimises time, but
also reduces the risk of penalties for errors in tax returns. In addition, AI can offer recommendations
on how to optimise the tax burden, based on historical patterns and changes in tax policies,
providing a competitive advantage.
For this reason, the transition towards an increasingly digitalised and AI-based tax environment
requires companies to adapt quickly to new technologies. Companies must invest in specialised
software that integrates artificial intelligence and provide training to their teams to make the most of
these tools. This adoption of AI not only optimises tax compliance, but also improves financial
planning and risk management.
In this context, companies must be aware of the importance of cybersecurity. The use of AI involves
the collection and processing of large volumes of sensitive data, which requires robust protection
systems. Thus, protection against cyberattacks is essential to ensure that tax and financial
information is secure, especially when cloud platforms are used to manage data and perform tax
processes.
In addition, AI solutions can facilitate regulatory compliance in an increasingly complex global
environment. Many companies operate in different jurisdictions, which means they need to comply
with a variety of tax laws. AI-based systems can help automate this process by analysing the tax
regulations of different countries and automatically adjusting to changes in local laws.
In turn, the impact of AI is not limited to companies as such, but is also transforming the tasks of
‘white collar’ professionals such as accountants, auditors and tax advisors. While these professions
have historically been focused on data analysis and decision-making, AI is making these processes
more efficient and, in some cases, automatable.
For example, accountants no longer need to spend as much time on manual data entry. Instead, they
can focus on more strategic tasks, such as analysing and interpreting the tax results generated by AI.
AI-based systems can quickly identify anomalies and patterns that might otherwise go unnoticed by
professionals, allowing them to focus on making informed decisions.

In addition, tax advisors also benefit from AI, as they can use it to offer personalised advice based on
a company’s data in real time. Thanks to predictive models and data analysis, tax advisors can
anticipate potential problems and propose solutions before they become major issues.
Although AI is revolutionising white-collar professions, it also raises the question of how it will affect
future employability. Some fear that automation will eliminate jobs, but the reality is that AI, rather
than replacing professionals, will allow them to focus on higher value-added tasks, such as strategy
and innovation.
In conclusion, artificial intelligence is changing the way companies manage their taxes, from
automating tax returns to improving operational efficiency. This transformation not only improves
tax compliance, but also offers new opportunities for financial planning and tax optimisation.
Professionals in the tax sector must adapt to this new reality, using AI to optimise their work and
focus on more strategic tasks. At the same time, companies must ensure that they implement the
right tools and adopt security measures to take full advantage of the benefits that AI offers in tax
management. AI is not only transforming the tax sector, it is ushering in a new era of collaborative
work between humans and machines.
Jesús Raya Zamora.


The High Court of Justice of Madrid rules on the tacit acceptance of an inheritance and inheritance tax

On 14 October 2024, the High Court of Justice of Madrid (TSJM) issued a key ruling on inheritance tax. It analysed whether a person who initially rejected an inheritance should be considered an heir for tax purposes due to certain acts that could be interpreted as tacit acceptance of the inheritance.

The case: a repudiated inheritance and tax controversy

The case involved a taxpayer, Mrs Elvira, who formally rejected the inheritance from her sister who died in 2017. However, the Community of Madrid considered that she had carried out acts that showed tacit acceptance of the inheritance, such as the use of funds from the deceased’s bank account and the omission of the inheritance tax.

Initially, the Regional Economic-Administrative Tribunal (TEAR) of Madrid had ruled in favour of the taxpayer and revoked the tax assessment imposed. However, the Community of Madrid challenged this decision before the TSJM, arguing that the facts showed that the taxpayer had implicitly accepted the inheritance.

The decision of the TSJM

The court analysed the facts and concluded that there was sufficient evidence to consider that the taxpayer had tacitly accepted the inheritance. Among the reasons given in the judgement, the following stand out:

  • The taxpayer was listed as authorised on the deceased’s bank accounts.
  • The funds in the accounts were withdrawn in full in the same year as the death.
  • Certain payments were made with the deceased’s money, which could be interpreted as asset management typical of an heir.

Based on the Inheritance and Gift Tax Act, the court determined that these acts implied a tacit acceptance of the inheritance and, therefore, the taxpayer was obliged to pay the corresponding tax.

Consequences and recommendations

Although the court upheld the tax assessment, it decided to revoke the penalty imposed, as the Community of Madrid did not adequately justify the taxpayer’s guilt.

This case highlights the importance of properly managing the renunciation of an inheritance. To avoid tax problems, it is essential to:

  1. Formalise the renunciation before a notary as soon as possible.
  2. Avoid any management or disposal of the deceased’s assets, as this can be interpreted as tacit acceptance.
  3. Consult a tax advisor to determine the tax impact and the best legal options in each case.

Our firm recommends that anyone in a similar situation seek specialised advice to avoid adverse tax interpretations. If in doubt, we are at your disposal to guide you through the process and ensure compliance with your tax obligations.

Sara Gámez Córdoba.