admin

Brexit: The end of the transitional period

BREXIT: THE END OF THE TRANSITIONAL PERIOD


Next 31st December 2020 the transitional period of Brexit will end. Even though there is a lot of uncertainty regarding the possibility of having a special tax agreement between UK and the EU, at present day, there is none and consequently, UK will be considered as a third country to all effects from 1stJanuary 2021.

Historically, there has always been a very strong trade relationship between UK and Spain, and therefore, it is important for Spanish companies to understand the new tax scenario and prepare for it. Furthermore, especially in Costa del Sol, there is a significant number of property owners with British nationality, who will have different tax treatments in comparison with the current situation.

COMPANIES

The main aspects that all entities should take into consideration are as follows:

  • Border taxes: import of goods from UK will be subject to customs duty. The Spanish Tax Authorities will not let any goods come in our country without paying the import taxes, in case it applies. Likewise, when sending goods to United Kingdom, the British Border Authorities will require their import taxes, in accordance with UK tax legislation.


  • VAT: when exchanging goods with the UK, we will be talking about imports or exports, instead of EU Operations. This implies a big difference: whilst currently no VAT is to be paid when buying/selling from/to UK, from 1st January 2021, the buying company will have to pay the VAT on the border of its country, in accordance with the VAT rates of such country, otherwise the goods will remain in the border.


  • British companies owning a property in Spain will be taxed at 24%, instead of the current 19%. This will increase significantly the tax quotas, not only for the tax rate increase of five points, but also because it will not be accepted to deduct any rental expense.

INDIVIDUALS

It is commonly known that a huge amount of British citizens own properties in Spain, either for personal use or for rental purposes. Brexit will increase their tax bills in Spain as indicated below:

  • Non Resident Taxes: EU citizens pay in Spain annually 19% of a deemed rent (2% of the cadastral value of the property, 1.1% if the cadastral value has been revised during the previous ten years). However, Non EU citizens should pay 24%.


When the property is used for rental purposes, EU citizens pay 19% of the rental profit, but Non EU citizens´ tax rate arises to 24%, with no deduction of expenses, which makes the tax quotas considerably greater for citizens outside the EU.


  • Wealth Tax: Non Residents in Spain with properties located in our country with a total value of Euros 700,000 (or above), are subject to Wealth Tax each year. EU citizens can decide whether they are taxed according to the national legislation or autonomic legislation. However, Non EU Citizens cannot do so. Most of the times, the national Wealth Tax legislation is more tax expensive than the autonomic ones and therefore, the British Wealth tax bills are likely to increase after Brexit.

There are other tax implications which could affect in other cases. Companies that normally operate with UK and British citizens owning properties in Spain should plan for the post-Brexit era, always following the advice of professionals.

At MDG we are at your entire disposal to help you with any doubt you may have.
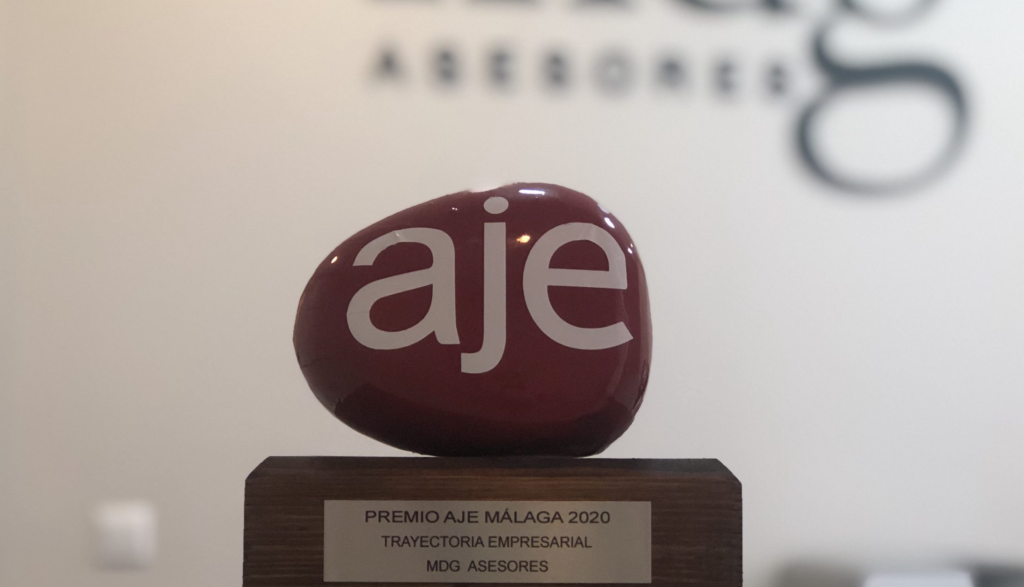
During the month of November, MDG will participate in the regional awards of AJE.

We are pleased to announce that on September 17th MDG Advisors received the Award for Best Business Trajectory 2020 from AJE. Among others, the jury included important personalities from the Malaga Town Hall, Technological Park of Malaga, Bic Euronova, University of Malaga, Junta de Andalucia and AJE Board of Directors.

MDG and the telecommuting challenge

At MDG we have adopted telecommuting as most things are adopted in life, with the urgency of a close deadline and where there was no room for procrastination. We had organised the remote system many months before but had hardly used it unless for the very extraordinary days we could not go to the office for medical reasons.

We started working from home overnight and were lucky to have all systems previously installed. Since the early beginning of our firm we were always concerned about adopting technology to our routines and investments in this field were done every year. It was our target for 2020 to become a digital firm, we could have never imagined a more radical launch.

But it is not just the technological structure that conditions a proper adaptation to telecommuting, it is also essential the cohesion and commitment of the team with the project. Working from home is a litmus test for the communication and productivity skills of any company.

After 4 weeks working from home, the balance so far could not be better, our levels of productivity haven`t been affected and the compromise of all the team, from managers to juniors has been remarkable. If there is something positive we get from the Covid-19 crisis, it is the record adaptation of our firm and the opportunity to confirm the level of engagement and commitment of the MDG team.

Publishment of the “real decreto” 9/2020 and 10/2020

From MDG, we would like to inform you about the principal measures taken in this regulation. However, we would like to inform you also that as from tomorrow, there will be more measures published and the ones we already have will be clarified. We are living a confusing time and little rigour in the regulation recently published, due to this unusual COVID-19 crisis, hence we recommend patient and caution.

These measures are the following ones:

1. Suspension of all economic activity NOT indispensable. You can access the list of these essential activities, at the following link: https://www.boe.es/buscar/doc.php?id=BOE-A-2020-4166

2. The new recoverable paid leave is adopted between March 30 and April 9. For those workers of the companies that have to suspend their activity because it is not essential, this permission is provided. Their salaries will continue to be paid , but the hours corresponding to that salary must be recovered after the State of Alarm is overcome. This is mandatory, even if it is called “permission”, and the hours will be gradually recovered. It does NOT apply to companies that can work remotely.

3. Dismissal for objective reasons is limited, in other words, force majeure and economic, technical, organizational causes … for the termination of contracts will not be considered as objective cause, therefore the dismissal will not be fair. The Government pretends to limit the extinctions of contracts, and to facilitate the suspensions of contracts.

4. Interruption of the calculation of duration in the suspension of temporary contracts. If the suspension of temporary employment contracts has been agreed, its computation will restart after the conclusion of the Alarm State.

5. Facilitation of the unemployment benefits for workers affected by ERTES. The application for unemployment benefits will be made collectively by the employer, and not by each worker individually.

6. The ERTES requested on the occasion of COVID-19, both those based on force majeure and objective causes, will only last as long as the Alarm State is maintained.

7. Warning to companies that, if they act in fraud of law or with falsification of data, both in ERTES and in the reception of any benefit, will be sanctioned accordingly, as well as the Government remark that necessary measures will be taken to review and control that such actions do not occur.

Devengo iva con aplazamiento en el pago de rentas

Estamos recibiendo la consulta recurrente de qué ocurre con el IVA en aquellos casos en los que se acuerda un aplazamiento o moratoria en el pago de rentas y a través de este post queremos dar claridad a las opciones fiscales disponibles:
El artículo 75.Uno.7º de la Ley 37/1992, del IVA, en adelante LIVA, establece que se produce el devengo:

“En los arrendamientos, en los suministros y, en general, en las operaciones de tracto sucesivo o continuado, en el momento en que resulte exigible la parte del precio que comprenda cada percepción.

No obstante, cuando no se haya pactado precio o cuando, habiéndose pactado, no se haya determinado el momento de su exigibilidad, o la misma se haya establecido con una periodicidad superior a un año natural, el devengo del Impuesto se producirá a 31 de diciembre de cada año por la parte proporcional correspondiente al periodo transcurrido desde el inicio de la operación, o desde el anterior devengo, hasta la citada fecha”.

De acuerdo con la doctrina del TEAC (Resoluciones de 30 de junio y de 27 de octubre de 1993) y la jurisprudencia del TS (S de 6 de noviembre de 2006, rec. 5933/2001, que ratifica la Resolución del TEAC de 29 de mayo de 1998), puede indicarse:
– En los contratos de arrendamientos y de tracto sucesivo, el devengo tiene lugar cuando sea exigible la parte del precio que comprenda cada percepción, sin que exista base jurídica para compensar en la autoliquidación las cantidades correspondientes a clientes que estime de dudoso cobro.
– En tanto no exista resolución contractual por impago de las rentas pactadas (por sentencia judicial) se siguen devengando las cuotas correspondientes. Solo a partir del momento en que el contrato quede resuelto y no antes, el impuesto dejará de devengarse.
– Todo ello, sin perjuicio de que, cuando se den las condiciones previstas en el artículo 80.tres y cuatro de la Ley del IVA ( concurso o crédito incobrable), pueda modificarse la base imponible de las operaciones.

MDG goes digital

We are happy to announce that we have taken a new step on the digital transformation of our procedures: we are already in the cloud and we are proud of it!

At MDG we have always been very focused on walking alongside technology, as we trust on the new IT era to ensure smooth communications with our clients, as well as to increase our professional performance. The implementation of this system enables our clients to access and monitor the accounts of their entities in live; anywhere; anytime.

Want to know more? Please get in touch.

MDG informative note after the publication of the “real decreto ley 8/2020”

Dear clients,

From Mdg Advisors, we would like to inform you about the new measures implemented by the Government, through the publication today of the regulation “Real Decreto-Ley 8/2020”, which may affect the self-employed/ freelance. 

First of all, we would like to inform you that we are awaiting the development of these regulations, as well as we are waiting for new measures to be adopted by the Government in these weeks, so we advise caution and you have our entire disposal to help you in this time of uncertainty. Self-employed associations are also working to try to get further actions on this in the Cabinet (“Consejo de Ministros”) next week.

Thus, we inform you that the main measure adopted in this “Decreto” for freelancers has been the regulation of the extraordinary benefit for cessation of activity (“Prestación extraordinaria por cese de actividad“), a benefit that the self-employed may apply that implies the payment of this benefit and the exoneration of the payments of the Social Security fees, if requirements are met. If not, there is no suspension of the payment of the fees and no benefit.

The main notes if this measure are the following:

Who can request this extraordinary benefit for cessation of activity?

– The self-employed whose activities are suspended due to the regulation of the “Real Decreto 463/2020, de 14 de Marzo, de declaración del Estado de Alarma” (Declaration of the State of Alarm). In other words, if you are among the sectors covered by this “Decreto” and you have had to close your business, you can apply for this benefit. Please find in the following link these sectors, in the annex at the end of the text: https://www.boe.es/buscar/doc.php?id=BOE-A-2020-3692

– The self-employed whose billing in the month prior to the application of the benefit is reduced by at least 75% in relation to the average billing of the previous semester. In other words, if this benefit is requested in April, the billing of the month of March should be compared with the billing of the previous semester, to determine if the billing has been reduced by 75%.

What requirements must be fulfilled?

– Be affiliated and registered, on the date of the declaration of the State of Alarm (March 14), in the Special  Regimen of Social Security for Self-Employed Workers (RETA).

–  In the event that the business activity is not directly suspended due to the regulation in the “Real Decreto 463/2020, de 14 de marzo”, it has to be proved that the billing is reduced at least by 75%, in relation to the billing in the previous semester.

– Be up-to-date in the payment of the Social Security fees. However, if it is not, this situation of non payment can be regularised by paying the outstanding fees due within 30 days.

What is the amount of the benefit?

– In general, the amount will be 70% of the regulatory base (“base reguladora”).

– In the event that the minimum contribution period (“período mínimo de cotización”) is not accredited, the amount will be 70% of the minimum contribution base (“Base de cotización mínima”) in RETA.

What is the duration of this benefit?


– The duration is 1 month.

– In the event that the Alarm State is extended and its duration exceeds one month, it will be expandable until the last day of the month in which the Alarm State ends.

– During this time it will be understood as contribution time, and will not reduce the periods of benefit for cessation of activity to which the beneficiary may be entitled in the future.


To consider:


– This benefit is incompatible with any other Social Security benefits.

– The management of these benefits correspond to the mutual collaborators of the Social Security.

Apart from that, it should be take into account the possibility, regulated in this “Decreto”, of requesting a deferral on the mortgage payment of the main residence (vivienda habitual), not others, with some requirements, which may also be helpful.

Also, we would like to inform that the guarantee of water supply, energy and telecommunications, is applicable only for individuals that cannot eventually attend to the payment of those supplies, but this is not applicable  for companies, they have to pay their suppliers.


Finally, several credit benefits have been approved with public finance, that companies (PYMES) and self-employed may can apply for. We must wait for its further policy development in order to verify the requirements that will be established to access these grants.


Again, we remain at your entire disposal for any questions you may have.

Thank you for trusting in our firm.

Regards,

Brexit’s information

Today, 31th January, the UK leaves the European Union and we would like to inform you briefly in tax terms about it.


Finally the Brexit Agreement has been signed, but now begins a transition period until next 31th December 2020. During this transition period, EU laws will continue to be in force for british citizens, therefore, until 01st January 2021 it will be applicable the same tax conditions up to now, like the UK would be still a member of the European Union.


Should you need any further information, please find the following link https://www.agenciatributaria.es/AEAT.internet/Inicio/La_Agencia_Tributaria/Campanas/BREXIT/BREXIT.shtml . The Spanish Tax Agency has made its efforts to cover all the tax information the taxpayer may need to know in this site, so you will find all the main consequences, in tax terms, british residents have to concern about from 01st January 2021 onwards.


We remain at your entire disposal to help you with any doubt you may have

Fiscal measures of the new government

The deal arranged by PSOE and Unidas Podemos last 30th December has provoked an agreement that both parties have called “Coalición Progresista. Un nuevo acuerdo para España”. This agreement includes, amongst others, the partial abolishment of the labour reform approved back in 2012, increase of Minimum Wages and a series of fiscal measures.

The main points of this agreement from a tax point of view are:

1/ Fight against fraud. It is intended to update the list of tax haven territories, eliminate fiscal amnesties and promote fraud prevention through Tax Office lists of debtors. Regarding cash payments, the limits will be stricter.

2/ Increase of control of “SICAV”. New requirements will have to be met in order to apply the reduced tax rate for this kind of entities, ensuring its nature of collective investment instrument. To do so, it will be establish a maximum capital amount per investor (including participation of related parties).

3/ Corporation Tax. Big corporations will be taxed at a minimum of 15%, increasable until 18% for financial entities and hydrocarbon companies. Dividends and capital gains related to participation on other entities will be reduced by 5%, and qualified as non tax deductible expenses. Small and Medium size companies (“PYMES”) will be taxed at 23% instead of 25%, as long as their annual turnover does not exceed one million euros.

4/ Personal Income Tax ( IRPF). Tax payers with rents above 130,000 euros will see their tax rate increased around two %, and the part exceeding 300,000 euros will be increased by 4%. For financial earnings above 140,000 euros, national tax rate will be 27% instead of 23%.

5/ Special regime of “SOCIMIS” will be reformed, applying a tax rate of 15% on retained profits.

6/ VAT. There will be a tax rate reduction in female hygiene products and veterinary services.

7/ New government also wants to approve new taxes such as: Tax on certain digital services, applicable to operations that currently are not taxed in the digital economy; Financial transactions Tax and/or Tax to punish certain behaviours on environmental issues.


Regardless of this agreement, none of the above mentioned measures has been approved yet but the increase of Minimum wages.

Inheritance and donations from non-residents

For all those non-residents outside the European Union (EU) and the European Economic Area (EEA) who paid the Tax on Inheritance and Donations years ago, the decision made by the Spanish Supreme Court on February 19 has been good news. The Spanish Supreme Court finally ruled that Spanish internal regulations discriminates non-residents in relation to Inheritance and Donations Tax, and therefore this regulation was null and void. According to this sentence (STS 550/2018), non-residents in the EU and EEA should be subject to the rules of the Autonomous Communities when paying this tax, and not the state regulations as has been done until now, which was less beneficial. Thus, discriminatory treatment was granted to non-residents in the EU and the EEA by applying regulations that harmed them, which is contrary to Community law, and therefore null and void.

But this situation already raised controversies in the past. In principle, when a non-resident in Spanish territory received a donation or inheritance in Spain, the state regulations were applied instead of autonomic ones, which in most cases contain tax advantages when paying this tax, such as deductions or bonuses, which state regulations do not include. Therefore, the fact of being non-resident turned out in a higher tax liability than in the case of residents, giving rise to a different treatment for the mere objective fact of the residence. This was contrary to European law, as it was discriminating against residents of the European Union and was violating the principle of free movement of capital in art. 63 of the TFEU (Treaty on the Functioning of the European Union), and the Court of Justice of the European Union concluded in its sentence of 3 September 2014 (Case C-127/12) that if European non-residents were taxpayers of the tax, the same rules should objectively be applied to them and, therefore, the regional rules should be applied.

Following this mandatory ruling, the Spanish internal regulation was modified by introducing the Second Additional Disposal in the text of the Inheritance and Donations Tax Law and correcting this situation, but instead of including all non-residents, only the modification was contemplated for residents in the European Union and the European Economic Area, once again establishing a situation of discrimination against residents in third countries. This disposal was already criticised at the time because the European legislation was once again being violated by establishing that the free movement of capital also applies to third countries.

Reaching the point of the publication of this Supreme Court judgement in 2018, it is finally concluded that third countries’ residents are also subject to the regulations of the autonomous communities in the settlement of Inheritance and Donations Tax, opening the way to possible challenges for those non-residents who paid a higher fee when settling the tax in accordance with state regulations.

How is it possible to make this claim?

For non-prescribed inheritance and donations tax settlements, a refund of the excess paid may be requested by submitting a Request for the refund of undue income to the corresponding Autonomous Community Tax Agency, in which it is alleged that the application of autonomic regulations are applicable instead of state regulations, when there are reasons for doing so. The specific case must be taken into account, that is to say, the Declaration (not prescribed) must be reviewed to verify whether or not applying the autonomic regulation, the resulting quota to be paid is lower than the original one, having the right therefore to the return of what has been unduly paid.

In the case of liquidations to be submitted now, the issue presents greater complications. The Spanish internal regulations have not yet been modified, eliminating this discrimination against residents of third countries. Therefore, if the liquidation is submitted by applying the autonomic regulations, even though we have the Supreme Court’s criterion in the ruling, we risk a rejection of this liquidation. Therefore, there are two possibilities: present the liquidation with the state regulations and, after that, challenge said declaration and request the refund of the unduly paid, or to take the risk and try to get the Autonomous Tax Agency to accept the liquidation with the application of the autonomic regulations.

We must add that there are already binding inquiries of the Directorate-General for Taxation (CV 3151-18 and CV 3193-18) in which it is estimated that effectively the Spanish legislation that governs Inheritance and Gift Tax is contrary to European regulations, since the principle of free movement of capital is violated, giving conformity to the criterion of the Supreme Court and, therefore, admitting that the autonomic regulations on this tax are also applicable to non-EU residents, thereby giving taxpayers greater expectations of success in tax declarations with the application of the appropriate legislation, that is, the autonomic one.