admin

What’s new in the draft law for a new tax reform.

oday, the new tax reform is being debated in Congress, which may bring with it important measures for taxpayers who are affected by it, in the event of its final approval in the Plenary.

Among the measures that have been debated in this tax reform, the following stand out:

a) Tax cuts for SMEs and micro-SMEs: Progressive rates will be established to reduce the taxation of companies, with a significant reduction in the coming years.

b) Increase in capital income: the taxation of savings income in personal income tax (IRPF) will be increased from 28% to 30%.

c) Tax relief for recapitalisations: Companies, both large and small, will be able to reduce their corporate income tax base depending on their recapitalisation. This relief may be up to 30% of the increase in equity if the company increases its workforce by 10%. The reduction could be up to 20% of the tax base, or 25% in the case of SMEs.

d) Reductions in corporate tax: progressive reduction in the tax rate for companies with a turnover of less than one million euros.

Other measures that have been debated during these days and that will have to await final approval are the tax on energy companies, the tax on banks and the tax on tourist rentals, among others.

At MDG Advisors we will keep a close eye on the latest developments in the tax reform project to find out which measures are finally approved and to analyse how they will affect the taxation of our clients and anyone else who requests it. Do not hesitate to contact our MDG Team for more information.

Jesús Raya Zamora.

The tax on large inheritances

For some days now, Congress has been debating the introduction of a new tax: the tax on large inheritances.

The party SUMAR has brought the debate to the table of the Congress, demanding the approval of this new tax as a fundamental requirement to give its support to the Government in the approval of the general budgets.

This new state tax would mean the harmonization of Inheritance and Gift Tax, forcing all inheritances and gifts over one million euros to be taxed, regardless of the relationship between the parties and the Autonomous Community of residence.

As already happened with the Wealth Tax and the Solidarity Tax for large fortunes, this new proposal is already generating a lot of commotion among taxpayers and deep controversy in the world of tax advice. For this reason, at MDG Advisors we will continue to report on the status of this tax proposal.

Pablo Mallo Bárcena

Countdown to comply with the new obligations on electronic invoicing – “VERIFACTU”··

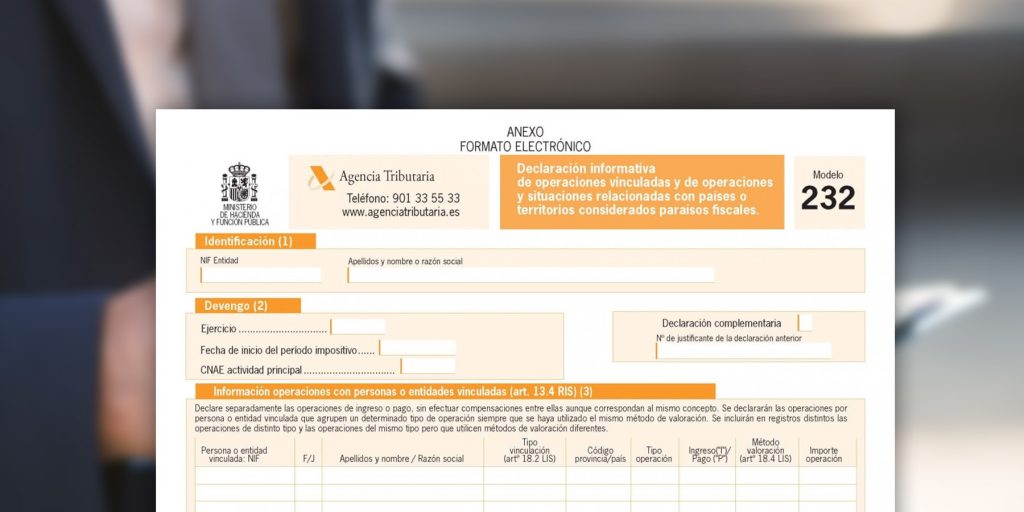
After finishing the third tax quarter and already with a view to complying with the census obligations that November brings with it with the Tax Agency and checking the obligations entailed by Form 232 – Informative declaration of related transactions and of transactions and situations related to countries or territories qualified as tax havens, we have had to stop with a new publication in the BOE, as the countdown to comply with the new obligations on electronic invoicing (known as Verifactu) has begun.

On October 28, 2024, Order HAC7/1177/2024, of October 17, 2024, was published in the BOE, developing the technical, functional and content specifications referred to in the Regulation that establishes the requirements to be adopted by the computer or electronic systems and programs that support the invoicing processes of businessmen and professionals, in force since October 29, 2024.

The publication of this Ministerial Order means the beginning of the computation of the maximum period of nine months in which manufacturers and marketers of invoicing systems for businessmen and professionals must market products adapted to the regulation, so this period will end on July 29, 2025.

However, it is expected that the deadline will be delayed until January 1, 2026 for corporate taxpayers and July 1, 2026 for individuals with economic activity, according to the proposed amendment of the Verifactu Regulation that has been published in the prior public consultation process, but as it is not a final text, it may undergo modifications until its official publication.

The most important objectives of this Ministerial Order are:

  • To reinforce the obligation to issue invoices for all transactions carried out by businessmen and professionals.
  • To ensure that all transactions are recorded in the computer system in a secure, non- manipulable, accessible manner and with a standard structure and format to facilitate the legibility of the records, the automated analysis and the simultaneous submission to the Tax Administration.
  • Facilitate compliance with tax obligations.

It should be noted that this obligation to exchange invoices automatically with the Treasury affects companies with a turnover of less than 6 million euros, since those that exceed that figure are already obliged to send the information to the Treasury through the SII since the 2017 financial year.

From our firm we will take care of updating this information so that our clients can properly comply with the deadlines involved in the well-known Verifactu.

Leticia Cayuela Mayor

Whats new in the IRPF 2025 Campaign Payment: Acceptance of Bank Card and Bizum You are here:

The Income Tax Declaration Campaign (IRPF) is a crucial time for taxpayers in Spain, and in 2025 this process will be modernised with the introduction of new payment methods. From this year, taxpayers will be able to pay their taxes by bank card and Bizum, which promises to make the process more convenient and efficient. This important development was announced by Soledad Fernández, Director General of the Tax Agency, during the opening of the XXXIV Congress of State Tax Inspectors. Although the exact date of entry into force of this measure has not yet been
confirmed, the Tax Agency is working to have it operational for the next income tax campaign.

Historically, personal income tax payments were mainly made by direct debit or bank transfer, methods that can be cumbersome and require several steps. By accepting card payments and Bizum, the Tax Agency aims to simplify the process and allow citizens to make their payments instantly and securely from their mobile devices, responding to the demands of an increasingly digitalised society looking for practical and efficient solutions to manage their finances. With these improvements, the Tax Agency is not only facilitating tax compliance, but also promoting a more fluid and accessible relationship between the state and citizens.

The inclusion of payment methods such as bank card and Bizum in the IRPF 2025 campaign represents a significant step forward in the modernisation of tax administration in Spain. This initiative will not only make the filing process more accessible, but also reflects a commitment to innovation and adaptation to taxpayers; needs.

We look forward to hearing more about this exciting new development.

Carmen Moya López

Registration of properties in the land registry

In the Spanish registry system, the concept of "inmatriculación" refers to the process through which a property that has not previously been registered in the Land Registry is recorded for the first time. This process, governed by the Mortgage Law, is essential for providing legal certainty to property ownership. The recent amendment to this law, which came into effect in May 2024, establishes that the Land Registry will be managed electronically, using the "real folio" system, where the property is the fundamental element.

The first registration of a property in the registry can be done through various means. One method is the domain proceeding (Article 203 of the Mortgage Law), which is processed before a notary and requires the presentation of the title deed, the cadastral certification, and other documents that prove the absence of prior registration. The registrar reviews the documentation, and if there are no conflicts with other properties, the registration proceeds.

Another method is registration by double title (Article 205), which requires the submission of two public deeds proving the ownership of the property, with at least one year between them.The property description must be consistent between both deeds and match the updated cadastral certification.

Additionally, the Mortgage Law allows for registration through an administrative certification (Article 206), reserved for public administrations, or through administrative documents in specific procedures (Article 204), such as cases of forced expropriation or land consolidation.

It is important to note that the protection of public property is also reinforced in this process, requiring that the graphical representation of the property be coordinated with the Cadastre, which helps to prevent issues such as double registration. In exceptional cases, an alternative
graphical representation is allowed when it does not exactly match the cadastral certification.

Finally, the effects of the public registry's legal protection do not apply immediately, as at least two years must pass from the property's registration for third-party buyers to benefit from this protection, as stipulated in Article 207 of the Mortgage Law.

This legal framework aims to provide greater transparency and legal certainty to the process of property registration in Spain, ensuring the proper identification and protection of both public domain and private properties.


Sandra Gámez Chaves

Form 232: information return on related-party transactions and other situations to be taken into account. You are here:

After the third quarter of the financial year and during the month of November of each year, there is an obligation to report certain information to the Tax Agency about the company’s activity during the previous financial year. We are talking about Form 232.

What is Form 232?

Form 232 is an information return that is reported electronically to the Tax Agency when the requirements established for this purpose are met in relation to related-party transactions and/or transactions with tax havens (now called non-cooperative jurisdictions).

Who is obliged to file it?

Those corporate income taxpayers who carry out transactions with related persons or entities under the terms set out in article 18.2 of Law 27/2014 on Corporate Income Tax (LIS) and who exceed certain economic thresholds established in the regulations in force, both in a specific transaction and as a whole and without taking VAT into account, are obliged to file Form 232 and complete the ‘Information on transactions with related persons or entities (art.13.4 RIS)’.

What is the deadline for filing?

It will be filed in the month following the ten months after the end of the tax period to which the information to be supplied refers. Therefore, as a general rule, in the case of taxpayers whose tax year coincides with the calendar year, the deadline for filing the return is from 1 to 30 November.

What is a related-party transaction?

A related-party transaction in corporate income tax refers to those transactions carried out between entities or individuals that are connected in some way, either because they belong to the same business group, are shareholders of the same company, or have other significant ties. Specifically, they are those parties set out in article 18.2 of the LIS.

In conclusion, Form 232 is a compulsory information return with the aim of obtaining greater tax transparency. Failure to file it may be subject to a penalty, as well as failure to justify the elements required in the return itself. Therefore, it is essential to maintain an optimal assistance in this matter, so, for further information, do not hesitate to contact MDG Advisors.

Jesús Raya Zamora.

New TEAC criteria – Calculation of the exemption for income from work abroad (article 7.p LIRPF).

It is true that once the summer holidays were over, it was time to get down to work with the third quarter taxes, but there has been a new TEAC resolution that gives taxpayers a hand, and we consider it convenient to take a few minutes away from the third quarter taxes to keep you informed, as it has a considerable economic impact on the taxpayer’s personal income tax.

The Central Economic Administrative Court (TEAC) has agreed in its recent Resolution, number 8685/2023 of 19 July 2024, to unify criteria regarding the calculation of the exemption contained in article 7.p) LIRPF (work carried out abroad).

To put ourselves in context, let us recall that article 7 p) of the Personal Income Tax Act establishes that ‘the exemption shall apply to the remuneration earned during the days spent abroad, with a maximum limit of 60,100 euros per year’, and to find out how to calculate this exemption, we had to go to article 6 of the Personal Income Tax Regulations:

“The exemption shall have a maximum limit of 60,100 euros per year. For the calculation of the remuneration corresponding to work carried out abroad, the days that the worker has actually been abroad must be taken into consideration, as well as the specific remuneration corresponding to the services rendered abroad.

In order to calculate the amount of income accrued each day for work carried out abroad, apart from the specific remuneration corresponding to the aforementioned work, a proportional distribution criterion shall be applied, taking into account the total number of days in the year’.

And we always wondered, what would happen to taxpayers who had travelled abroad for less than the duration of the calendar year, would they also have to make the proportional distribution to calculate the exemption taking into account the TOTAL number of days in the year?

Yes, and let us not forget that this has been the criterion used by the Directorate General of Taxes in many rulings issued to taxpayers, which clearly disadvantages taxpayers who have travelled abroad with an employment contract for a fixed period of less than one calendar year.

And this is precisely the criterion addressed in resolution 8685/2023 of 19 July 2024 of the TEAC.

The TEAC concludes that only in cases where the employment relationship has covered the entire financial year should the content of article 6.2 of the RIRPF be applied without exception, with the consequent division between the 365 days.

However, when the employment relationship extends over a period of less than one calendar year, the amount of non-specific earned income accrued during the days spent abroad must be calculated using the number of days corresponding to the duration of the employment contract in the calendar year in the denominator.

Once this change of interpretation has been analysed, the Personal Income Tax of taxpayers in 2024 can be calculated on the basis of this new criterion adopted by the TEAC, but there will be many self-assessments of Personal Income Tax filed in previous years that will require review in order to rectify them and request a refund of undue income, since the exemption applied at the time was less than that permitted on the basis of this new criterion adopted by the TEAC.

Therefore, MDG Advisors is at your disposal to answer any questions you may have in this regard, to provide you with the best advice on this change of criteria in the IRPF.

Leticia Cayuela Mayor.
Consideration as a large company

Do you consider yourself to be a large company? According to the criteria of the Tax Agency, a large company is one that has achieved a turnover of more than 6,010,121.04 Euros in one year.

This consideration gives rise to a series of census and tax changes from the following year onwards:

– Notification to the Tax Agency of the status of Large Company through census form 036.
– Monthly submission not only of VAT self-assessments, but also of withholdings and payments on account, Electricity Tax and Tax on Alcohol and Beverages.
– Preparation of record books through the electronic supply of invoicing records (SII).

– Obligation to calculate corporate income tax instalments in accordance with Article 40.3 of the Corporate Income Tax Act.

It is important each year to review whether these requirements are met, not only to report that this volume of transactions has been exceeded, but also to report that, even though this requirement has been exceeded previously, it has ceased to be met. In other words, if the turnover for a financial year is less than 6,010,121.04 Euros, it would also be necessary to report the loss of status as a Large Company, with the consequent change in the frequency of the self-assessments to be filed.

Given that we are about to start the last quarter of the year, if you think you are going to exceed this threshold, and you have any doubts about how to notify the authorities, we are at your disposal.

Isabel María Díaz Rubio.

Main Features of the Parity Law

The new Organic Law 2/2024, of August 1, 2024, on equal representation and balanced presence of women and men, published in the BOE on August 2, 2024 and coming into force on August 22, 2024, is based on the equality before the law of all citizens as set forth in the first article of the Spanish Constitution. In the same field, it is worth mentioning the Resolution of the United Nations General Assembly, which presents the balanced participation of at least forty percent of each sex in representative and decision-making positions as a parity threshold to eliminate bias in decision-making.

As a point of origin of the progress made by this new legislation focused on achieving equality in political and economic decision-making, we can place the Organic Law 3/2007, of March 22, which focuses on eradicating inequality so that the presence of men and women as a whole does not exceed sixty percent and is not less than forty percent.

This new text is intended to break glass ceilings and ensure that women are represented fairly and equally at all decision-making levels, as required by the Constitution and the European Union.

From this provision it is worth highlighting as a priority the already mentioned balanced presence of men and women, without exceeding sixty percent or being less than forty percent, both in higher and executive bodies of the General State Administration and in entities of the State institutional public sector, bringing with it several changes, among which we can highlight the Constitutional Court, the Council of State or the Court of Auditors.

Specifically, it sets out this balance in decision-making bodies such as boards of directors, constitutional bodies and management teams.

But it does not only stop there, it covers new sectors and areas such as sports, public procurement, foundations or the tertiary sector, modifying the Sports Law, the Public Sector Contracts Law and the Organic Law of the University System.

In terms of its impact, it directly affects companies, especially listed companies, which must ensure that at least 40% of the members of their boards of directors are women. Nor should they forget that minimum percentage in senior management positions.

On the other hand, transparency must not be left aside, since in the event of female representation exceeding sixty percent, this deviation must be justified in writing.

This new law presents a challenge and an opportunity for both companies and organizations. Those that best adapt to the new requirements will see this reflected in greater competitiveness and long-term sustainability. To do so, they will have to correctly apply this regulation by revising their selection, promotion and professional development policies to ensure that they can meet the new requirements.

Translated with DeepL.com (free version)

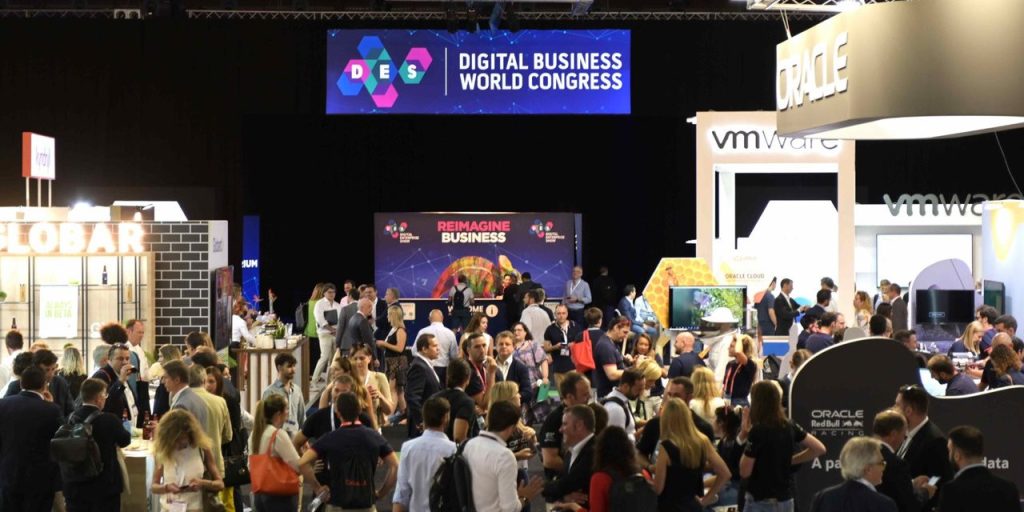
MDG Advisors attends the Digital Business World Congress in Malaga

Our partner Miriem Diouri on behalf of MDG Advisors attended the Digital Business World Congress, the most relevant congress in Europe on exponential technologies and business growth with digital strategies. From 11-13 June at FYCMA, this event brought together more than 450 international speakers, global influencers and authorities who discussed new business models, disruptive innovations and leadership strategies.

During our participation, we explored the latest developments in artificial intelligence and technology presented at the fair. With 250 hours of content, DBWC offered deep insights into the impact of technology in key sectors such as banking, retail, life sciences and smart cities, as well as transformative technologies such as AI, Blockchain, VR/AR, Metaverse, MultiCloud, IoT, Cybersecurity and Big Data.

We take away valuable insights and knowledge to implement in our digital strategies!