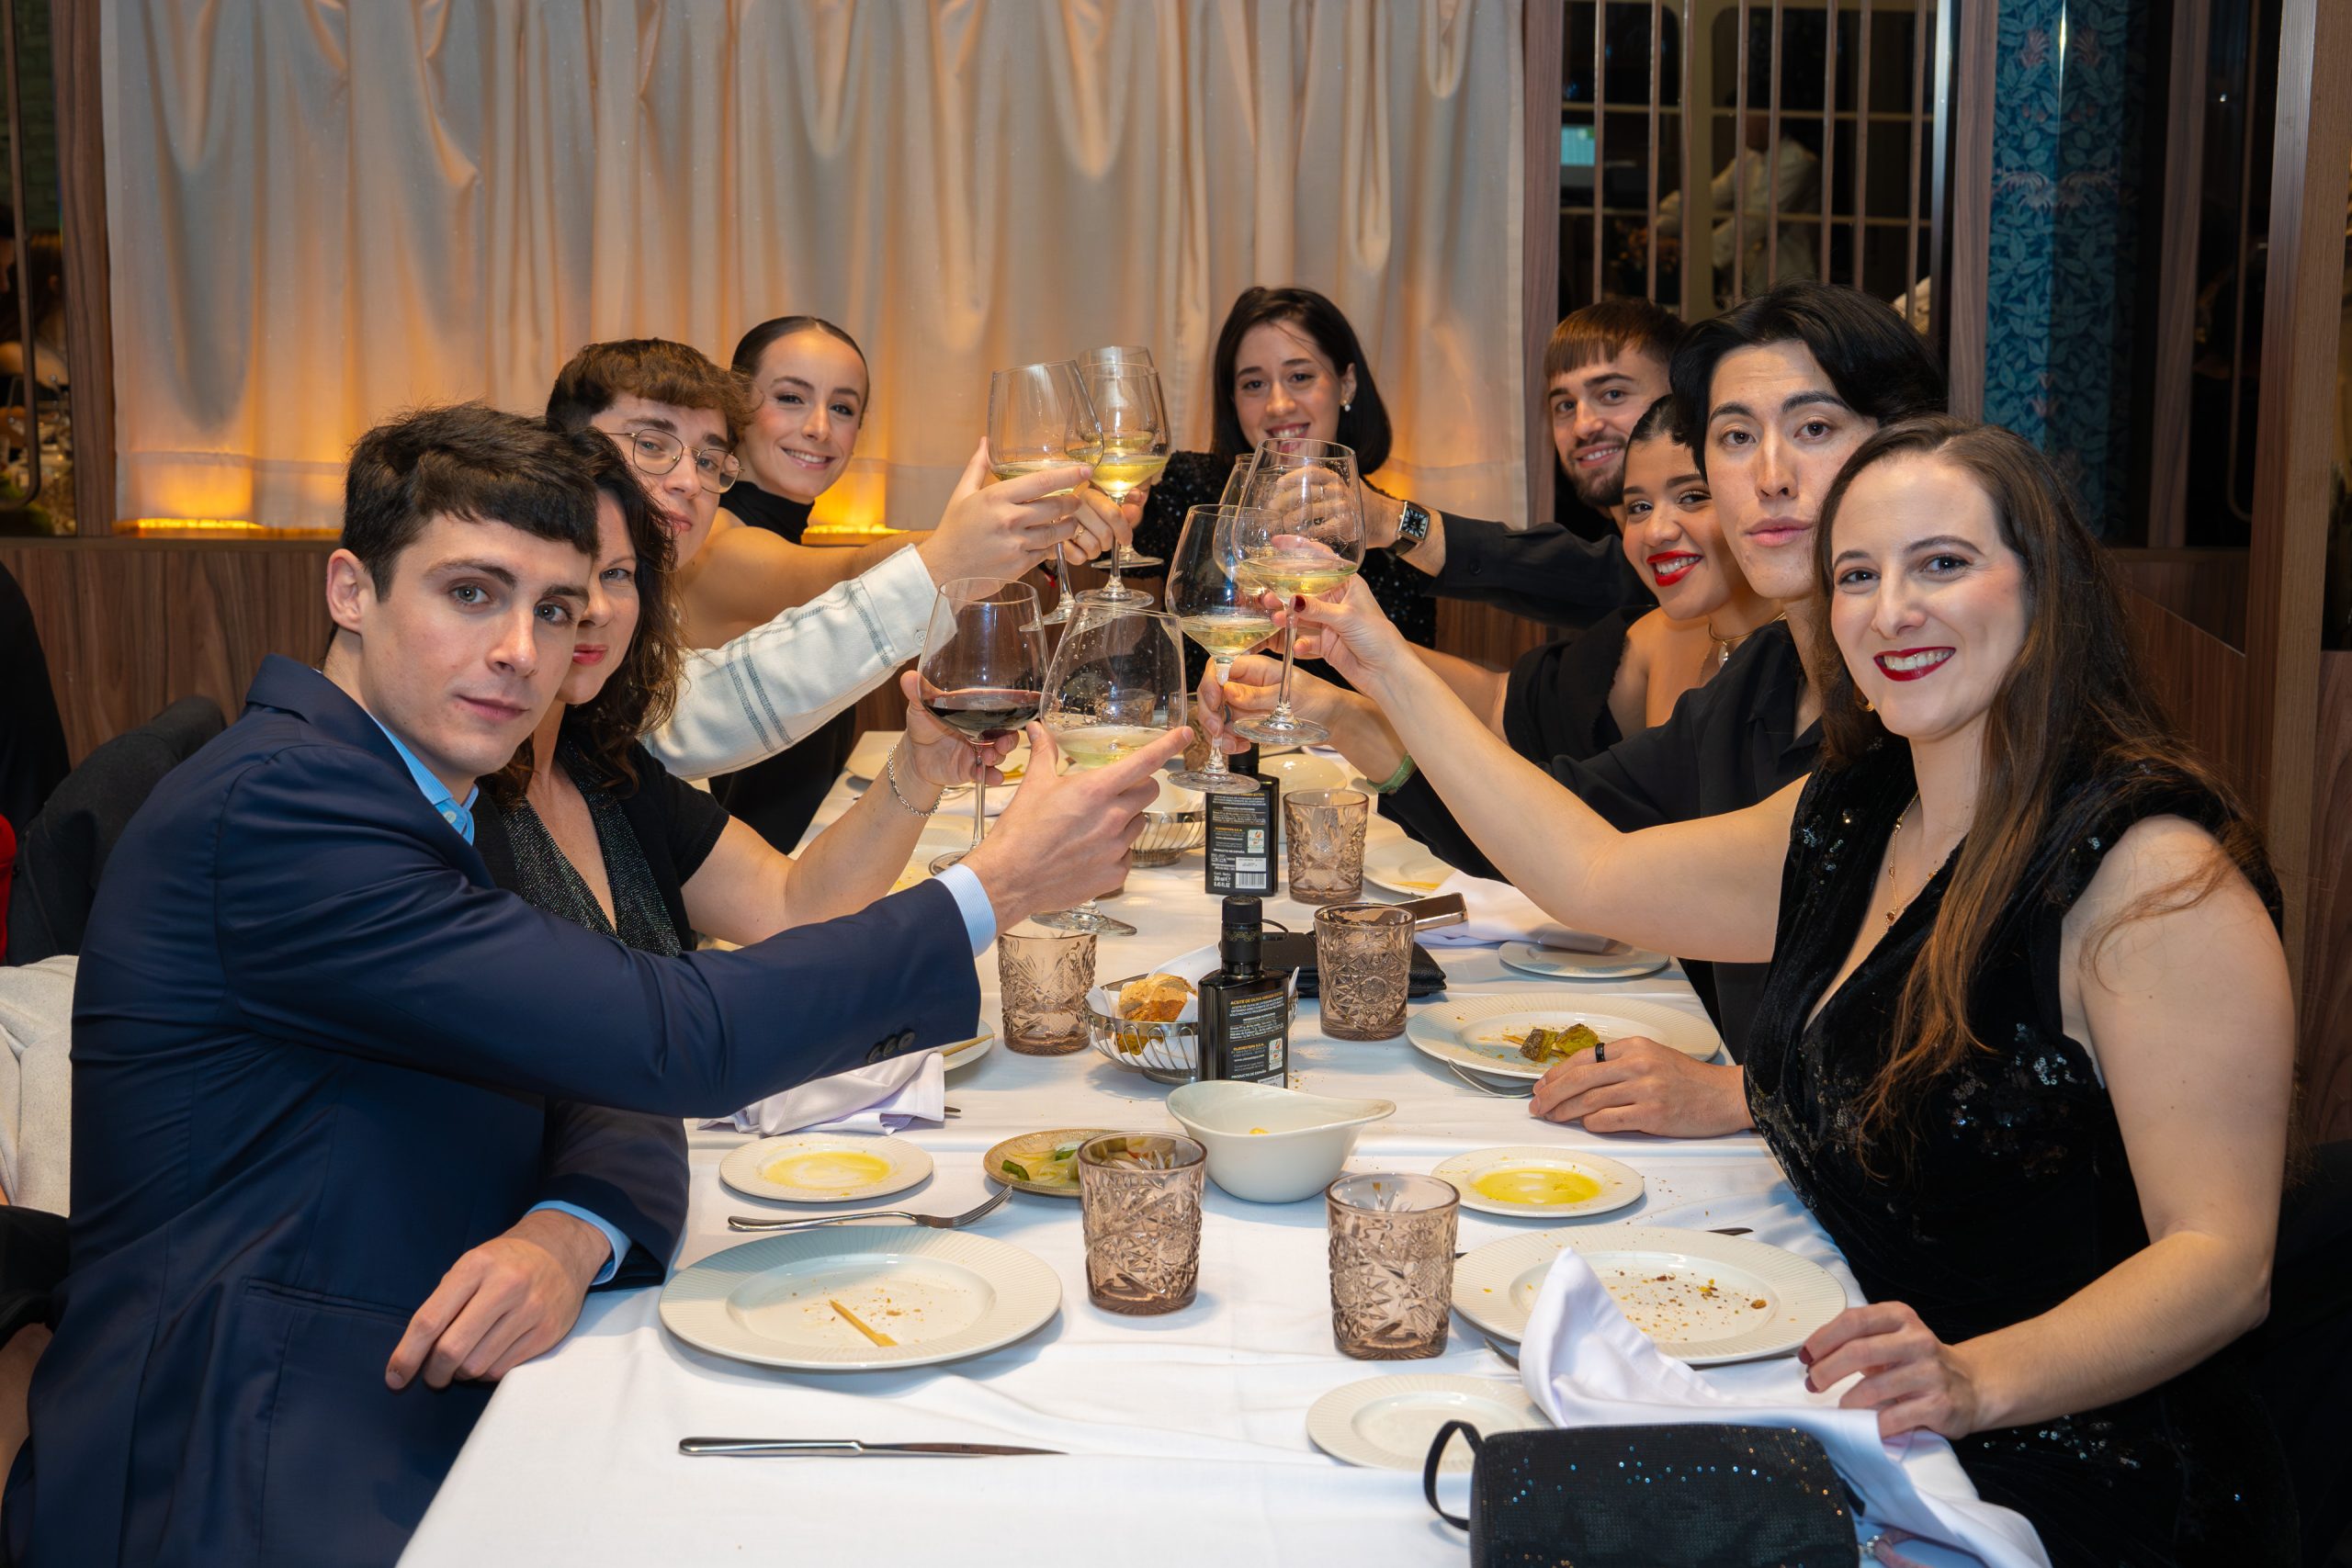
admin

Tax Office criteria in Beckham Rule tax audits.

As you may have seen in our media, we have discussed the Beckham Law, its requirements, advantages, and how it works. But it is also important to understand what Spanish tax inspectors are looking for when they open an investigation. The Tax Agency does not act randomly, so receiving a notification usually has a reason.

Inspectors tend to look for certain patterns: newly established Spanish companies with limited resources that generate income abroad, foreign companies managed from Spain that could be considered permanent establishments, assets abroad that are disproportionate to declared salaries, and income or assets abroad in the year of relocation, such as property sales, transfers, or investment returns.

Being aware of these factors helps you anticipate possible inspections and ensure that your structure under the Beckham Law complies with regulations. If you would like to review your situation, please do not hesitate to contact us.
Beckham Law and Primary Residence in Spain: Tax Update

The Beckham Law regime has historically been very attractive for professionals relocating to Spain, as it allows them to pay a fixed tax rate on income earned in the country, generally without taxing worldwide income. However, questions have always arisen regarding the application of certain rules, particularly concerning real estate.

Until now, if a property in Spain was the taxpayer’s primary residence, it was not considered to generate income from real estate, following the same logic applied to regular residents. However, a recent ruling has changed this interpretation, and now taxpayers under the Beckham Law must pay tax on the property they own in Spain, even if it is their main residence. In practice, this means they are treated as residents with an available urban property, with the corresponding tax obligations.

This change highlights that special regimes remain highly attractive, but they are subject to modifications in interpretative criteria and a higher level of tax scrutiny. For this reason, personalized tax advice is essential for beneficiaries of this regime, helping them plan ahead and optimize their tax situation while avoiding unexpected surprises. Staying informed and adapting to changes is key to fully benefiting from these special regimes.


Living Between Two Countries Doesn’t Mean Paying Taxes Twice

There is a common belief that if you live between two countries or earn income abroad, you will end up paying taxes twice on the same income. In reality, the tax situation is very different.

Most countries have signed double taxation agreements (DTAs) specifically designed to prevent the same income from being taxed twice. These agreements determine which country has the right to tax each type of income—such as employment income, dividends, rental income, or pensions—and how double taxation is eliminated.

In practice, your country of tax residence will usually allow you to credit or deduct the tax paid in the other country, in accordance with the applicable tax treaty. As a result, even if you have tax obligations in more than one jurisdiction, the overall tax burden is generally neutralized.

Living between countries can certainly add complexity. Correctly determining tax residence, applying the right treaty, and filing tax returns properly and on time are essential. When done correctly, double taxation is the exception, not the rule.

In short, having international income does not automatically mean paying more tax—it means understanding the rules and applying tax treaties correctly.


Key points of the reinvestment exemption for primary residence applicable to non-residents

It is commonly assumed that non-residents cannot apply the reinvestment exemption for a primary residence. However, this is not always correct.

Additional Provision 7 of the Spanish Personal Income Tax Law allows the capital gain from the sale of a former primary residence in Spain to be exempt, even after the taxpayer has become a non-resident, provided the proceeds are reinvested in a new primary residence.

To apply the exemption:

  • The taxpayer must have been a Spanish tax resident prior to the sale.

  • Both properties must qualify as primary residences under IRPF rules.

  • Legal reinvestment deadlines must be met.

  • The new primary residence does not need to be located in Spain, as confirmed by recent binding rulings.

This exemption does not apply to taxpayers under the Beckham Law regime.

Due to its complexity, this provision should be analysed carefully on a case-by-case basis.


Related-Party Transactions: Their Importance in Proper Formalization

During November, we focused on the preparation and filing of Form 232, the informative declaration for related-party transactions and transactions with non-cooperative jurisdictions. Based on this experience, we want to share some essential professional recommendations.

Related-party transactions must always be valued at market conditions, in accordance with Articles 17 and 18 of the Corporate Income Tax Law, and be properly documented.

For loans and credit lines between related parties, it is crucial to formalize agreements and set a market-based interest rate.

Commercial transactions between related parties should be valued using the most appropriate method depending on the goods or services provided.

To ensure regulatory compliance, we recommend documenting all transactions in the Transfer Pricing Manual, a key tool to demonstrate that the conditions applied are equivalent to those in transactions between independent companies, reducing tax risks.

We remain available to provide specialized advice and assist with any questions regarding Form 232 and related-party transactions.

New ruling on the deduction of expenses for non-residents

In July this year, the Spanish National Court issued a relevant ruling affecting non-resident owners with rented properties in Spain. Until now, only residents of the European Union were allowed to deduct expenses related to rental income, while residents of third countries were required to pay tax on the full amount received.

The National Court recognized this right for a taxpayer residing in the United States, considering that denying the deduction violates both the principle of free movement of capital under the Treaty on the Functioning of the European Union and the principle of non-discrimination set out in the Double Taxation Agreement between Spain and the United States.

Although this ruling does not establish legal precedent, it represents an important step towards equalizing the tax treatment of EU and non-EU residents. It is still too early to initiate claims for tax corrections or refunds for non-prescribed fiscal years, but the decision marks significant progress in addressing a long-standing discriminatory situation.

Avoid a €500,000 Shock: The Truth About Spain’s Solidarity Tax with Miriem Diori, MDG Advisors

Investing in Spain can be highly attractive, especially in Málaga and the Costa del Sol, but understanding the Solidarity Tax on Large Fortunes is essential to avoid unexpected costs.

Although Wealth Tax has been abolished in Andalusia, the national Solidarity Tax still applies to individuals with net assets exceeding €3.7 million per person.

  • Residents are taxed on their worldwide assets.

  • Non-residents are taxed on assets located in Spain, including real estate, bank accounts, and investment portfolios.

Without proper planning, some investors have faced annual tax bills of up to €500,000. Structuring investments correctly — for example, purchasing jointly with a spouse or partner — can significantly reduce or even eliminate this tax.

Early professional tax and legal advice is key to investing in Spain with confidence and peace of mind.

New court ruling: Wealth Tax limits for non-residents in Spain.

In Spain, tax residents face certain limits on their tax and solidarity contributions, based on their economic capacity and personal income tax (IRPF) situation.

A recent Supreme Court ruling confirms that these limits can also apply to non-residents, as restricting them to residents only could be considered discriminatory. This opens the door for non-residents to adjust their tax obligations based on their assets in Spain.

To understand how these limits affect your situation, it’s important to review your tax status and filings.

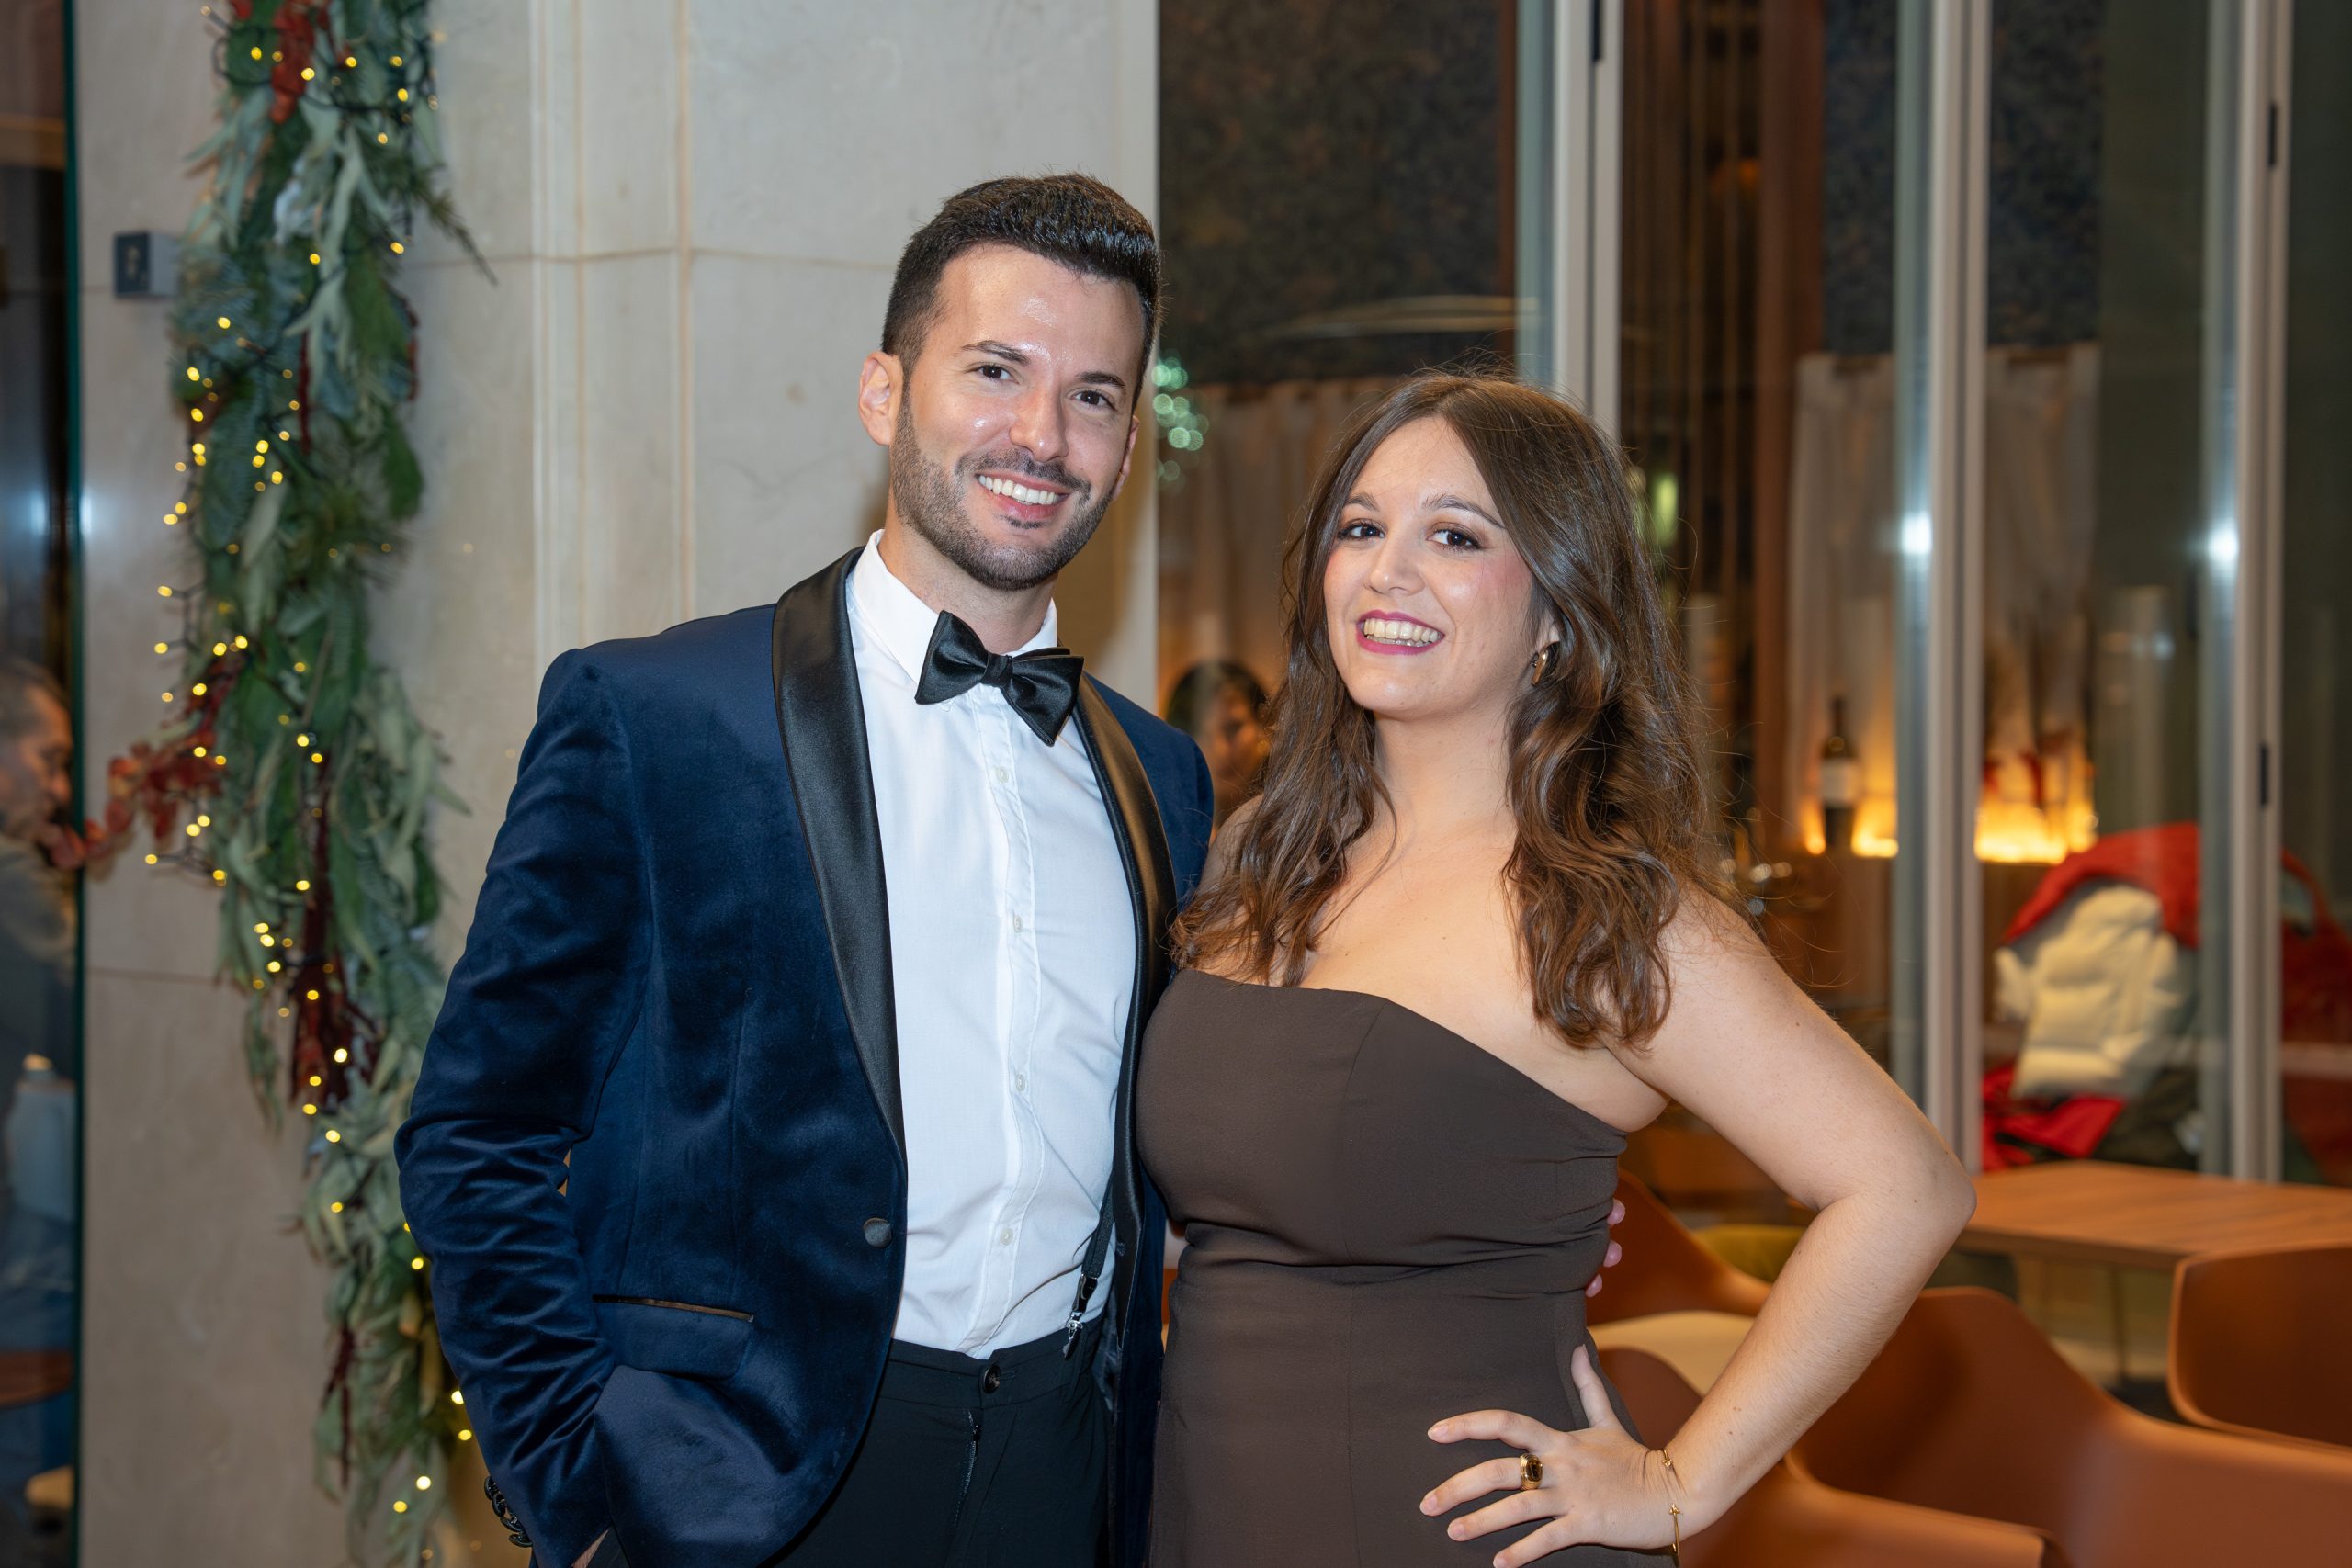
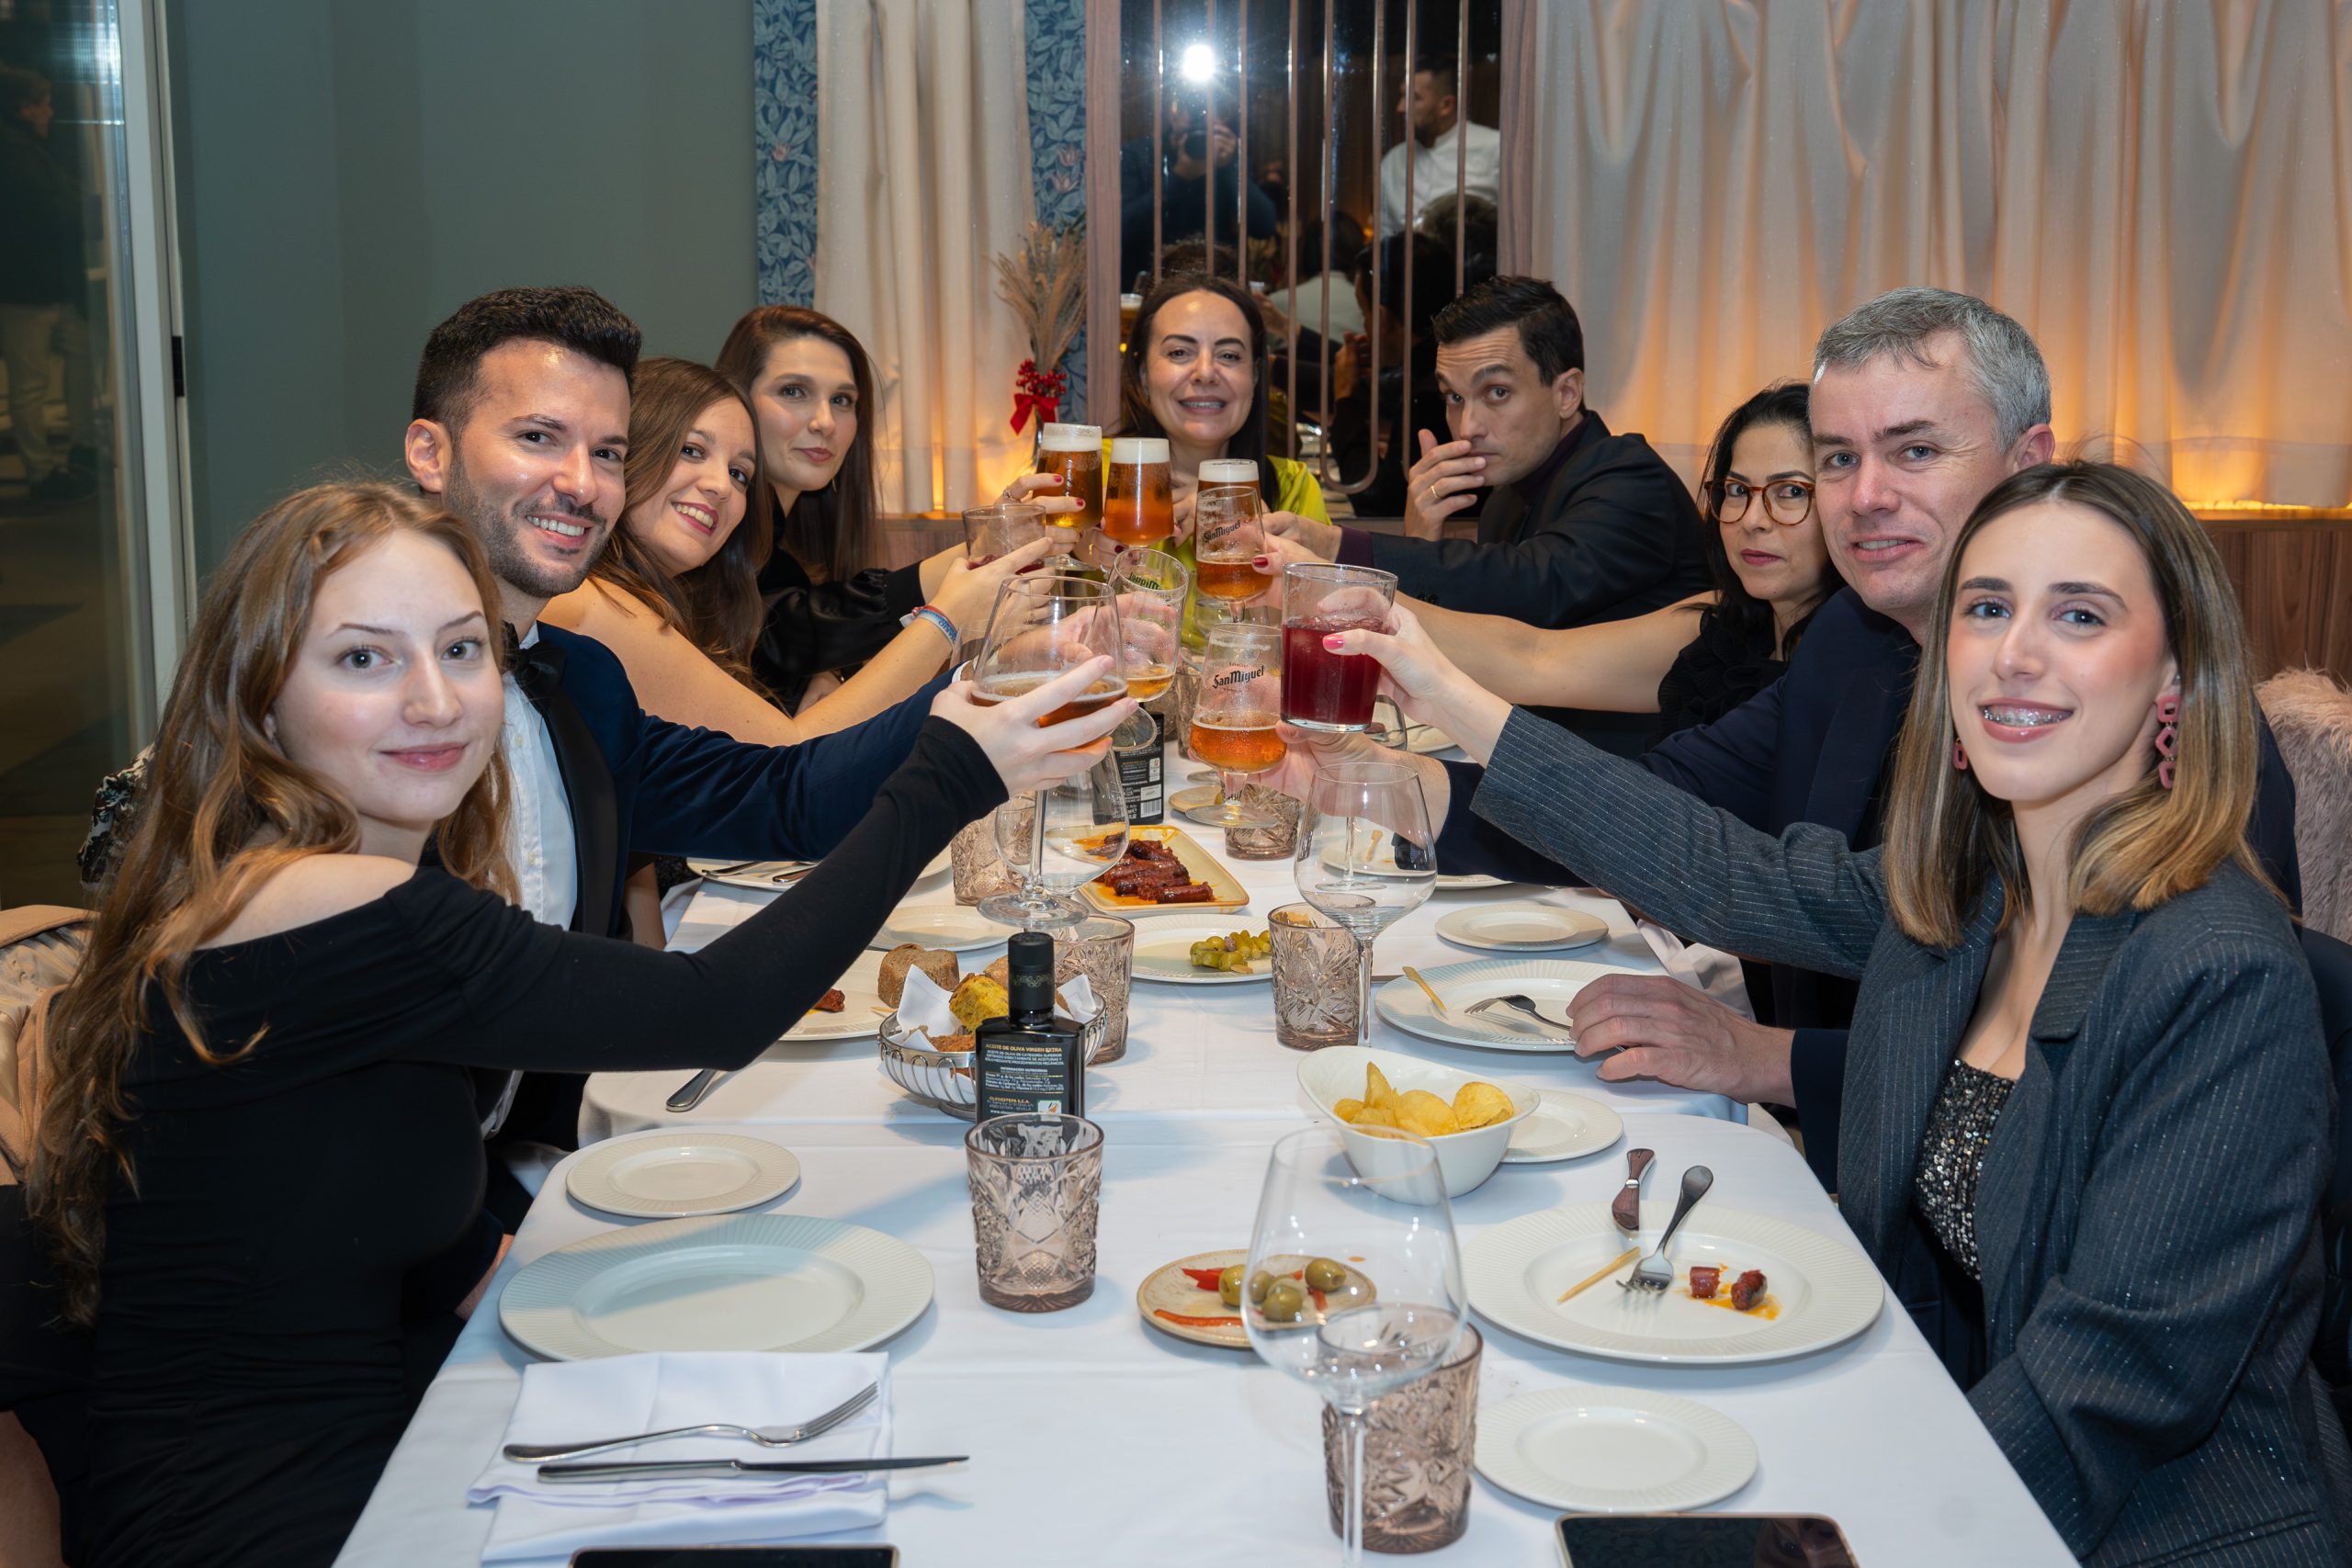
Christmas dinner 2025

We would like to share some moments from our Christmas dinner, a time to pause, share, and give thanks for the great work done by the entire team throughout the year.

Laughter, good company, and lots of enthusiasm to continue growing together. Thank you to everyone who is part of MDG Advisors and makes this project possible every day.

✨ Here’s to a new year full of challenges and shared successes!


We wish you a Merry Christmas

From all of us at MDG Advisors, we wish you a Merry Christmas and a joyful holiday season. Thank you for your trust, collaboration, and continued support throughout the year.