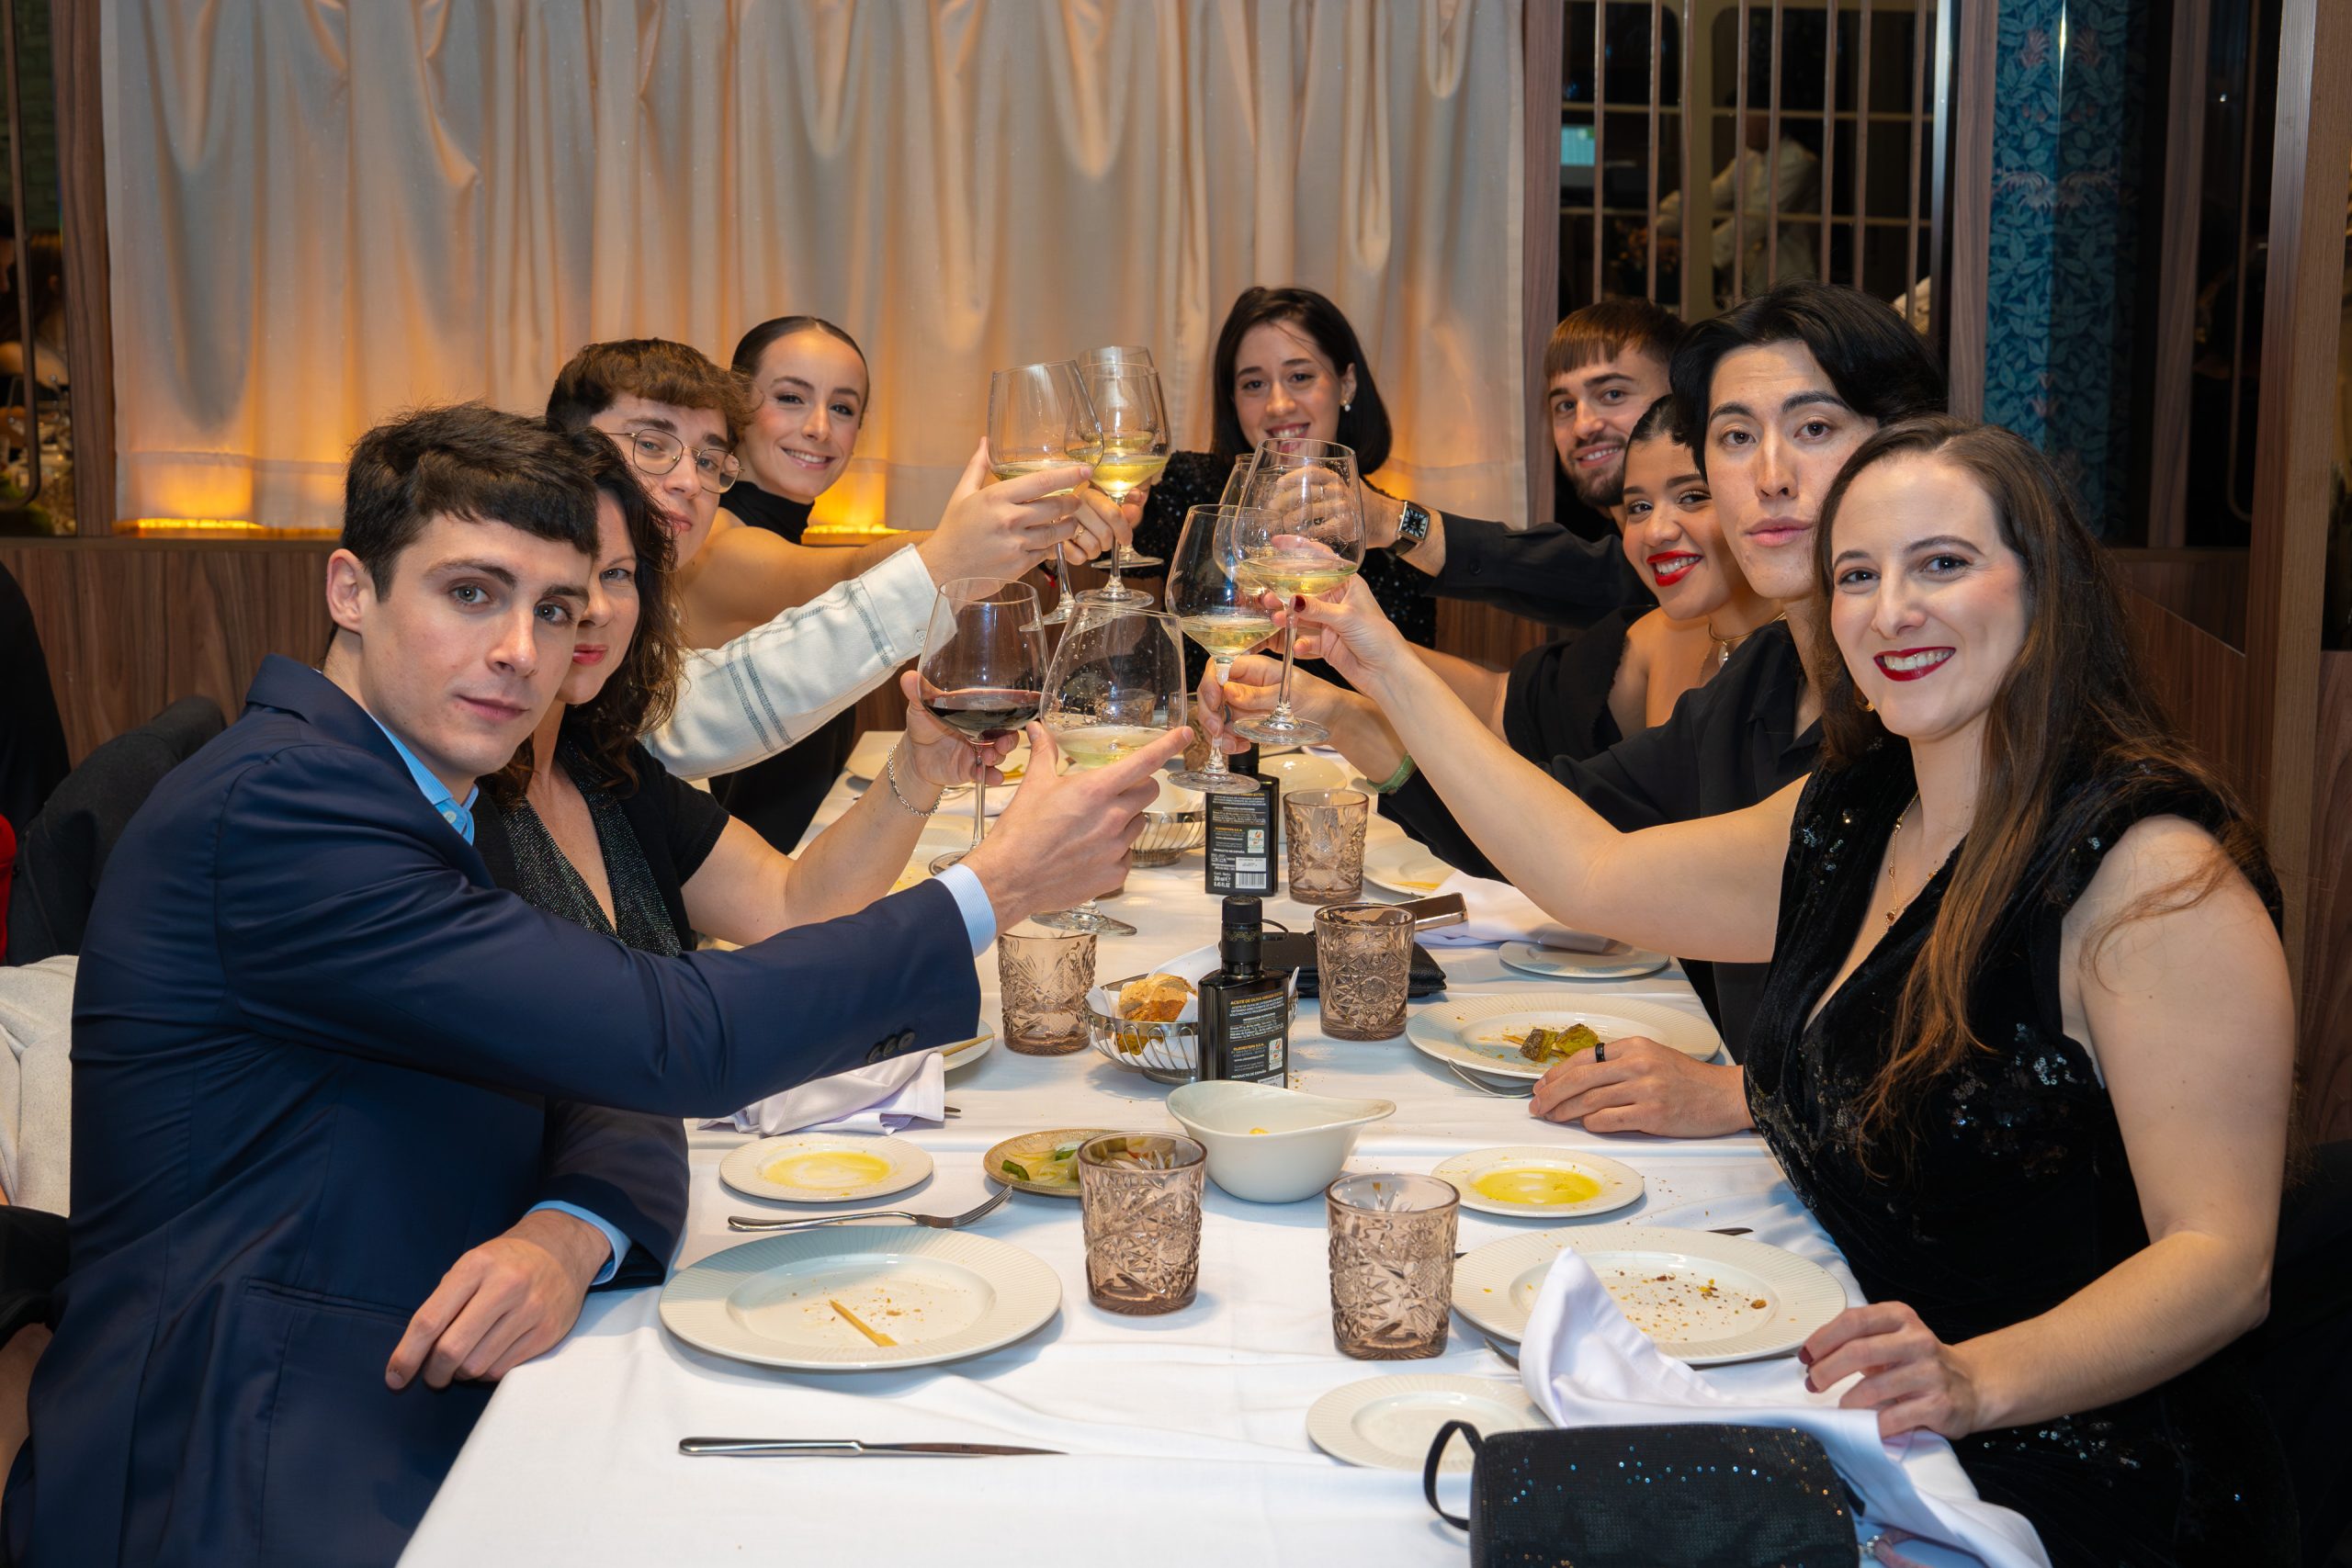admin

Beckham Law and Primary Residence in Spain: Tax Update

The Beckham Law regime has historically been very attractive for professionals relocating to Spain, as it allows them to pay a fixed tax rate on income earned in the country, generally without taxing worldwide income. However, questions have always arisen regarding the application of certain rules, particularly concerning real estate.

Until now, if a property in Spain was the taxpayer’s primary residence, it was not considered to generate income from real estate, following the same logic applied to regular residents. However, a recent ruling has changed this interpretation, and now taxpayers under the Beckham Law must pay tax on the property they own in Spain, even if it is their main residence. In practice, this means they are treated as residents with an available urban property, with the corresponding tax obligations.

This change highlights that special regimes remain highly attractive, but they are subject to modifications in interpretative criteria and a higher level of tax scrutiny. For this reason, personalized tax advice is essential for beneficiaries of this regime, helping them plan ahead and optimize their tax situation while avoiding unexpected surprises. Staying informed and adapting to changes is key to fully benefiting from these special regimes.


Living Between Two Countries Doesn’t Mean Paying Taxes Twice

There is a common belief that if you live between two countries or earn income abroad, you will end up paying taxes twice on the same income. In reality, the tax situation is very different.

Most countries have signed double taxation agreements (DTAs) specifically designed to prevent the same income from being taxed twice. These agreements determine which country has the right to tax each type of income—such as employment income, dividends, rental income, or pensions—and how double taxation is eliminated.

In practice, your country of tax residence will usually allow you to credit or deduct the tax paid in the other country, in accordance with the applicable tax treaty. As a result, even if you have tax obligations in more than one jurisdiction, the overall tax burden is generally neutralized.

Living between countries can certainly add complexity. Correctly determining tax residence, applying the right treaty, and filing tax returns properly and on time are essential. When done correctly, double taxation is the exception, not the rule.

In short, having international income does not automatically mean paying more tax—it means understanding the rules and applying tax treaties correctly.


Key points of the reinvestment exemption for primary residence applicable to non-residents

It is commonly assumed that non-residents cannot apply the reinvestment exemption for a primary residence. However, this is not always correct.

Additional Provision 7 of the Spanish Personal Income Tax Law allows the capital gain from the sale of a former primary residence in Spain to be exempt, even after the taxpayer has become a non-resident, provided the proceeds are reinvested in a new primary residence.

To apply the exemption:

  • The taxpayer must have been a Spanish tax resident prior to the sale.

  • Both properties must qualify as primary residences under IRPF rules.

  • Legal reinvestment deadlines must be met.

  • The new primary residence does not need to be located in Spain, as confirmed by recent binding rulings.

This exemption does not apply to taxpayers under the Beckham Law regime.

Due to its complexity, this provision should be analysed carefully on a case-by-case basis.


Related-Party Transactions: Their Importance in Proper Formalization

During November, we focused on the preparation and filing of Form 232, the informative declaration for related-party transactions and transactions with non-cooperative jurisdictions. Based on this experience, we want to share some essential professional recommendations.

Related-party transactions must always be valued at market conditions, in accordance with Articles 17 and 18 of the Corporate Income Tax Law, and be properly documented.

For loans and credit lines between related parties, it is crucial to formalize agreements and set a market-based interest rate.

Commercial transactions between related parties should be valued using the most appropriate method depending on the goods or services provided.

To ensure regulatory compliance, we recommend documenting all transactions in the Transfer Pricing Manual, a key tool to demonstrate that the conditions applied are equivalent to those in transactions between independent companies, reducing tax risks.

We remain available to provide specialized advice and assist with any questions regarding Form 232 and related-party transactions.

New ruling on the deduction of expenses for non-residents

In July this year, the Spanish National Court issued a relevant ruling affecting non-resident owners with rented properties in Spain. Until now, only residents of the European Union were allowed to deduct expenses related to rental income, while residents of third countries were required to pay tax on the full amount received.

The National Court recognized this right for a taxpayer residing in the United States, considering that denying the deduction violates both the principle of free movement of capital under the Treaty on the Functioning of the European Union and the principle of non-discrimination set out in the Double Taxation Agreement between Spain and the United States.

Although this ruling does not establish legal precedent, it represents an important step towards equalizing the tax treatment of EU and non-EU residents. It is still too early to initiate claims for tax corrections or refunds for non-prescribed fiscal years, but the decision marks significant progress in addressing a long-standing discriminatory situation.

Avoid a €500,000 Shock: The Truth About Spain’s Solidarity Tax with Miriem Diori, MDG Advisors

Investing in Spain can be highly attractive, especially in Málaga and the Costa del Sol, but understanding the Solidarity Tax on Large Fortunes is essential to avoid unexpected costs.

Although Wealth Tax has been abolished in Andalusia, the national Solidarity Tax still applies to individuals with net assets exceeding €3.7 million per person.

  • Residents are taxed on their worldwide assets.

  • Non-residents are taxed on assets located in Spain, including real estate, bank accounts, and investment portfolios.

Without proper planning, some investors have faced annual tax bills of up to €500,000. Structuring investments correctly — for example, purchasing jointly with a spouse or partner — can significantly reduce or even eliminate this tax.

Early professional tax and legal advice is key to investing in Spain with confidence and peace of mind.

New court ruling: Wealth Tax limits for non-residents in Spain.

In Spain, tax residents face certain limits on their tax and solidarity contributions, based on their economic capacity and personal income tax (IRPF) situation.

A recent Supreme Court ruling confirms that these limits can also apply to non-residents, as restricting them to residents only could be considered discriminatory. This opens the door for non-residents to adjust their tax obligations based on their assets in Spain.

To understand how these limits affect your situation, it’s important to review your tax status and filings.

Christmas dinner 2025

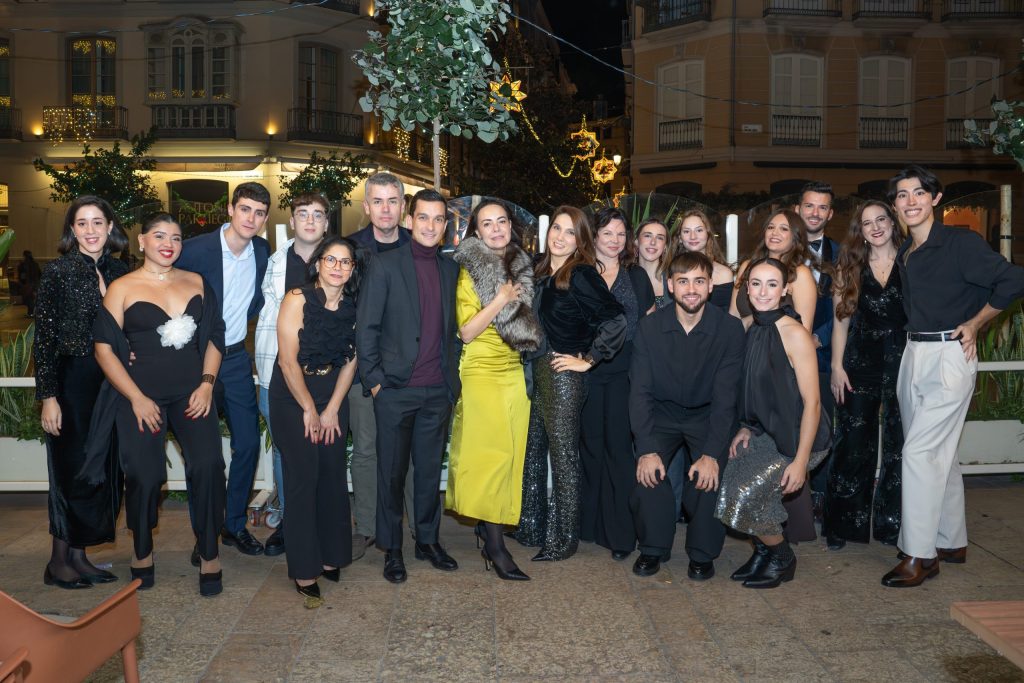
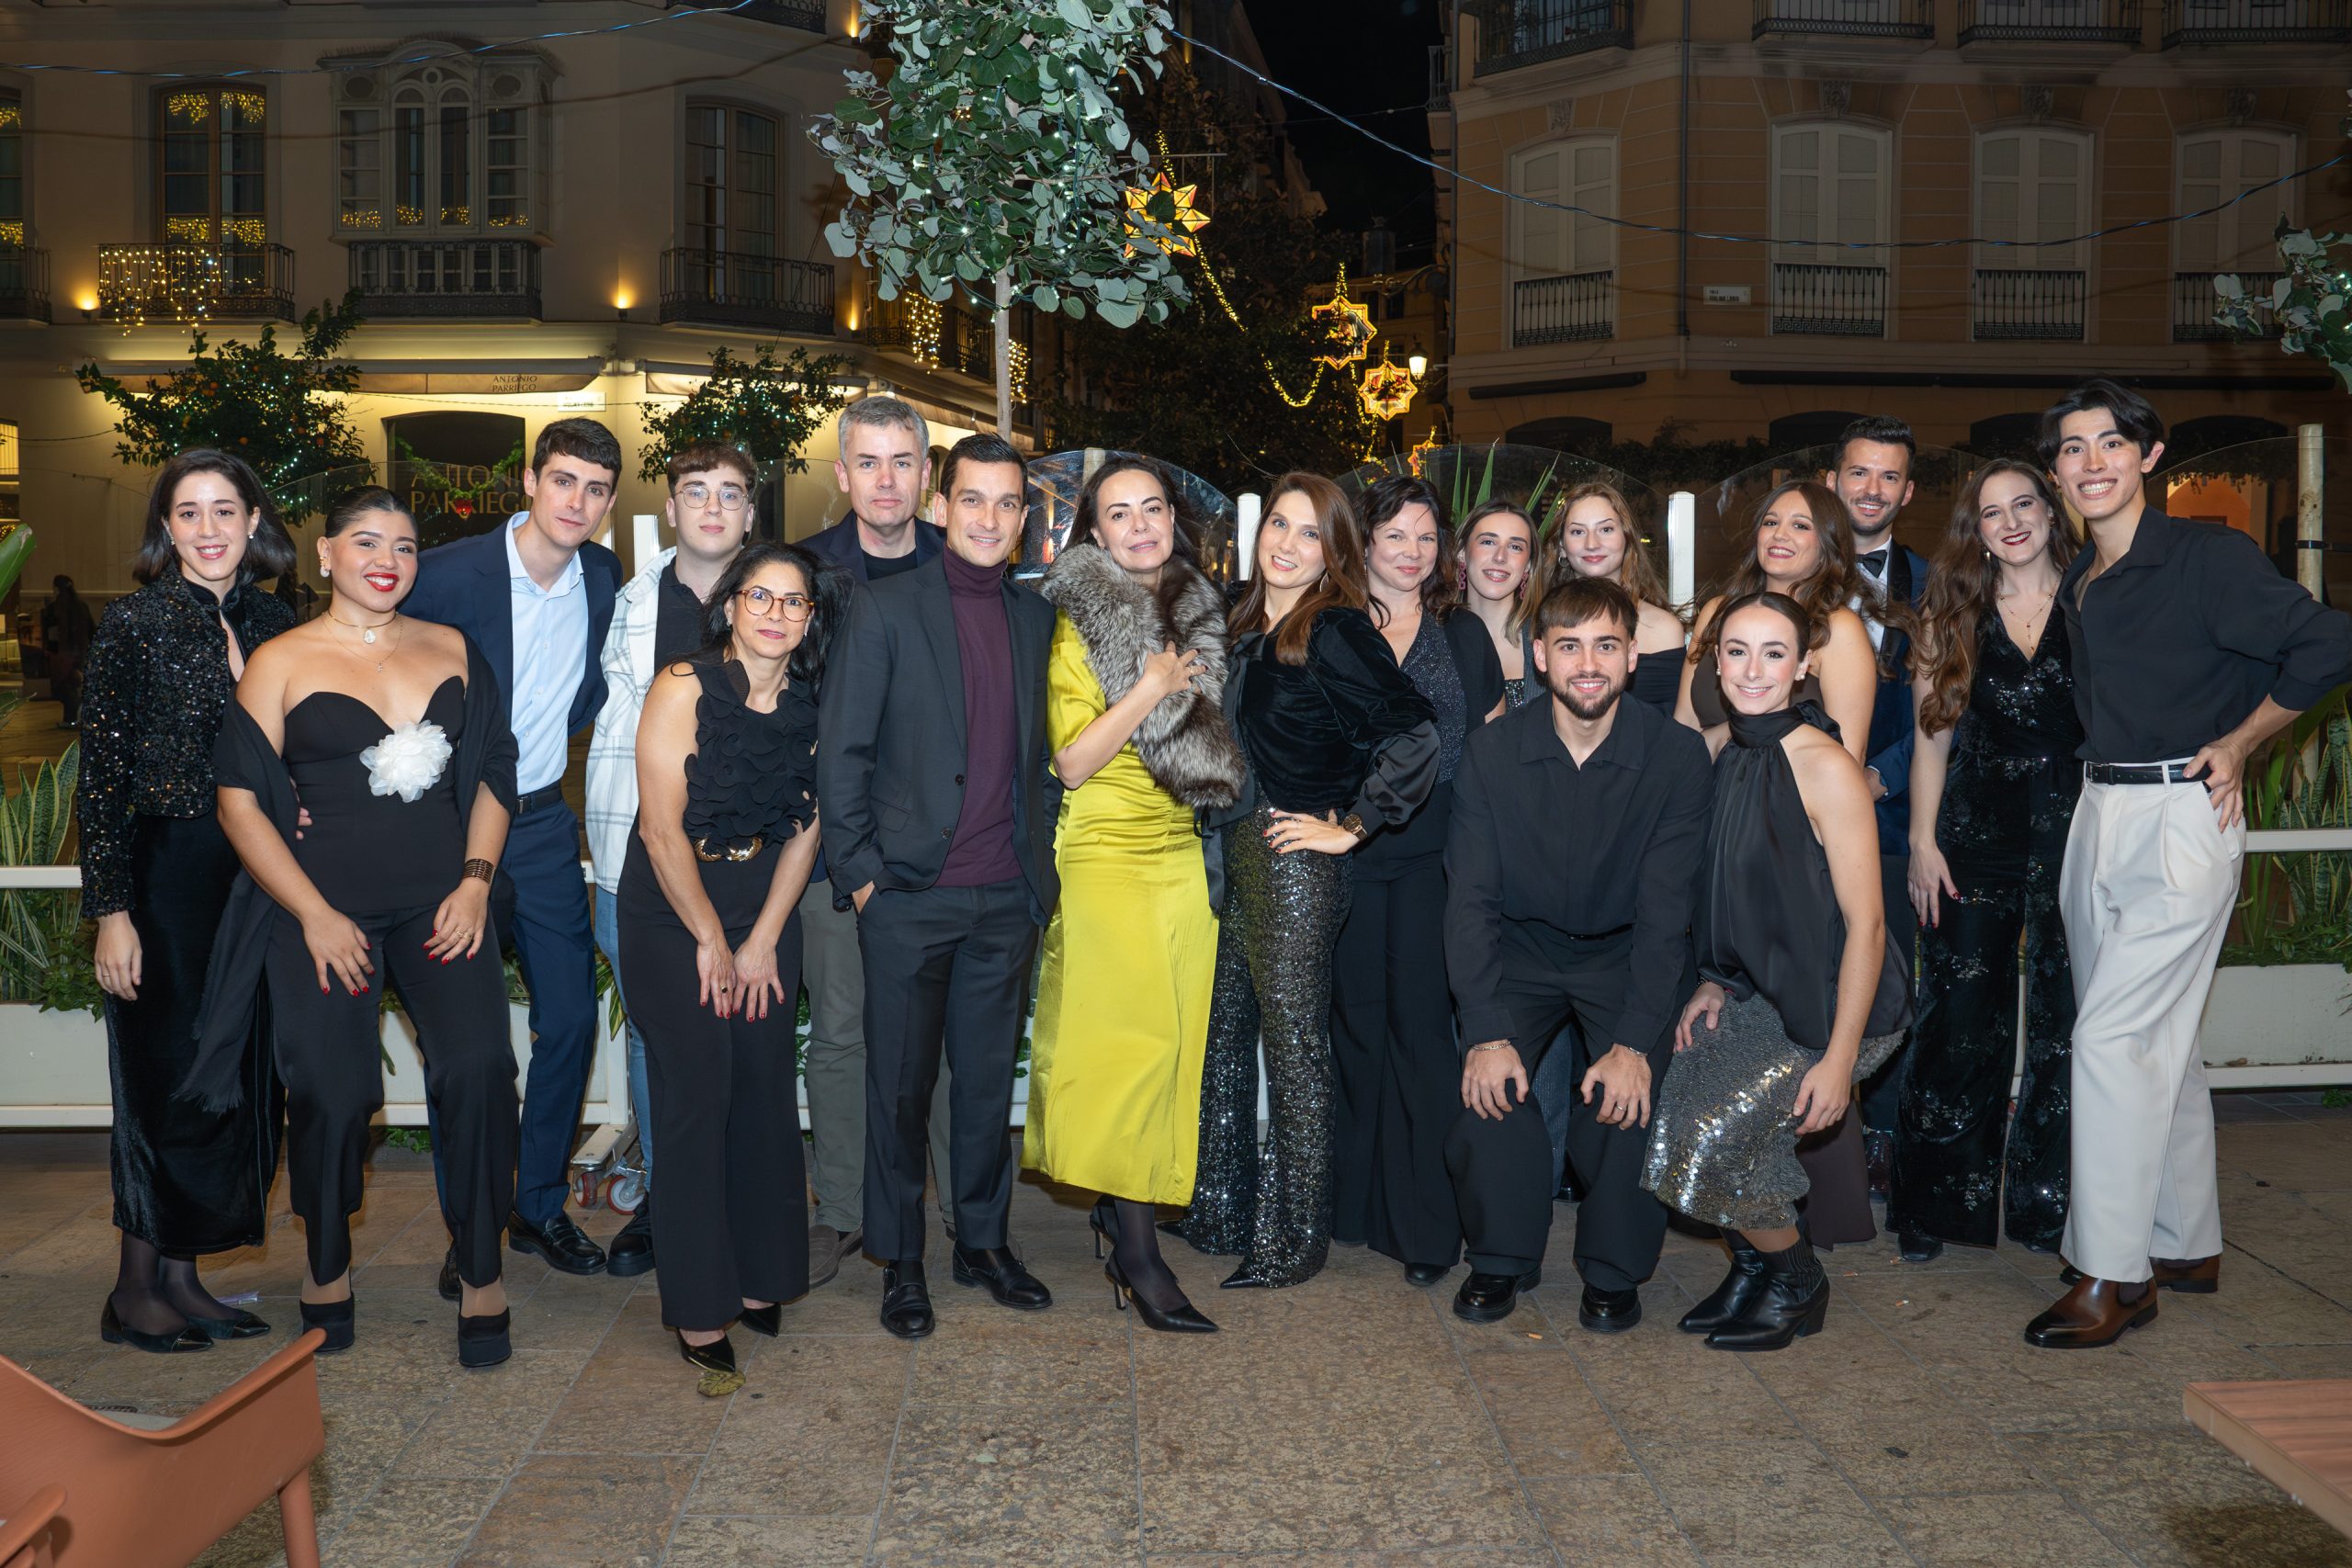
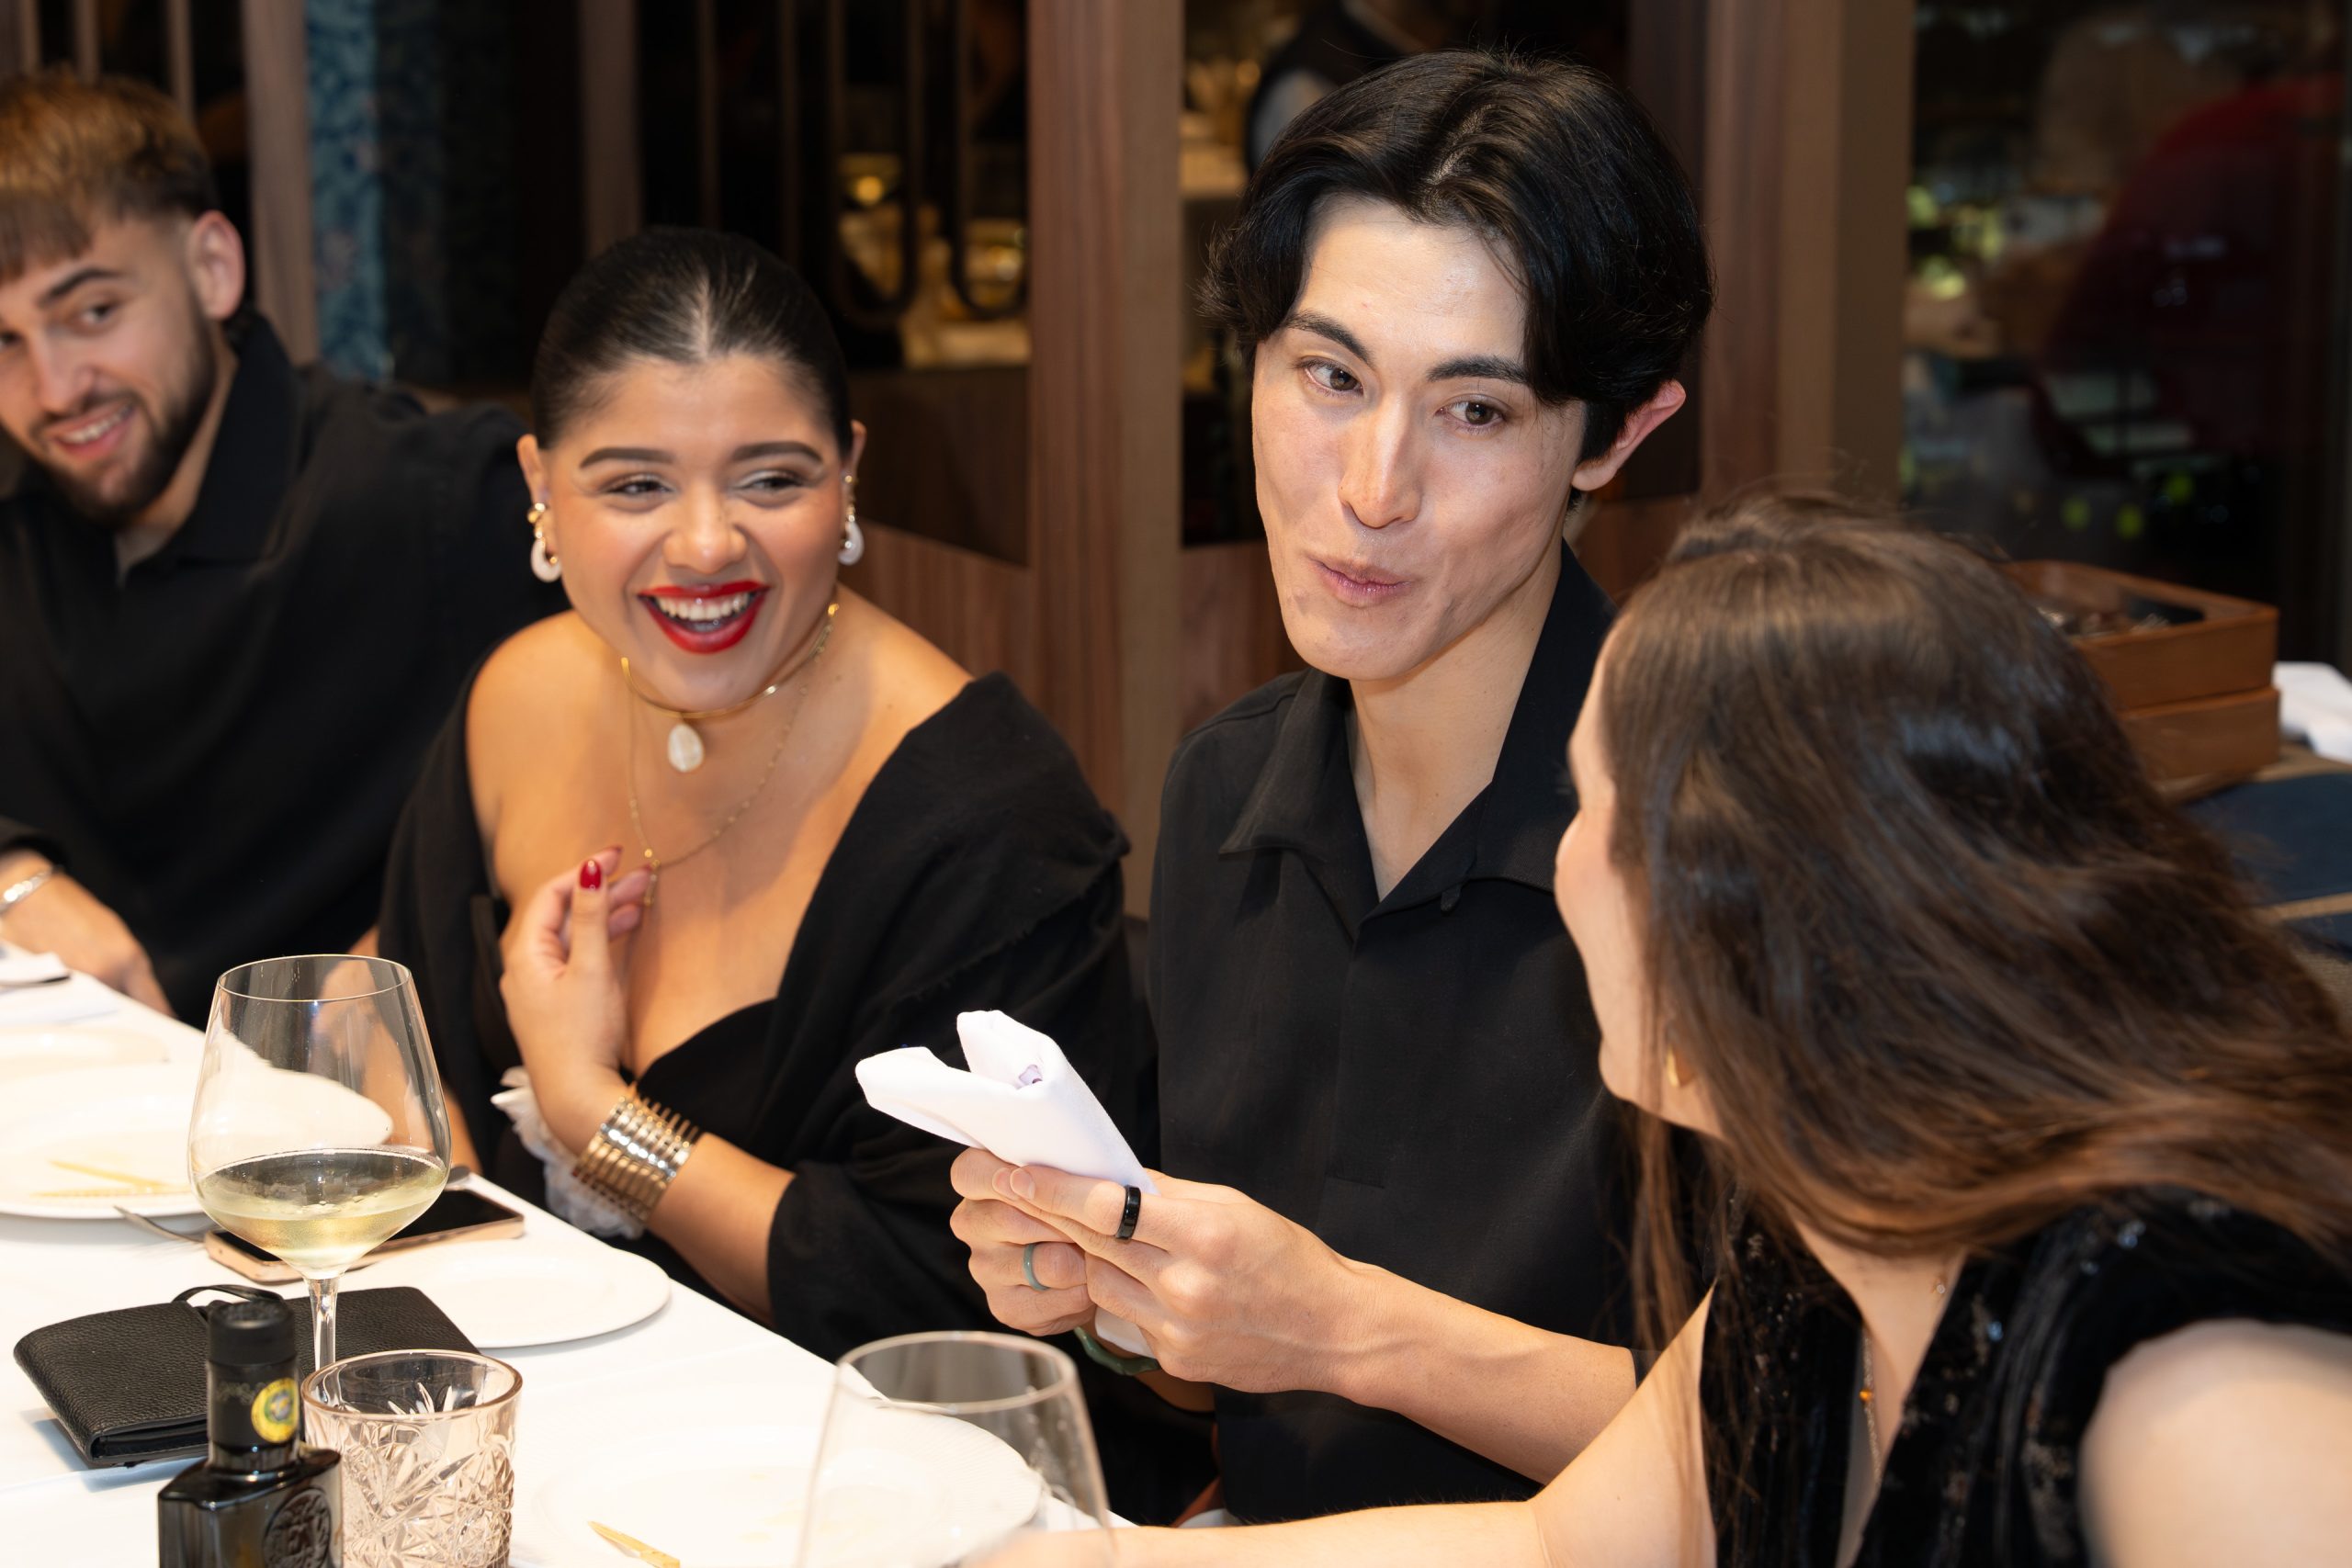
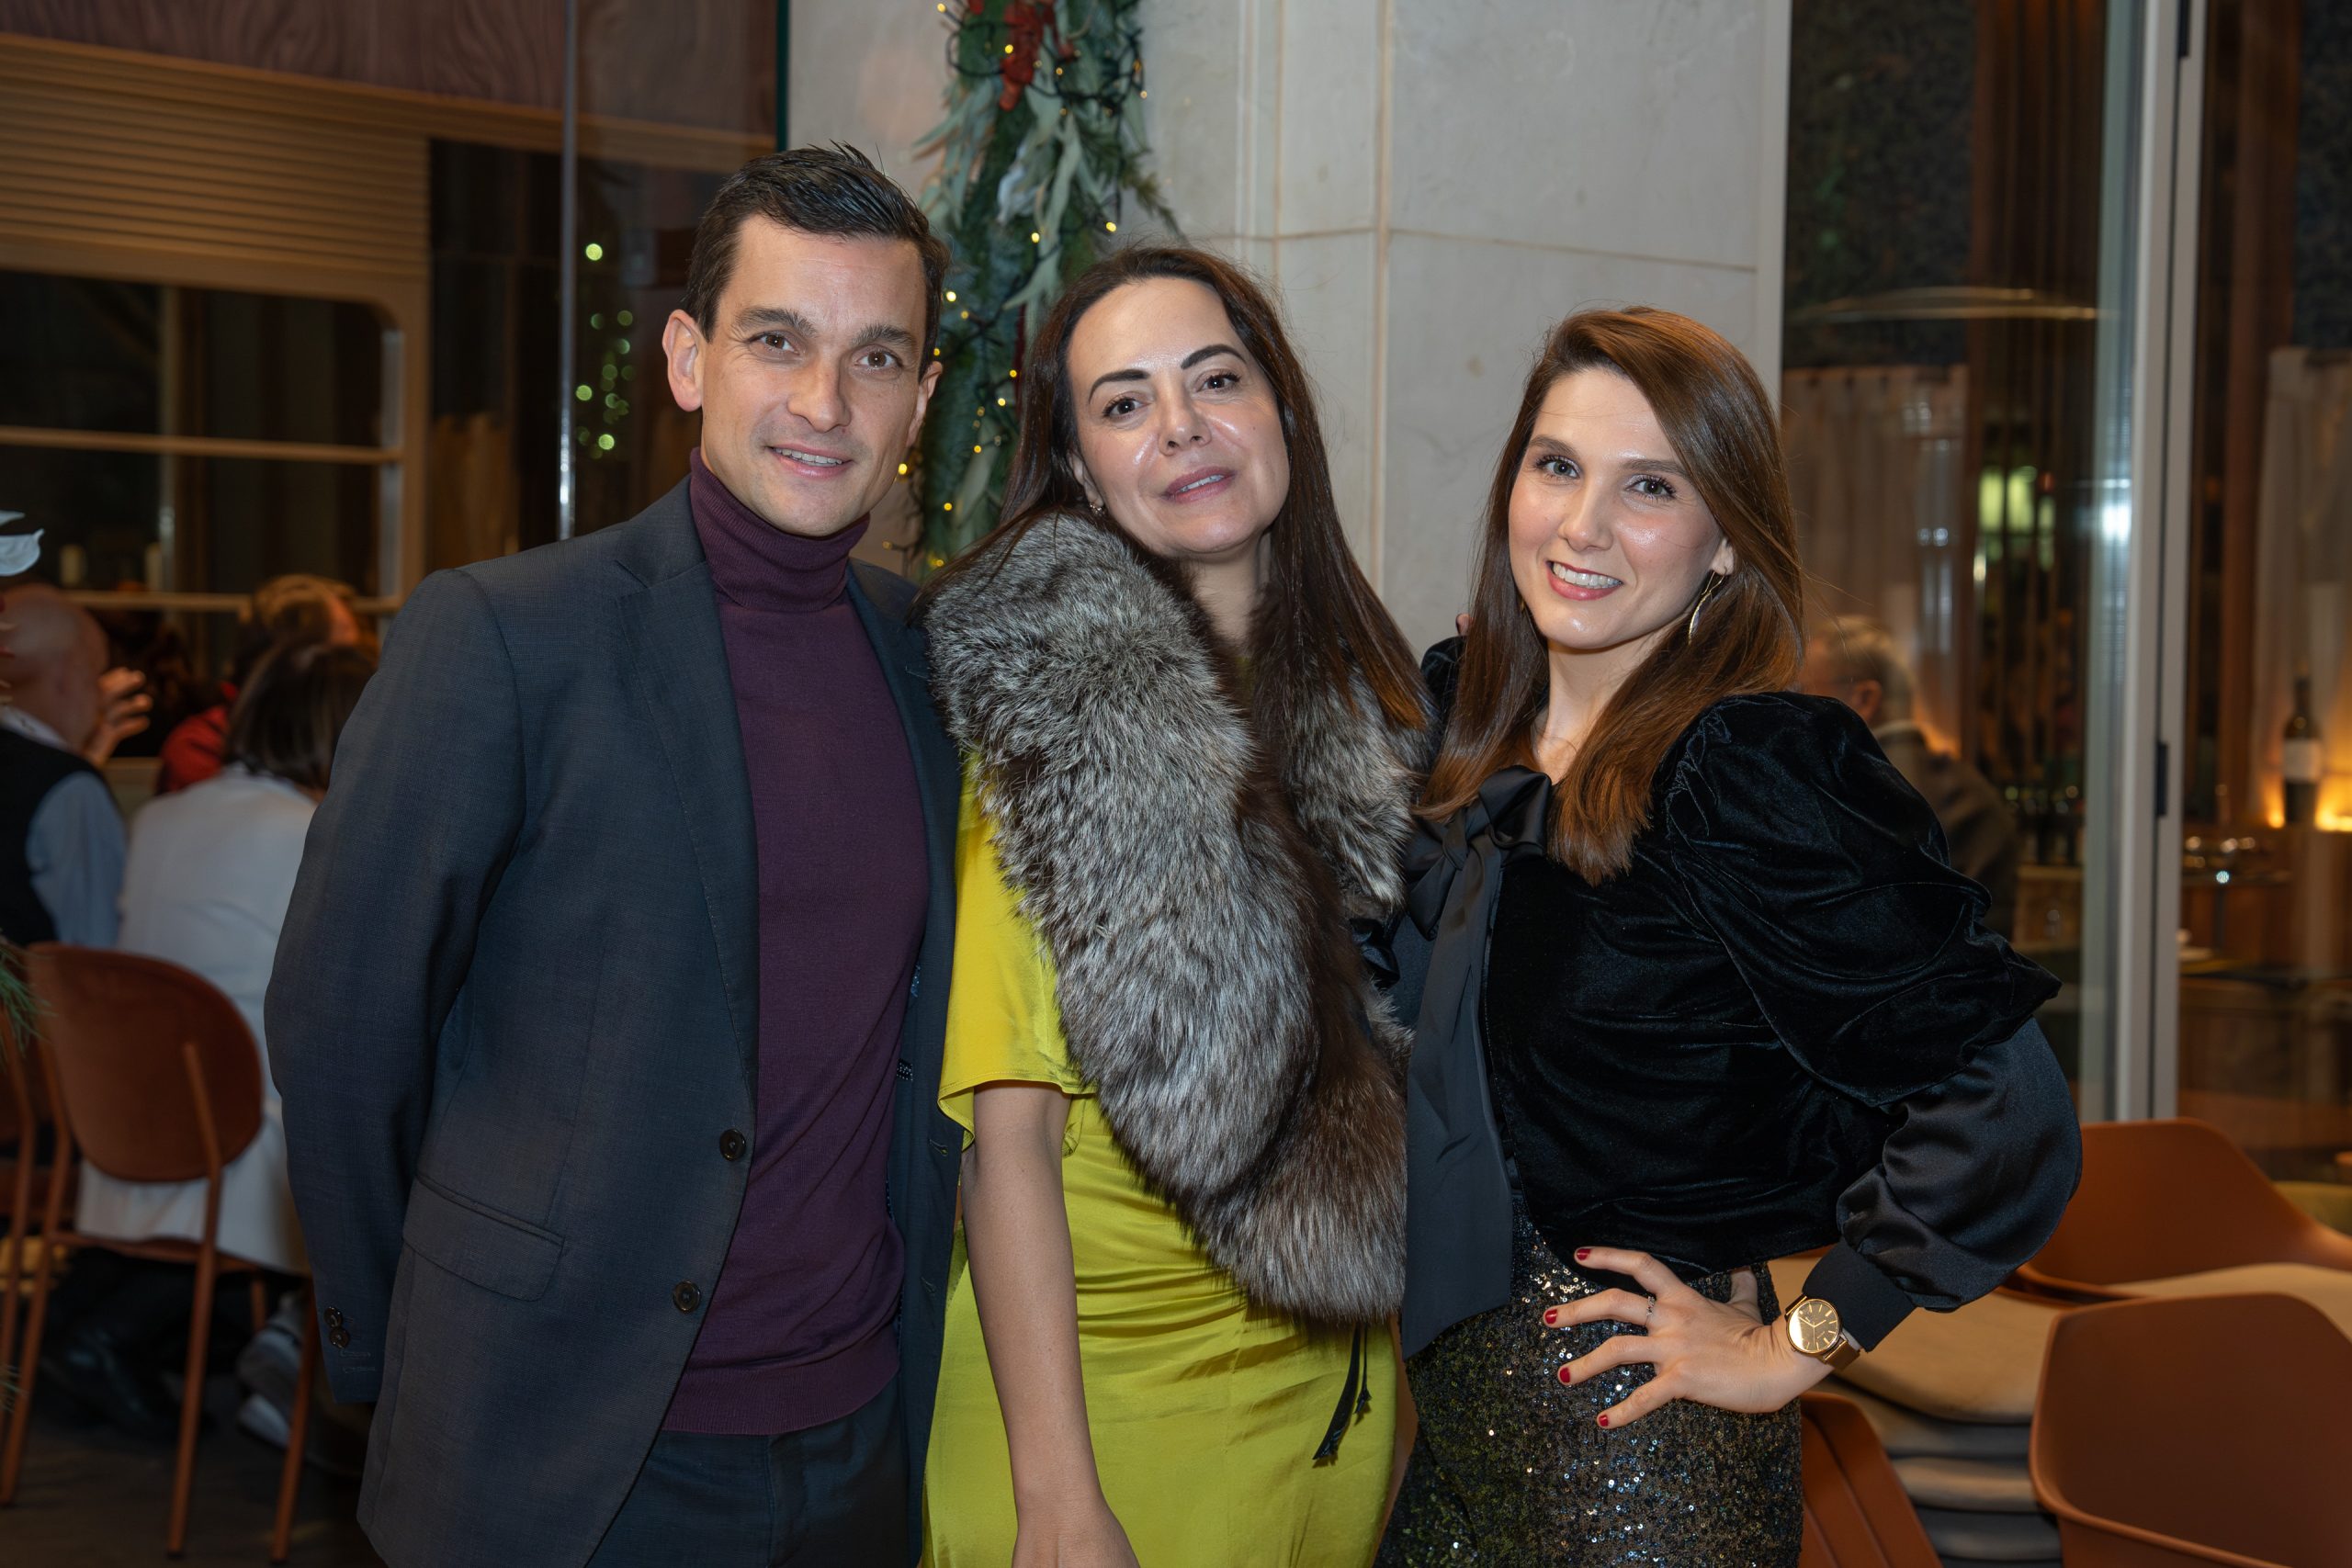
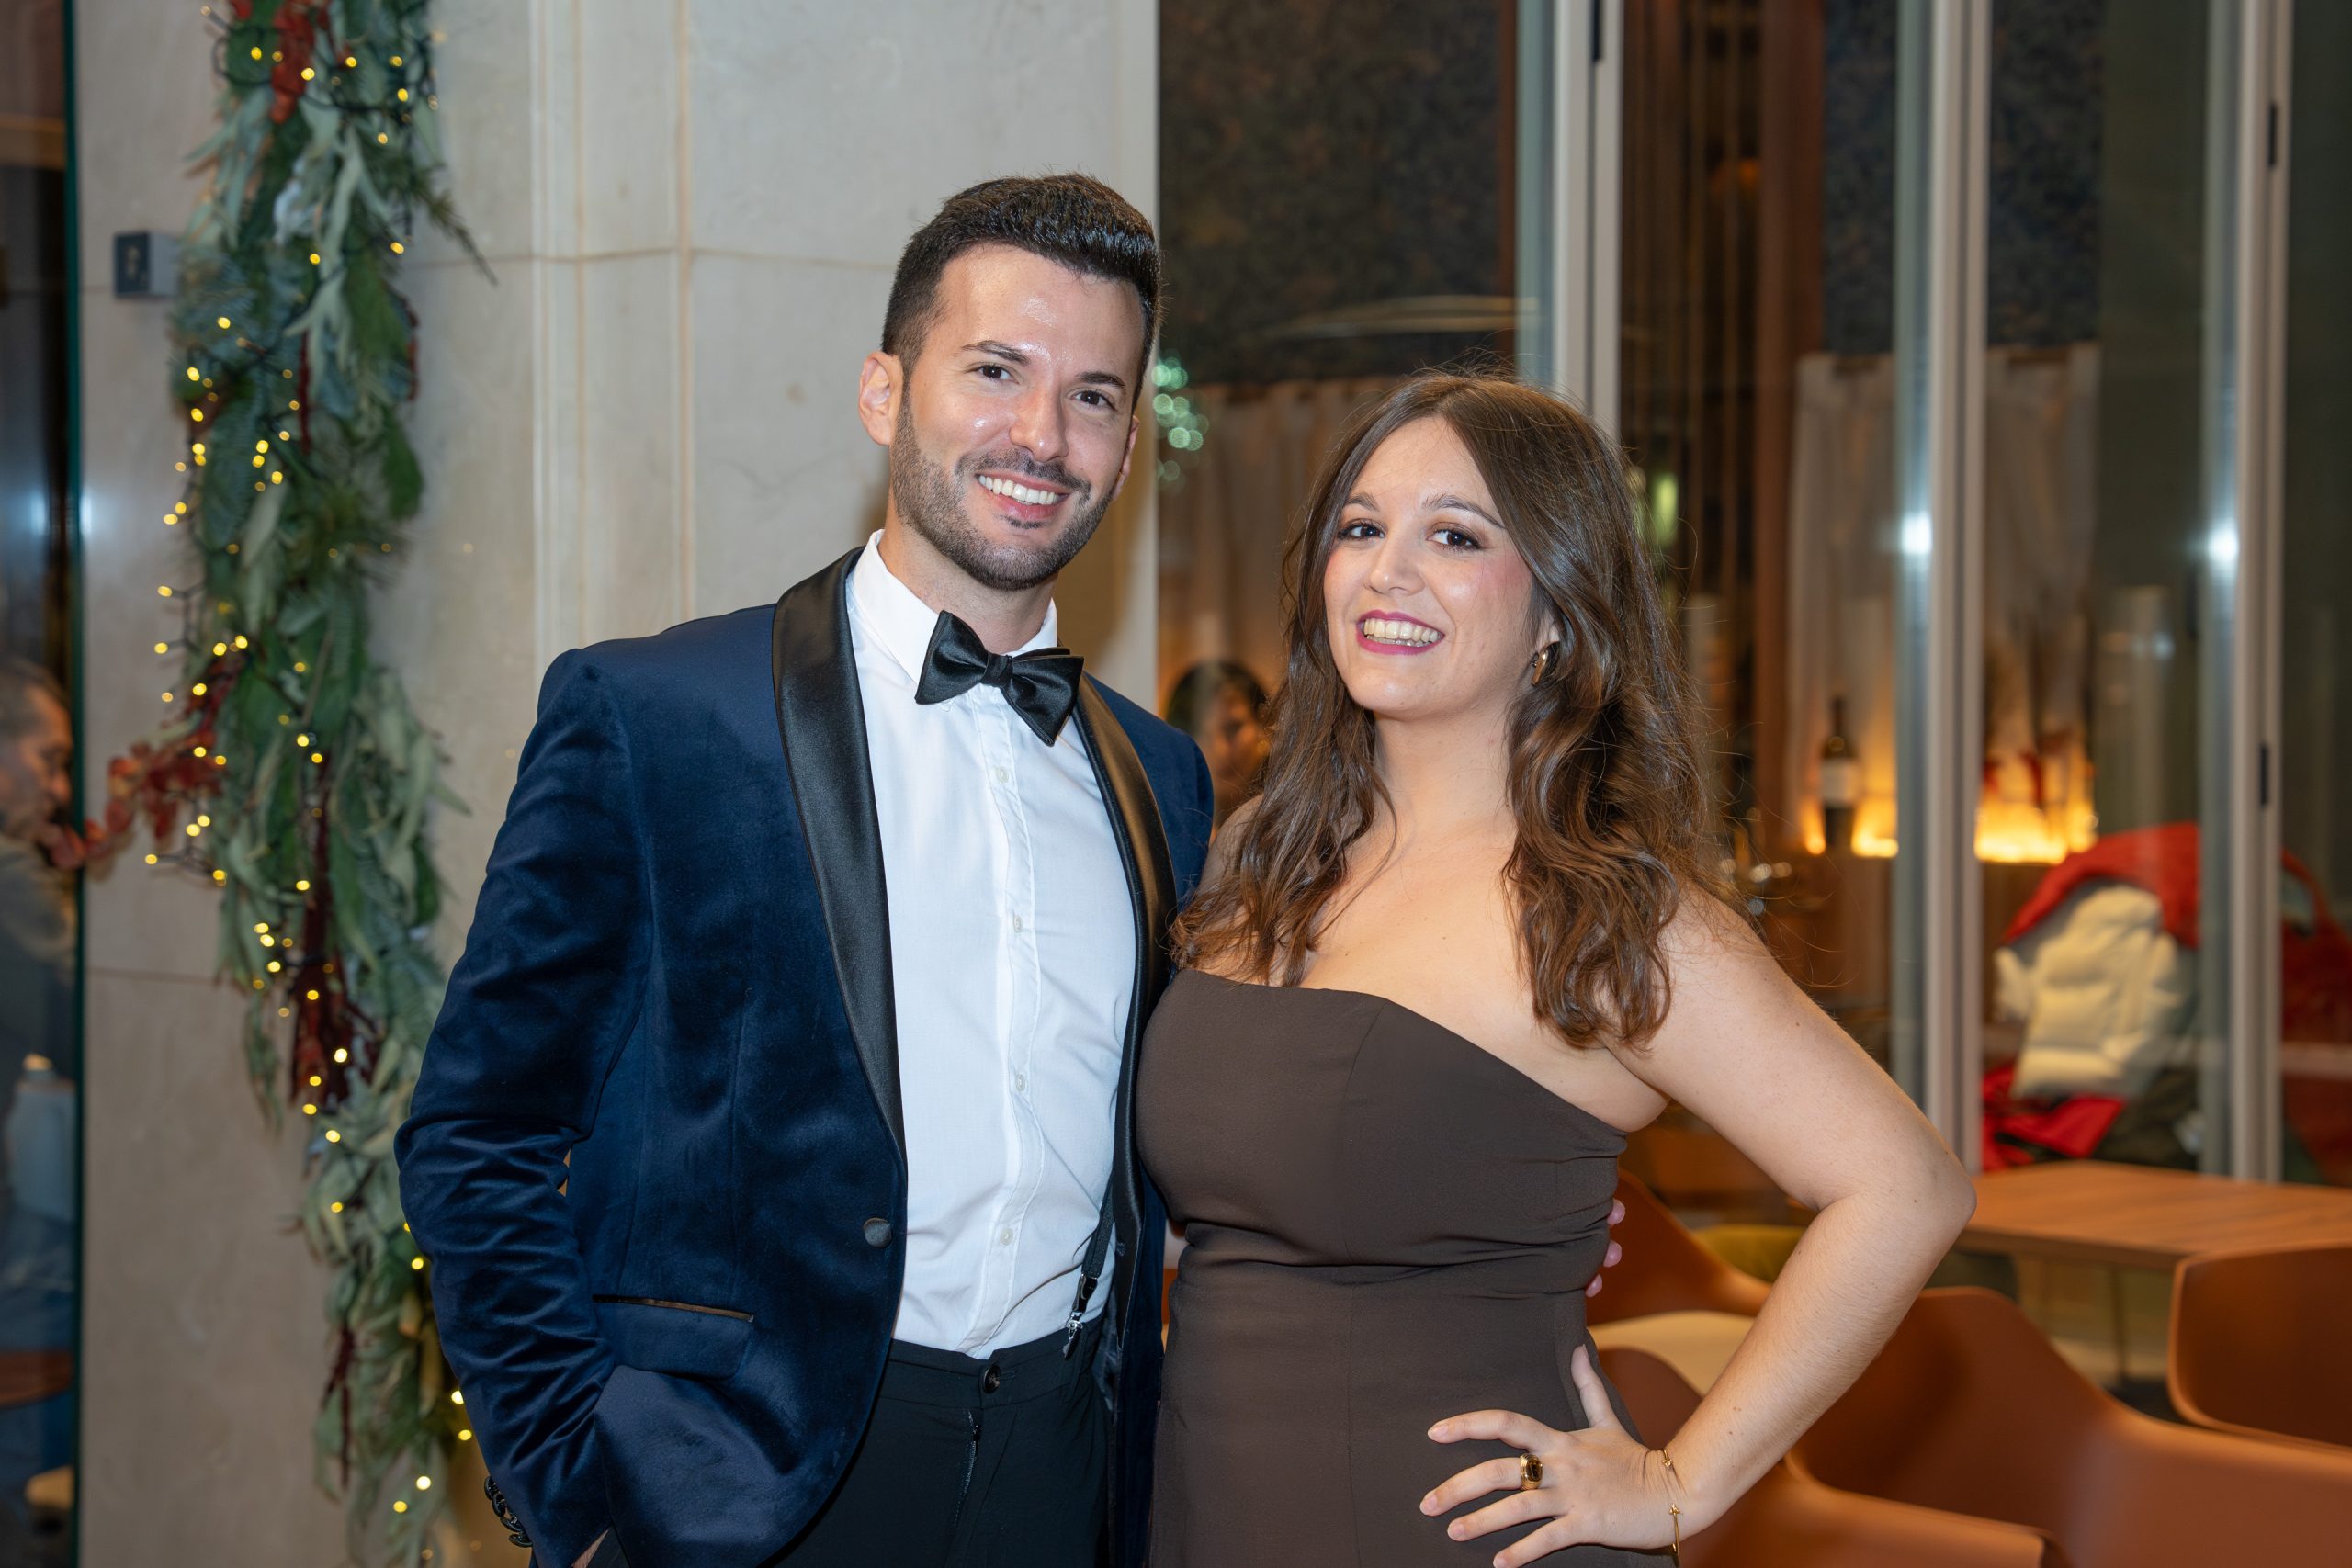
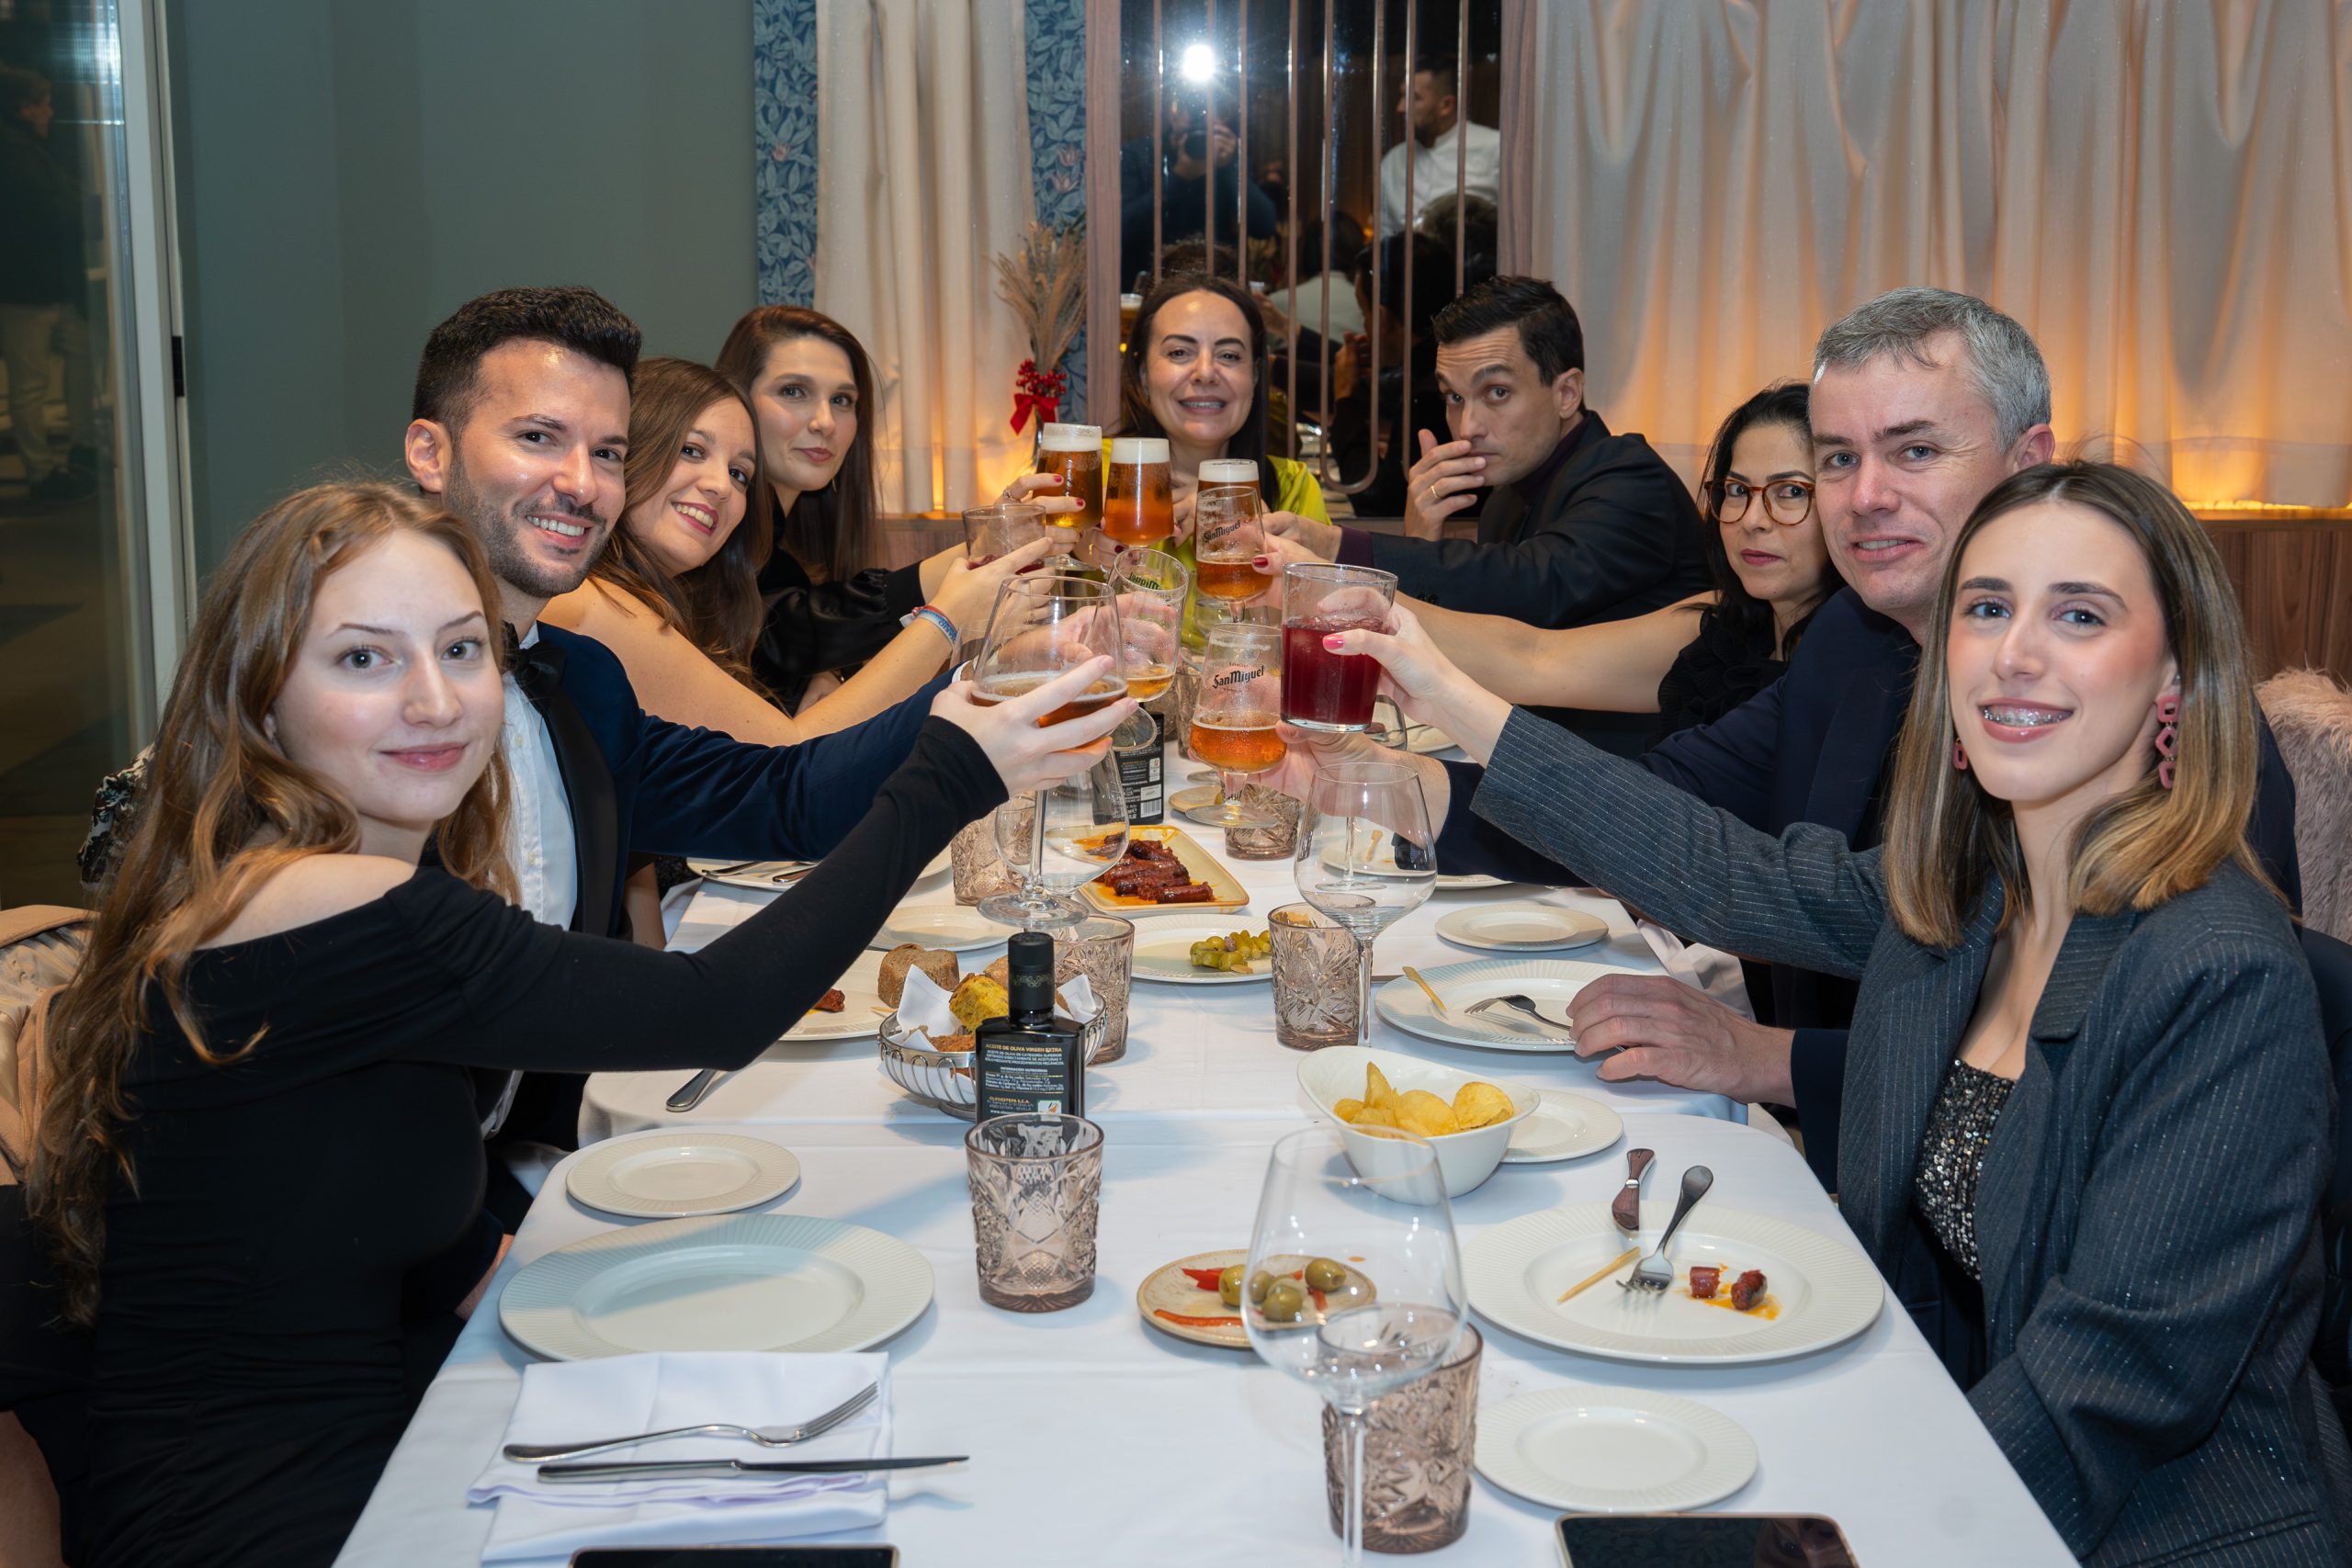
We would like to share some moments from our Christmas dinner, a time to pause, share, and give thanks for the great work done by the entire team throughout the year.

Laughter, good company, and lots of enthusiasm to continue growing together. Thank you to everyone who is part of MDG Advisors and makes this project possible every day.

✨ Here’s to a new year full of challenges and shared successes!


We wish you a Merry Christmas

From all of us at MDG Advisors, we wish you a Merry Christmas and a joyful holiday season. Thank you for your trust, collaboration, and continued support throughout the year.

Verifactu moratorium: What your company needs to know about this.

In December 2025, the Government approved a further extension of the obligation to implement the Verifactu verifiable invoicing system. (Legal News)

The new effective dates are:

  • For companies subject to corporation tax: 1 January 2027.
  • For all other companies and, where applicable, self-employed persons and professionals: 1 July 2027.

In practice, this means that the formal obligation to issue invoices under the Verifactu standard is postponed for an additional year.

What is Verifactu and why does it matter?

Verifactu is the electronic invoicing system designed by the Tax Agency (AEAT) whose objective is to guarantee the authenticity, integrity and traceability of invoices issued by companies and professionals.

Invoices issued under Verifactu must be generated using certified software, include a unique identifier and, where applicable, a QR code, and be securely recorded so that the AEAT can access them at any time.

The purpose of this regulation is to strengthen controls against tax fraud, improve transparency and standardise electronic invoicing in Spain.

What does the moratorium mean for your company?

The positives — more time to prepare for the transition

  • Additional time to adapt systems: If you have not yet incorporated compatible software or are in the process of implementing it, you now have more time, until 2027, to do so at your leisure.
  • Less rush for immediate technological investment: Avoid hasty decisions in December 2025 — you can plan ahead with greater foresight.
  • Opportunity to calmly review internal processes: Opportunity to coordinate accounting, invoicing, filing and internal reporting before the requirement comes into effect.

But that doesn’t mean you can leave everything to the last minute

  • The moratorium only postpones the requirement; the system is still planned. You must continue planning.
  • If your company had already begun the adaptation process — changing software, internal processes, training — you should review those plans in light of the new deadline (and anticipate that suppliers will update their software).
  • Regulatory uncertainty remains: the postponement reflects organisational difficulties, which underscores the importance of accompanying the transition with advice.

What our consultancy would recommend — steps to take now

As your consultancy, we propose the following actions to take advantage of the extra time and ensure an orderly transition:

  1. Evaluation of the current invoicing system
  2. Check whether your invoicing software meets the technical requirements of Verifactu (certification, unalterable registration, possibility of generating unique identifiers, etc.).
  3. Planning for technological adaptation
  4. If it is necessary to change or update software, define internal deadlines, costs, testing and staff training well in advance.
  5. Design of robust internal processes
  6. Prepare a standard procedure for issuing, archiving and backing up invoices in accordance with the new system; define responsibilities within the company.
  7. Internal communication and training
  8. Inform the entire team — finance, accounting, administration — about the importance of the new regulations and their correct use.
  9. Simulation of adaptation scenarios
  10. Conduct pilot tests with the new system before it becomes mandatory to detect errors or integration failures.

What this moratorium means for your company in the medium term

Although the moratorium may seem like a respite, it does not eliminate the obligation—it only postpones it. The ideal approach is not to wait until 2026 or 2027 to act, but to take advantage of this margin now to:

  • Calmly implement a modern invoicing system.
  • Reduce the risk of future penalties for non-compliance.
  • Optimise accounting and administrative processes, improving efficiency and thus saving time and costs.
  • Take advantage of the transition to implement good internal control practices and secure digital archiving.

Conclusion

The government’s decision to postpone the mandatory implementation of Verifactu until 2027 offers your company a valuable opportunity to adapt at your own pace. However, realistically speaking, the moratorium should not be interpreted as an indefinite delay: the system will become mandatory, and it is advisable to prepare as soon as possible.

Our tax advisory service is at your disposal to accompany you throughout the process: from evaluating your current system to implementing the new software, including training your team and defining internal processes. If you wish, we can organise an information session for clients, explain the regulations in detail and prepare a personalised action plan tailored to your structure.