admin

Measures To Avoid International Double Taxation

On numerous occasions, individuals and entities may be exposed to being taxed on the same income, profit, or asset in more than one country due to discrepancies in tax regulations between jurisdictions. This tax issue can generate a duplicate tax burden, negatively impacting those individuals and legal entities that carry out their operations internationally.

For this, it is essential to put in place measures to prevent international double taxation in the tax area, ensuring fairness and efficiency in the taxation of income that could be taxed in more than one country. These measures are mainly divided into unilateral and bilateral measures.


UNILATERAL MEASURES:

Unilateral measures refer to decisions taken individually by individual states within the scope of their domestic legislation. In the context of Spanish legislation, this includes the provision on the deduction for international double taxation, applicable to both natural and legal persons, and regulated in the Personal Income Tax (IRPF) and Corporate Income Tax (IS) regulations, respectively.


BILATERAL MEASURES:

Bilateral measures arise from the collaboration between two States that sign a Double Taxation Avoidance Convention (DTA). These agreements seek to clarify and unify the tax situation of individuals and entities involved in international activities. The Double Taxation Conventions, of which Spain has signed several with different countries, seek to address and resolve these issues. The provisions established in these treaties and conventions take precedence over domestic tax regulations, being automatically and compulsorily applicable, with no possibility of waiver.

The provisions established in these treaties and conventions take precedence over domestic tax regulations, being automatically and compulsorily applicable, with no possibility of waiver. The Double Taxation Conventions, of which Spain has signed several with different countries, seek to address and resolve these issues. Therefore, the first step in determining the tax treatment of income obtained in Spain by a non-resident is to identify the country of tax residence and verify the existence and content of the Double Taxation Agreement with that country, in order to define the tax treatment corresponding to that income.


In conclusion, international double taxation involves complex challenges for individuals and entities with international operations. Both unilateral and bilateral measures are essential pillars to ensure fairness and efficiency in cross-border taxation, preventing duplication of tax burdens and establishing a robust framework to address tax complexity in an international environment.

Sandra Gámez Chaves
The limited verification procedure of the Tax Agency and its importance in tax management.

The Tax Agency, in its tax collection work, has various tax procedures to verify and audit the economic activity of taxpayers within the tax administration itself, where it finds its regulatory motivation in articles 117 and 123, among others, of the General Tax Law (hereinafter, LGT).


One of these procedures is the limited verification procedure, a tool that allows the tax administration to review certain aspects of the tax return without carrying out a full audit. In this article, we will explore what the limited verification procedure consists of, how it works and its importance in the field of taxation and tax compliance.


What is the limited audit procedure?


The limited verification is an audit procedure that the Tax Agency regulates in article 136 et seq. of the LGT. This procedure is carried out to verify the correctness of certain aspects of a taxpayer’s tax return without the need to review the taxpayer’s entire tax situation. Unlike a full inspection, which involves an exhaustive analysis of all tax aspects of a person or company, the limited verification focuses on specific and concrete issues.


This procedure is used when the tax administration detects indications of tax irregularities or non-compliance in one or more items of the tax return. Instead of initiating a full inspection, which can be costly and time-consuming, the limited audit focuses on resolving the identified doubts or irregularities.


How does the limited audit procedure work?


The limited audit procedure starts with a notice to the taxpayer informing him that a review of certain aspects of his tax return will be carried out. This notice usually details the items or concepts that will be subject to review. For his part, the taxpayer must cooperate with the Tax Administration by providing the information and documentation requested within the deadline established for this purpose.


During the limited verification process, the Tax Agency reviews the documentation provided by the taxpayer and carries out the necessary checks to verify the correctness of the items being investigated. This process may include the review of invoices, contracts, financial statements and any other relevant documents that provide reliable information about the liquidation of a certain tax.


Once the review is completed, the Tax Agency issues a report with the results of the limited audit. If tax irregularities or non-compliance have been identified, the taxpayer will be notified and given the opportunity to make representations and correct the discrepancies.


Importance of the Limited Audit.


The limited audit plays a fundamental role in the tax system, as it allows the Tax Agency to verify the correctness of tax returns without having to carry out full inspections on all taxpayers. This streamlines the audit process and allows the tax administration to focus on the cases with the highest risk of non-compliance.


In addition, the limited audit promotes transparency and voluntary compliance with tax obligations. Taxpayers who know that the tax administration can review certain aspects of their tax returns are more likely to file accurate returns and comply with their tax obligations.


On the other hand, the limited audit also protects taxpayers’ rights, as it avoids intrusive and costly inspections when they are not necessary to the specific case. This helps to maintain a balance between tax control and the protection of taxpayers’ privacy and rights.


In conclusion, the limited verification procedure of the Tax Agency is an essential tool to verify the correctness of taxpayers’ tax returns. It allows a targeted review of specific aspects, streamlining the audit process and encouraging voluntary compliance with tax compliance. At the same time, it protects taxpayers’ rights by avoiding costly and/or unnecessary inspections. In short, the limited audit is an effective mechanism to guarantee the integrity of the tax system.


Jesús Raya.

Impatriate regime: The so-called Bekcham Law also has census obligations in November

Our firm advises taxpayers covered by the Special Regime for Workers Posted to Spanish Territory to review their tax situation for the 2024 tax year in November, as some of them may have to comply with certain census obligations.

This special regime, also known as the Beckham Law, allows individuals who have acquired their tax residence in Spain as a result of moving to Spanish territory for work purposes to pay Non-Resident Income Tax.

Following the publication of Law 28/2022, of 21 December, on the promotion of the start-up ecosystem, this regime has undergone changes, which came into force on 1 January 2023:

  • Previously, it was required not to have been resident in Spain in the ten tax periods prior to the move to Spanish territory, reducing this figure to just five years.
  • The move had to take place as a result of an employment contract or appointment as a director in a non-related entity. Currently, the fact of being a related entity does not exclude the regime, as long as it is not an asset-holding company, and it is allowed to apply for new employment reasons, such as the performance of an entrepreneurial activity or an activity performed by a highly qualified professional providing services to emerging companies. There is also the option of applying as a spouse or child under the age of 25 or a child with a disability of a taxpayer covered by this scheme.


It lasts for 5 years, in addition to the year in which tax residence in Spain is acquired. However, there is the possibility of renouncing in the event that the taxpayer’s situation undergoes changes that result in less advantageous taxation. This renunciation should be made expressly in November and December, prior to the beginning of the calendar year, and with effect from the beginning of the calendar year. In the event that the taxpayer no longer complies with the requirements under which he/she joined the scheme, he/she must opt out of the scheme within one month of the non-compliance. Unfortunately, in both situations the taxpayer loses the possibility to opt back into the scheme in the future.

If you need help to opt out of this special regime, or to complete the census obligation to opt out this November, we are at your disposal.

Isabel María Díaz Rubio.

Form 232 and its implications for reporting related parties

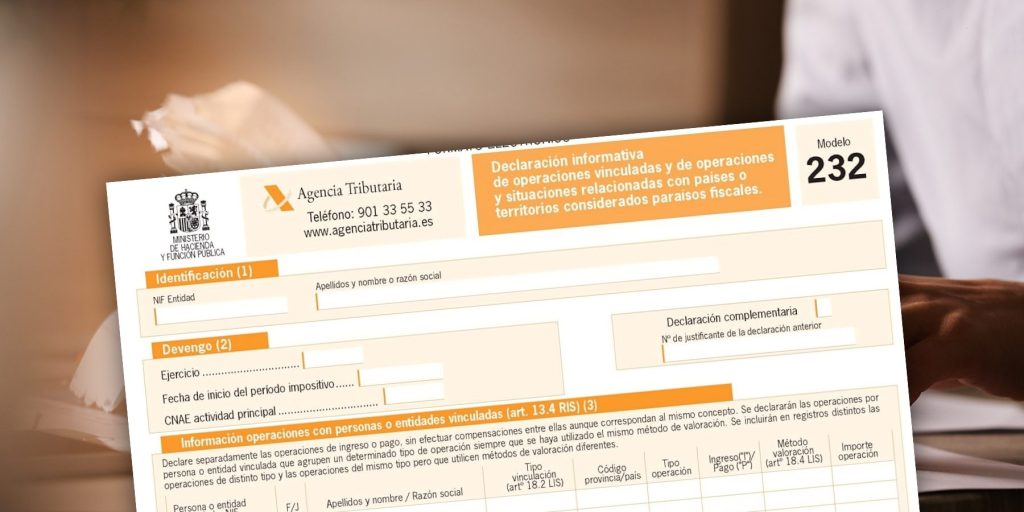
Form 232 is an information return in which the Tax Agency is informed of related-party transactions and transactions and situations related to countries or territories classified as tax havens.

Related-party transactions are regulated in Article 18 of the Corporate Income Tax Act.

The deadline for filing this form is within the month following the ten months after the end of the tax period. Therefore, if a company ends its tax year on 31 December, the deadline for filing is November.

There is an obligation to file this return when transactions are carried out with related persons or entities, according to the following assumptions:

  • – Transactions carried out with the same person or related entity for an amount greater than 250,000 euros.
  • – Specific transactions carried out, provided that the total amount of each of these types of transaction in the tax period exceeds 100,000 euros. Specific transactions are regulated in article 18.3 of the Corporate Income Tax Act.
  • – Transactions of the same type which in turn use the same valuation method carried out with a related person or entity accounting for more than 50% of the net turnover of a company.
  • – Transactions with countries considered tax havens.
  • – When the reduction in the tax base provided for in Article 23 of the Corporate Income Tax Act is applied for the assignment of certain intangible assets to related persons or entities.

In short, this is yet another tax obligation that companies must comply with if they are obliged to do so, so please do not hesitate to contact our team to resolve any queries you may have.

Sara Gámez Córdoba

Vat monthly refund register (redeme): advantages and disadvantages for companies

During the month of November, companies based in Spain have the possibility of voluntarily applying for inclusion in the monthly VAT refund register (REDEME). This register has an interesting financial attraction for those companies that need to improve their cash-flow in terms of VAT refunds as, through monthly returns, they will be able to apply for such a refund, which is normally quicker than the general annual refund that takes place in January for companies filing quarterly returns.

Being on the monthly refund register implies greater obligations, such as settling VAT on a monthly basis (form 303) and the obligation to keep the VAT register books through the AEAT’s Electronic Headquarters with the well-known SII (Immediate Supply of Information), increasing the administrative cost for the company.

However, the advantages provided by this system in conjunction with the SII are greater:

– Obligations are reduced, as there will be no need to file Forms 347, 340 and 390.

– The information provided by each company can be easily compared with that of other companies using the SII.

– Errors are reduced and management is simpler. Minimising errors can also avoid penalties and surcharges from the tax authorities.

– The deadline for filing monthly self-assessments is extended by 10 days.

– The time taken by the tax authorities to issue refunds is reduced because the checks are carried out more quickly.

– The information requests made by the tax authorities are reduced, as the information is already in their possession and they do not have to ask companies for it.

Weighing up the advantages and disadvantages and depending on the organisational and financial structure of the company, it may be interesting to opt for this system in November for the 2024 financial year. If you have any doubts about REDEME or SII, please do not hesitate to contact MDG Advisors.

Marina Guerrero Castronuño.

The Importance of anticipating the accounting and fiscal year end.

In the tax advisory world, November has historically been a month of “little” workload or during which we take the opportunity to dust off certain files and close them. This is mainly due to the fact that, in this month, there are no excessive filing deadlines, which gives us a certain margin for “creativity”.

Since the creation of our firm, we have always performed accounting and tax pre-closings in November for several reasons:

  • It is necessary to anticipate possible high results in the Corporate Tax, avoiding cashflow issues.
  • As a general rule, companies close their fiscal year on December 31st , so that a closing in November and a meeting with the client is a highly valued action, since it gives the possibility of adopting measures before the closing that help to reduce the tax burden: bonus distribution, investments, etc.
  • Proactive advice: this concept is always an added value. With the era of digitalization, our role has been shedding the label of accountants to give more room to that of advisors. Therefore, our job is to advise the client and this is not achieved without proactivity. In our experience, clients place considerable value on receiving news about the performance of their companies before it is too late.


For these reasons it is necessary and advisable to anticipate the year-end closings to the month of November, giving flexibility to all our clients.

We hope you find this information useful. Should you have any queries, please get in touch with us.

Pablo Mallo.

The analysis of the Double Taxation Agreements and their implication in the “Temporary” Tax on large fortunes and in the Wealth Tax.

Now that we are familiar with the “temporary” tax on large fortunes, and after having received resolutions from the Tax Agency in which it seems that they are not in favour of giving their arm to twist in favour of the taxpayer, at least in the first instance (later we will see who wins the battle), we consider of special relevance to point out the importance of the analysis of the Double Taxation Agreements and their implications in this new “temporary” tax that has given us so many headaches, as well as in the Wealth Tax.

As a complement to a blog published by our firm in May 2023, in this case, we would like to highlight the importance of analysing the Double Taxation Agreements and their tax implications in each specific case presented by the taxpayer, before delving into the interpretation of the internal regulations of our country.

We are all aware of the modifications introduced by Law 38/2022, of 27 December, in terms of the regulatory changes affecting the taxation of companies not resident in Spain, but if there is anyone who is not aware of them at this time, we will explain them below:

New wording of 5.One.b) of the Wealth Tax Law real obligation:

“For these purposes, securities representing equity interests in any type of entity, not traded on organised markets, at least 50 per cent of whose assets are directly or indirectly made up of real estate located in Spanish territory, shall be considered to be located in Spanish territory. For the purpose of calculating the assets, the net book values of all the assets entered in the accounts shall be replaced by their respective market values as determined on the date on which the tax accrues.

In the case of immovable property, the net book values shall be replaced by the values that must be used as the tax base in each case, in accordance with the provisions of Article 10 of this law”.

Following the aforementioned amendment, our firm has received many enquiries from non-resident clients with direct or indirect participation through companies with real estate located in our country.

But the question is, does this modification affect all non-resident taxpayers who asked our firm? The answer to this question is that it is important to analyse each specific case, and in tax terminology, each Double Taxation Agreement in question.

In order to summarise whether or not the modification introduced in the aforementioned article 5.1.b) of the Wealth Tax Law has implications in your specific case, we summarise the tax implications in three large blocks:

– It will only affect countries without Double Taxation Agreements or with Double Taxation Agreements, but which do not contemplate Wealth Tax, so we would have to resort to domestic regulations: Andorra, Algeria, Australia, Brazil, Qatar, USA, China, Korea, Finland, Ireland, Ireland, Spain, France, Italy, Portugal, Spain and Portugal, China, Korea, Finland, Ireland, Italy, Japan, Portugal, Singapore; and with suspensive or resolutory character Saudi Arabia, Croatia, Albania, Cape Verde, Philippines, Hong Kong, Jamaica, Malaysia, Malta, New Zealand, Oman, Pakistan, Dominican Republic, Romania, Senegal, Thailand, Vietnam, Colombia, Egypt and Nigeria.

– It will also affect double taxation treaties with a real estate companies clause in the same terms as the current domestic law: Belgium, France, Panama, Germany, India, Israel, Luxembourg, Mexico, Norway, United Kingdom, Armenia, Azerbaijan, Belarus, El Salvador, Slovenia, Republic of Georgia, Kazakhstan, Uruguay, Iceland, Moldova and South Africa.

– And finally, and in this case of GREAT IMPORTANCE, it does not seem to affect double taxation treaties that contemplate Wealth Tax and that do not have a clause on real estate companies, as they are transactions NOT subject to tax: Argentina, Austria, Canada, Chile, Emirates, Greece, Holland, Hungary, Iran, Kuwait, Morocco, Poland, Russia, Sweden, Switzerland, Venezuela, Bolivia, Bulgaria, Czech Republic, Cyprus, Costa Rica, Cuba, Ecuador, Slovakia, Estonia, Indonesia, Latvia, Lithuania, Macedonia, Serbia and Tunisia.

After the above, and as a conclusion to this blog, it is important to highlight the importance of analysing, in the first instance, whether or not it is subject to the specific tax to be applied, and for this, the first thing to do is to analyse the double taxation agreement of each country, so that in the event that it is subject to the tax in its territory, the internal regulations of each country can be applied to see if any exemption, rebate or deduction, among other cases, can be applied.

Therefore, from our firm, we always advise and offer our clients good advice specific to each taxpayer, since the tax implications in each case differ from others, so in tax matters, the GENERALIZATION of a case from one client to another, is not good advice.

Leticia Cayuela.

What documentation is necessary if I have just arrived to live in Spain? Assignment of NIE number at the request of the interested party and the Certificate of Registration of the European Union.

The Foreigner Identification Number (NIE) is a crucial element for all foreigners who wish to reside or work in Spain, whether they are EU citizens or not. This number allows them to identify themselves in legal transactions and administrative procedures in the country. The NIE is essential for foreigners who study, work or carry out transactions in Spain for a period of three months or more.

There are two main categories, the assignment of a NIE number at the request of the interested party also known as the “White” NIE or the European Union Citizen Registration (CUE), popularly known as the “green” NIE.


Assignment of a NIE number at the request of the interested party.

The assignment of a NIE number at the request of the interested party is given in folio format and shows the holder’s personal data, including name, surname(s) and the identification number provided by the authorities. This NIE serves mainly as an identification and allows to carry out legal transactions, but does not confer any permanent residence rights.

The “White” NIE is issued to both EU citizens and foreigners of other nationalities. In some cases, such as when EU citizens wish to start working in Spain, they will need this number in order to register with the social security before obtaining their EU Citizen Certificate.


European Union Registration Certificate

The Certificate of Registration as a European Union Citizen (CUE) is a definitive or permanent identification. If an individual already has a “White” NIE, this number remains valid when obtaining the EU Registration Certificate.

To apply for a CUE, certain requirements must be met, depending on the individual’s personal situation, such as being self-employed, employed, a student or demonstrating sufficient financial resources, as well as having private health insurance without co-payments where this is required.

The documents required will vary according to the situation and may include a passport, the EX-18 form, proof of payment of fees and, in some cases, documents supporting the applicant’s status.


In summary, both the assignment of a NIE number at the applicant’s request and the Certificate of Registration as a European Union Citizen are essential for foreigners wishing to settle in Spain. The former is a provisional identification, while the latter is a permanent registration certificate for EU citizens who meet specific requirements.

Reversal of the taxable person in the execution of works

In the field of real estate development and, specifically, in the execution of works carried out between developer and contractor, it is common to find the figure of reverse charge in this area; however, how does this figure work and how is it regulated?

First of all, it should be noted that reverse charge is the figure in which the legislation provides, in certain cases, that the taxable person is the business or professional who receives the supply of the goods or the provision of the service, being an exception to the general rule that the taxable person for VAT will be the business or professional who supplies the goods or provides the service. Thus, the recipient of the good or service will be the one who will charge VAT to himself, having input VAT and output VAT for the same transaction.

In the field of construction work, its regulation is contained in Article 84.1.2 letter f) in which the taxable person may opt for the inversion of the taxable person for this modality, with or without the contribution of material, as well as in the transfer of personnel, and which are the consequence of contracts directly formalised between the promoter and the contractor and whose object is the urbanisation of land or the construction or rehabilitation of buildings.

Thus, it is necessary to establish the definitions and requirements for VAT purposes for each of these modalities:

 a) Land development: according to the DGT, the development of land is all those actions that are carried out to provide the land with the elements provided for by urban planning legislation (road access, water supply and drainage, electricity supply, etc.).

 b) Buildings: the definition of buildings, in accordance with the provisions of Article 6 LIVA, which establishes that buildings are constructions permanently attached to the ground or to other real estate, both above and below ground, which can be used independently and autonomously.

 c) Refurbishment: the definition of refurbishment can be found in the tax regulations themselves, where Article 20.Uno.22.B) states that:

  • That more than 50 percent of the total project cost corresponds to consolidation works or treatments of structural elements.
  • That the total cost of the works referred to in the project exceeds 25 percent of the purchase price of the building under certain conditions.

For practical purposes, and once the necessary requirements have been met to be able to apply the reverse charge in the execution of the work, the invoice issued must include a legend expressly stating that the transaction is covered by this type of reverse charge.

Therefore, the reverse charge in the execution of works is a modality that facilitates the liquidity of high value works in the real estate market with minimal interference from a tax point of view, since by using this figure, companies do not find themselves in the position of having to advance payment of VAT, despite its future deductibility and/or refund by the Tax Agency.