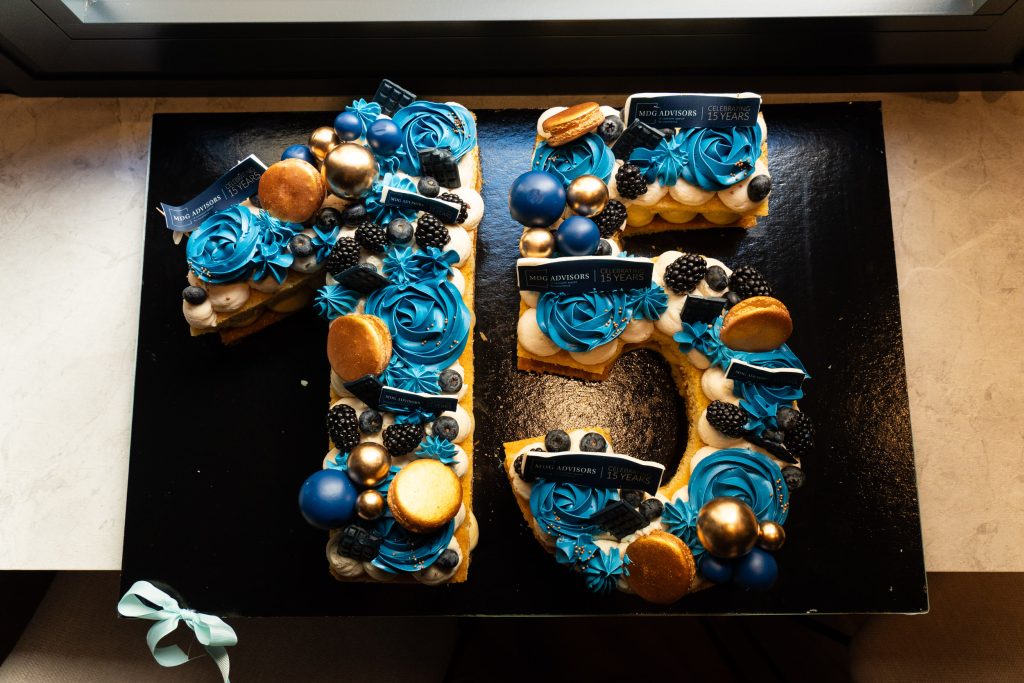2025 ENG

How to inyect funds in a Spanish Limited company ?

In the real estate business, especially when dealing with Spanish companies, one of the most common questions we receive is:
“What is the best way to inject funds into a Spanish Limited Company — through a loan agreement or a capital contribution?”

Both methods are valid, but they have different financial and tax implications depending on the company’s structure, objectives, and tax residence.

1. Loan Agreements
Funds injected through a loan are recorded as a liability in the company’s accounts. Interest may be payable to the lender and could be deductible or taxable depending on the jurisdiction. In some cases, repayment or interest may be restricted or subject to withholding taxes.

2. Capital Contributions
Capital contributions increase the company’s equity. They usually do not require repayment or interest, but can affect the shareholding structure and have corporate tax implications.

Choosing the Right Option
The decision depends on tax efficiency, fund repatriation, and the company’s long-term strategy. Because rules vary by country, it is essential to consult a qualified tax advisor before deciding.

Fontán and Zubizarreta: 30 Years of Legal Excellence in Marbella

With more than three decades of experience, Fontán & Zubizarreta Lawyers has established itself as one of Marbella’s most respected law firms. In such a dynamic and cosmopolitan city, its history reflects commitment, professionalism, and a deep connection with the local community. The firm has accompanied Marbella’s evolution —from challenging periods to its consolidation as an international destination— growing alongside the city and adapting to the changing realities of the legal world.

Inspired by key figures such as Lorenzo Ruiz Barrero, who shaped a way of practicing law based on clarity, closeness, and excellence, the team at Fontán & Zubizarreta remains firmly client-focused. “Listening is just as important as advising,” say the partners, convinced that trust and empathy are the cornerstones of quality legal service. Their approach combines tradition and experience with a modern outlook, providing effective solutions for an international and demanding clientele.

Should a Non-Resident Heir Pay Taxes in Spain?

This is one of the most common questions we receive at MDG Advisors, especially from clients with assets or family members in different countries.

However, the answer is not as simple as a “yes” or “no.” It depends on two main factors: where the assets are locatedand the tax residency status of the deceased.

👉 If the assets are located outside Spain, the non-resident heir is not required to pay taxes in Spain.

👉 If the assets are located in Spain, it is necessary to analyze the status of the deceased:

  • Deceased non-resident: The heir must file the state-level self-assessment, and may choose the autonomous community where the value of the assets would have been highest.

  • Deceased Spanish tax resident: The heir must also file the state-level self-assessment, but may apply the regional regulations corresponding to where the deceased resided during the last five years.

In short, the taxation of international inheritances requires a detailed analysis of each individual case. At MDG Advisors, we help our clients understand their tax obligations and optimize their tax burden both in Spain and abroad.

Time Recording: Is Electronic Clock-In Mandatory?

In recent months, many companies have been receiving communications or recommendations from external suppliers who insist on the supposed mandatory nature of electronic time recording. This situation has caused some confusion, especially among SMEs and self-employed workers with employees. However, as of today, current labour legislation in Spain does NOT require clocking in to be done using electronic systems.

📌 What does the current legislation say?

Article 34.9 of the Workers’ Statute, following its amendment by Royal Decree-Law 8/2019, establishes that all companies must ensure the daily recording of the working hours of their employees. But the important thing is this:

🔍 The law does not establish a mandatory format for such recording.

This means that time control can be carried out either electronically or on paper, provided that it is reliable, accessible and available for possible labour inspections for at least four years.

📄 Is paper recording valid?

Yes. Manual paper recording is still perfectly legal, provided that it meets the following requirements:

  • It records the start and end times of each employee on a daily basis.
  • It is accessible to the employee, the company and the Labour Inspectorate.
  • It is kept for the legally established period.
  • It is signed or validated by the employee.

🚫 What about external platforms that require it?

Many companies that provide HR or occupational risk prevention software are promoting the implementation of digital clocking-in systems, presenting them as ‘mandatory by law’. Although these systems can offer management and control advantages, they are not legally required.

✅ Conclusion

To date (October 2025), there is no regulation requiring companies to implement an electronic time recording system. What is mandatory is to keep track of working hours, and this can be done manually, on paper or using digital tools, depending on the reality and needs of each company.

Aaron Cheung Gallardo.


🎉 Celebrating 15 Years of MDG Advisors!

A huge thank you to our team, clients, and partners for being part of this incredible journey. Here’s to many more years of growth, innovation, and shared success!
#MDGAdvisors #15Years #Anniversary #Teamwork #Innovation

Lease with option to purchase: tax obligations for non-residents in Spain

Real estate investment in Spain by non-residents has become increasingly important in recent years. Many owners opt for contractual formulas that allow them to profit from their properties without giving up the possibility of a future sale. One of the most commonly used is the transfer of use with option to purchase, a concept that combines leasing with the transferee’s right to purchase the property within a specified period. In this article, we take an in-depth look at how income from this type of contract is taxed and what is involved in filing Form 210, in accordance with the provisions of the Directorate-General for Taxation (DGT) in its Binding Ruling V1141-24.

The transfer of use with option to purchase consists of a contract whereby the owner of a property transfers its use to a third party, usually through a lease, also granting them the right to purchase it in the future. This right can be exercised within a specified period and under previously agreed conditions. During the transfer period, the transferee pays a periodic rent for the use of the property. Additionally, they may pay an initial amount—known as an option premium—which guarantees them the right to purchase the property in the future. This premium, although not constituting periodic rent, has direct tax relevance.

When the owner of the property is not a tax resident in Spain, the income obtained from the transfer of use of a property located in Spanish territory is considered income obtained in Spain. Therefore, it is subject to Non-Resident Income Tax (IRNR). This includes both the periodic income derived from the use of the property, which is considered real estate capital gains, and the amount received for granting the option to purchase, which is considered a capital gain. Both types of income must be declared using Form 210, although with different deadlines and criteria.

The amount received for granting the right of first refusal cannot be considered a simple advance on the sale price. It is a change in assets that generates a gain for the owner and, as such, must be taxed in Spain. The capital gain is determined as the difference between the amount received for the right of first refusal and the expenses and taxes paid by the owner in relation to said concession. The non-resident owner must file Form 210 within one month of the date on which the amount is received. This declaration is made as a capital gain obtained without the mediation of a permanent establishment. The applicable tax rate is 19% for residents of European Union countries, Iceland, or Norway, and 24% for residents of other countries.

If the transferee decides to exercise their right and the sale is formalized, the non-resident owner generates a second capital gain, this time from the transfer of the property. This transaction must also be declared using Form 210. The capital gain is calculated as the difference between the transfer value—that is, the agreed sale price, which may include periodic rents and the option premium if they have been deducted from the price—and the acquisition value, which includes the original purchase price of the property, acquisition costs (notary, registration, taxes), and any investments and improvements made. The declaration must be made within three months of the end of the month in which the sale is formalized.

If the option premium has already been declared as a capital gain at the time of its granting, and this is included in the sale price, it is essential to avoid double taxation on the same amount. To do this, it is recommended to subtract the amount already declared from the transfer value and provide a copy of Form 210 previously submitted for the option premium.

In order to correctly comply with the tax obligations arising from this type of contract, it is essential to properly identify each type of income, file Form 210 within the established deadlines, keep all contractual documentation, and consult the double taxation agreements between Spain and the owner’s country of residence. Leasing with an option to purchase is an effective tool for making real estate in Spain profitable, but proper tax management is key to avoiding penalties, errors, or double taxation. Both the option premium and the subsequent sale generate tax obligations that must be met with precision. Having expert advice and drafting contracts clearly can make the difference between a profitable transaction and an unexpected tax burden.

Teresa Romero Navas



✨ Incorporating a limited company online is now possible: digitalization in the commercial sphere

At MDG Advisors, we continue working to provide our clients with the best advice. That is why we want to share with you an important step forward in the digitalization of the commercial field: the possibility of incorporating a limited company with a cash contribution entirely online.

This initiative greatly contributes to the revitalization of the business and entrepreneurial fabric, saving time and resources.

Our firm assists clients throughout the entire process:

  • We help complete all the required information through the Citizen’s Notarial Portal.

  • We handle the necessary formalities so that clients can have a video call with the notary, avoiding travel and speeding up incorporation.

  • If an interpreter is required on the day of incorporation, there is no problem: our professionals arrange a three-way video call to provide full translation support.

At MDG Advisors, we make this innovative service available to our clients to simplify the creation of new companies and contribute to economic growth.

For further information about this improvement in the commercial field, please feel free to contact us.

Is the self-employed company director’s personal assets at risk due to their company’s debts?

Everyone understands that a self-employed person is liable with their personal assets for the debts generated by their professional activity, as there is no legal separation between their personal assets and those of the business. 

This is why many entrepreneurs believe that, by setting up a limited company, they are automatically protected from the business’s debts. However, if you are a self-employed company director, you should be aware that your personal assets may be at risk if you do not manage your responsibilities as a director properly.

There are several circumstances that can lead to a partner becoming a self-employed company director, one of the most common being when they are a director of the company and own more than 25% of the share capital.

In these cases, even though the company has its own legal personality, the director may be held personally liable if several conditions are met:

– Negligent management: If the director fails to fulfil their legal duties — such as not keeping accounts, not filing taxes or acting to the detriment of the company — they may be sued by creditors.

– Debts to the tax authorities or social security: The tax authorities and the Treasury may refer the debt to the director if they detect repeated non-payment, concealment of assets or lack of cooperation.

– Company in the process of dissolution: If the company enters into dissolution (due to losses, inactivity, etc.) and the administrator does not call a meeting or liquidate the company, they may be liable with their own assets for the debts incurred from that moment onwards.

–   Lifting of the corporate veil: In serious cases, the courts may ignore the legal personality of the company if it is proven that it has been used as an instrument to defraud or evade responsibilities.

For this reason, to help you protect your assets, we recommend that you maintain rigorous and documented management, comply with all tax, accounting and commercial obligations, and act with diligence and transparency. If you need help achieving this, do not hesitate to contact MDG Advisors and we will accompany you through the process.

Isabel María Díaz Rubio


✨ The Silent Elegance in Client Relations

When it comes to working in the legal and tax sector, one concept immediately comes to mind: silent elegance. A way of doing things with discretion, paying attention to detail, and providing a service that inspires trust without the need for ostentation.

This elegance is reflected in values such as respect, discretion, and closeness, especially in a place like Marbella, where international clients seek not only professional advice but also guidance in everyday aspects of life in Spain: from their children’s education to hiring household services. In this process, the line between professional and personal can sometimes blur, creating a bond of trust that often resembles friendship.

Maintaining consistent quality service over the years is no coincidence. It stems from a clear approach: being sincere, conveying values without embellishment, and supporting clients honestly. This way of working builds long-lasting relationships and consolidates a recognized professional trajectory.

Another key factor is the added value of having an international profile and deep knowledge of foreign tax legislation. This proves essential for those looking to invest in Spain and in need of comprehensive advice that bridges different legal and cultural realities.

Ultimately, true luxury in this field does not lie in what is visible, but in what is conveyed quietly: trust, closeness, and professionalism sustained over time.

How To Start A Business In Spain Without Being A Resident (And Actually Survive It)

Starting a company in a foreign country always sounds like an odyssey… and Spain is no exception. But if you’re thinking of setting up a Limited Liability Company (Sociedad Limitada or SL) without being a resident, here’s the good news: it’s absolutely possible.

Who can set up an SL in Spain?

Anyone, whether a person or a company, resident or non-resident, can create an SL in Spain. You don’t need Spanish nationality, nor do you need to live in the country. But — and this is important — there are a few steps you can’t skip, and if you’re a foreigner, you’ll likely need a bit more time and patience to get through them.

What do you need?

In a nutshell, you’ll need to:
1. Get a NIE (Foreigner Identification Number).
2. Choose a name for your company and check its availability.
3. Open a bank account in Spain and deposit the minimum share capital (€3,000).
4. Sign the deed of incorporation before a notary.
5. Obtain a provisional tax ID (NIF), and later the final one.
6. Register your company and get it listed with the Spanish tax authorities.

Translation: yes, there’s paperwork, especially if you’re not physically in Spain. But the good news is, many of these steps can be handled by a legal representative (power of attorney) or even remotely with an advisor.

What about taxes?

Here’s where things get interesting: even if you don’t live in Spain, your SL will still be taxed here.
You’ll need to comply with obligations such as corporate income tax, VAT (if applicable), and
keeping proper accounting records.

And if your administrator is also a non-resident, there might be fiscal residence implications, meaning you’ll need to pay close attention to where your company is considered a tax resident.

To sum up, starting an SL in Spain without being a resident is neither impossible nor prohibitively difficult, but it does require solid planning and expert guidance.

Your best move? Surround yourself with professionals who know the system and can help you avoid common mistakes.

Spain remains an attractive gateway to the European market, and the SL structure is flexible and accessible, a great option for both entrepreneurs and foreign companies looking to set up shop here.

Complicated? Not really, especially if you get in touch with MDG Advisors.

Sandra Gámez Chaves